

Episode 100! Benny & The Squirrel hit the century mark!! Markets into the midterms, the Anthropic IPO, why Google and Amazon got hammered while Oracle ripped, and the one trade that has held the book together since June.
The LLM Monitor

Show Summary
Anthropic IPO Note
The podcast kicked off with a 5-minute run through of the 🐿️’s weekend note on the Anthropic IPO. Find it (no paywall) by clicking on the image below.

Midterm Elections (Minute 5)
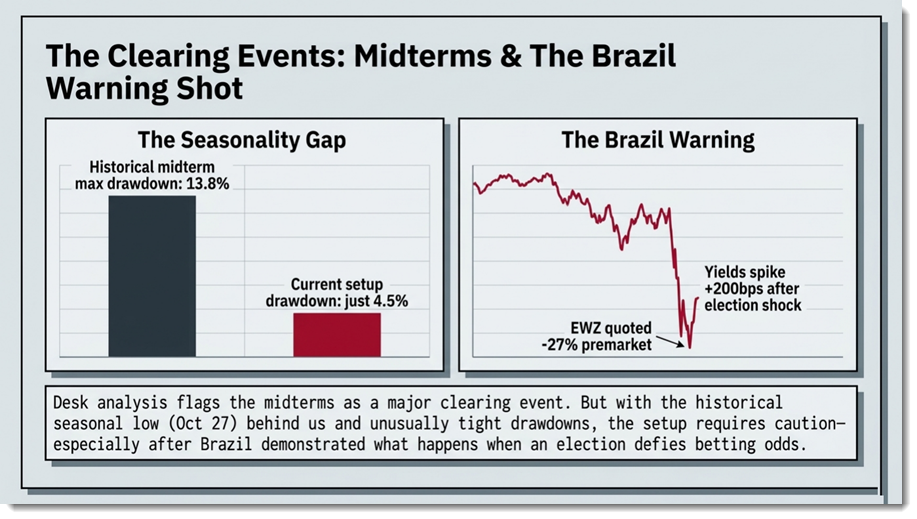
Brazil last week was a salutary lesson against treating political outcomes as foregone conclusions.
Pollsters have had a terrible decade; Democrats reportedly ahead in the Kansas Senate race, GOP more or less stopped funding North Carolina.
Structural wrinkle: Democrats need one extra seat because J.D. Vance holds the tie breaking vote as VP, and even then a one seat majority is fragile (the “Fetterman effect,” swing senators needing to be whipped or bought).
Polls cannot capture the sheer money in specific races: hundreds of millions from Musk on the Paxton versus Talarico Texas Senate Race; Musk’s total cycle spend is around half a billion dollars, making him the largest political donor in history, ahead of Soros.
Market Internals: Hidden Bear Market (Minute 7)
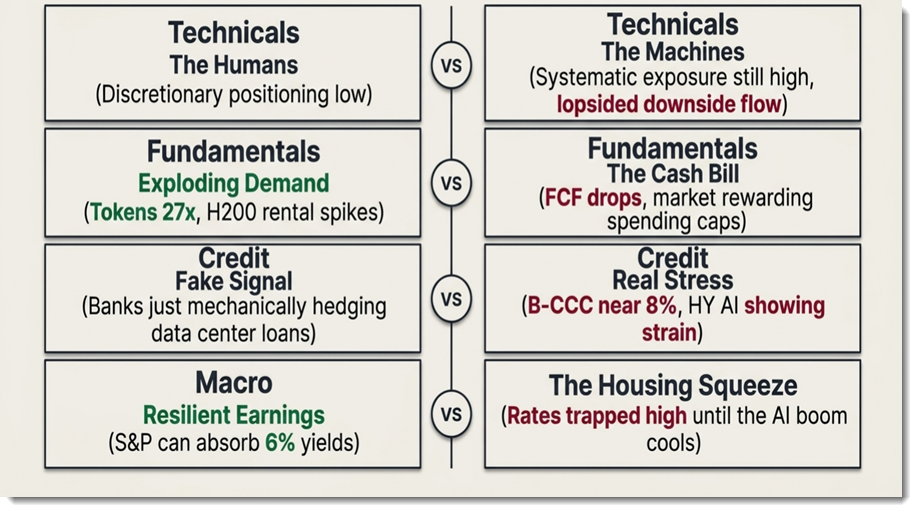
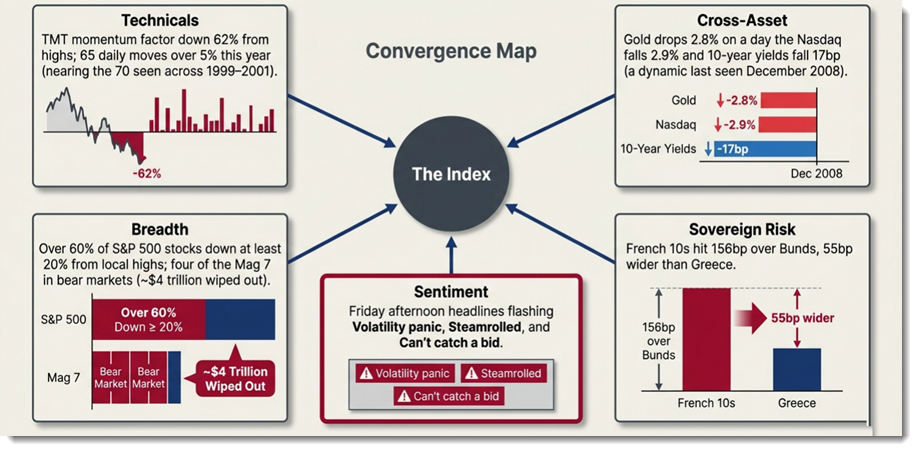
Recap of the structural bear market call: roughly 60% of individual stocks were already in bear markets (down 20% from highs).
Two distinct drawdowns: September hammered out of favour, rate sensitive and GDP sensitive names; October broadened the selling.
September weakness partly mechanical: many mutual funds and the government have a fiscal year end on 30 September, so tax loss selling of losers is traditional, with those names then resold into October.
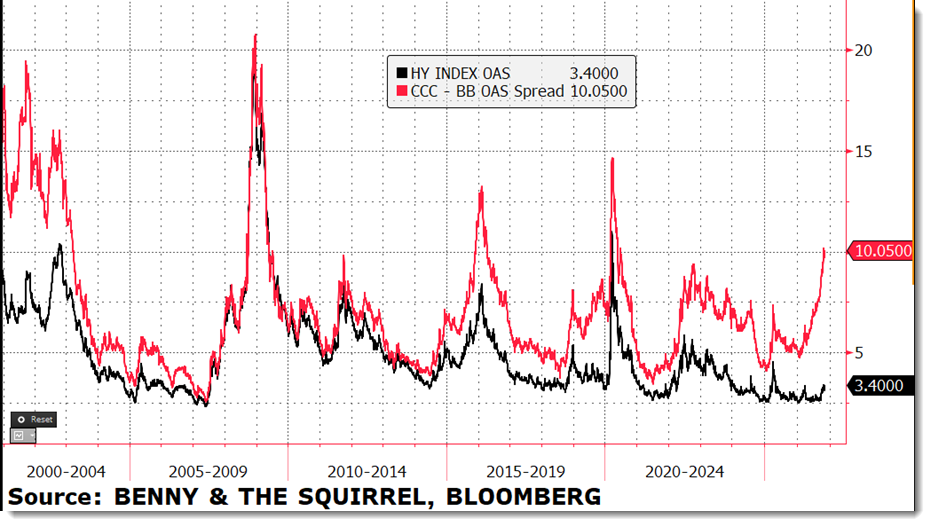
Triple C spreads show the biggest divergence “of the century” versus BB (the best of junk) and the high yield index average, though triple Cs are only a small sliver of the index, so no panic yet.
Is the credit story simply the continued selling of the most toxic remnants?
Ties into Mike Green’s passive dynamics: money comes in, spreads tighten, issuers keep hitting the bid; high yield still has capacity on a normalized basis.
IG is where hyperscaler TMT issuance has blown out spreads since last September; sector risk limits then force mechanical reallocation into other, sometimes terrible, credits at their best ever spreads relative to fundamentals.
Machines vs Humans (Minute 10)
The S&P index is only about 3% off its high, but the trading underneath has been violent: rate sensitives smoked in September then rebounded; tech held in then dumped.
Nasdaq futures sit near the 200 day moving average for the first time in a while.
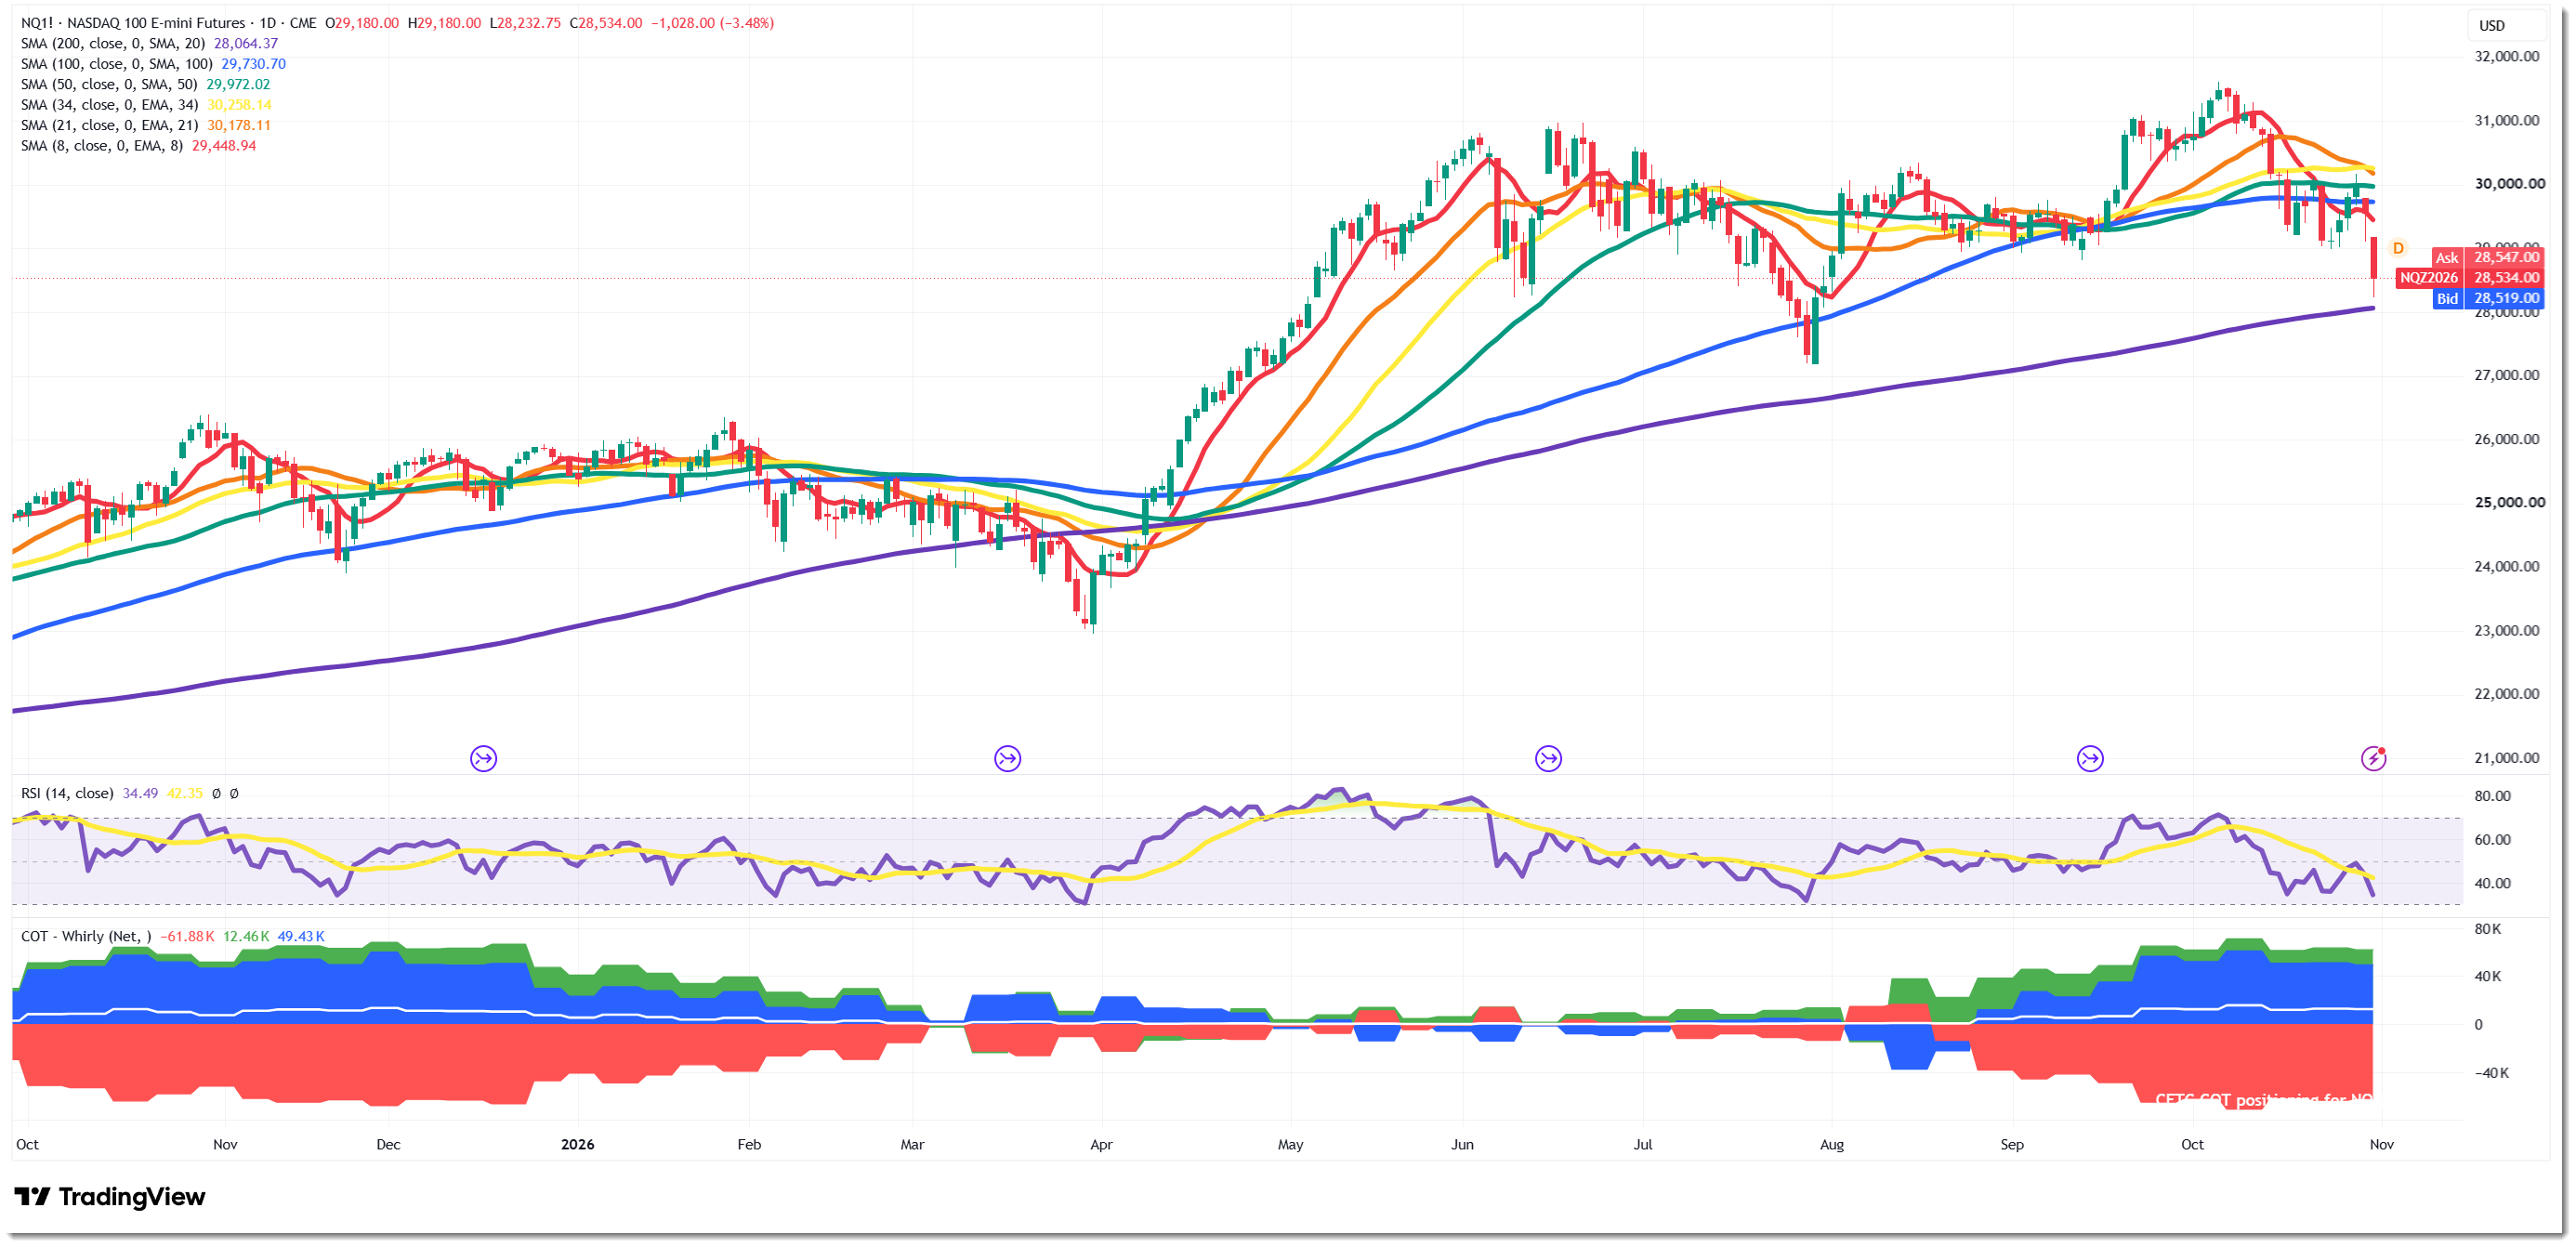
COT data (large and small spec length) shows the October drawdown barely dented positioning: the humans sold, the machines did not.
Sell side says CTAs have sold heavily, but the 🐿️, with 15% of NAV in trend strategies, sees no major equity index reduction in his own CTA holdings; vol target funds also remain very long because realized vol has remained depressed.
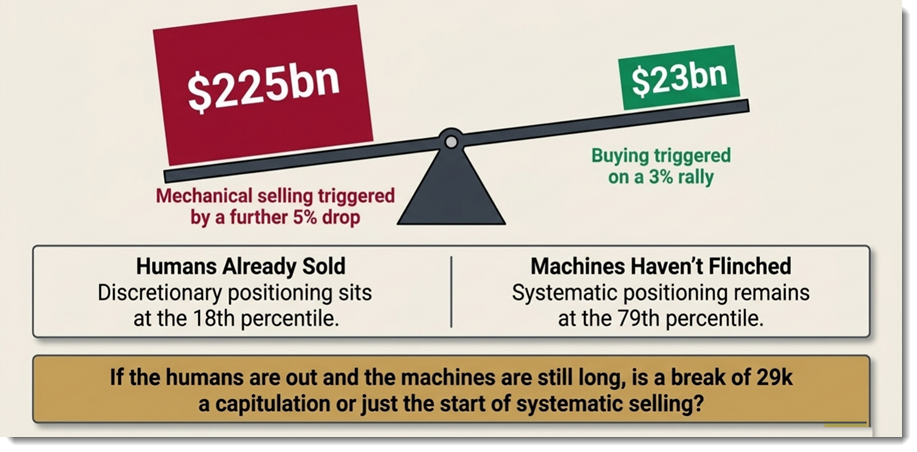
Thesis of Benny’s upcoming “casual barbell” essay: fewer humans matter at the margin than ever, so discretionary deleveraging is largely done and the systematic, mechanical players are the latent bag holders; if realized vol picks up, those are trapdoor sellers with no discretion.
Primary Supply (Minute 13)
Anyone under 41 on the Street has never seen a genuine multi year bear market (2022 probably does not count).
New and untested dynamic: the net supply of primary equity paper. Giant caps doing $90 billion equity raises and straight to the top of the index IPOs were flagged in May and June when they turned bearish on the AI trade.
The question to ask: why are the richest companies and executives in the world taking your savings, and why move down the capital stack to equity this early? Implication: the IG market was tapped out unless capital ratios improved first.
Hyperscaler Capex Reckoning (Minute 16)
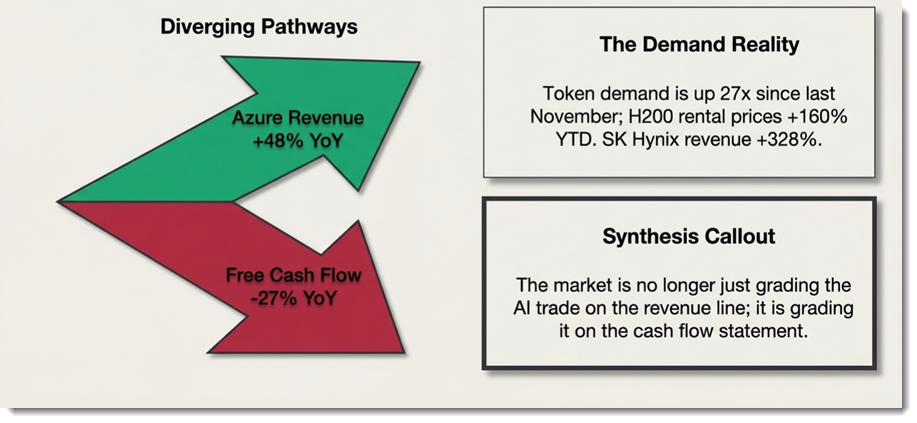
The narrative has shifted to free cash flow, which we flagged (way too early) back in April and May.
Oracle, “the dog of the hyperscalers,” rallied massively when Ellison merely hinted at spending a little less; Google and Amazon got hammered on their prints.
Cloud growth is no longer the driver; investors now watch capex and cash burn; relief rallies now come from spending restraint, and the revenue side of the AI equation remains unanswered.
Google: Search Erosion Arrives (18:30 to 22:10)
The “AI chatbots kill search” narrative from mid 2024 finally showed up in the numbers last quarter; those who bought that panic low did incredibly well.
Search erosion is coming home to roost alongside unyielding capex.
Both hosts pay for Gemini Pro and rate it highly (Nano Banana image generation is best in class), yet Google now front runs its own search links with AI summaries.
Framing from the NYC dinner with Mike and Hari: “search” is retrieval, “ask” is intelligence, and “ask” is coming for the search business.
Defence of Google: to stay in the retail LLM game it had no choice but to put its advertising cash cow at risk; unlike Kodak or newspapers, it is at least being proactive, but the fundamentals of its old utopia have changed.
Politics Returns (Minute 22)
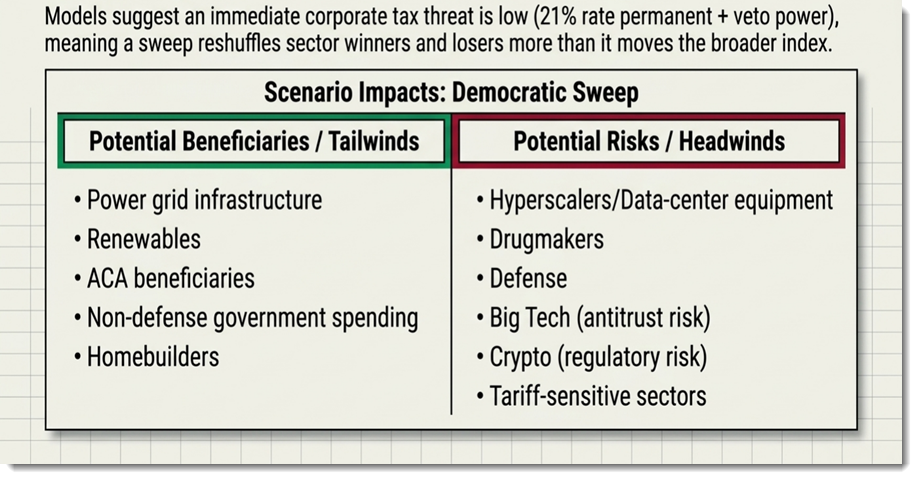
Blue wave and blue tsunami talk is everywhere; remember Brazil and wait for all the dice to roll before pre positioning for a Democratic sweep.
The September setup (long GDP sensitives, housing, bonds) to front run a sweep already worked; the October bond rally has made the trade much more coin flip like now.
The AI trade is such a large share of the market that political flow can dominate price action regardless of AI headlines.
Data centres are the sleeper political issue: Democrat opposition to manufacturing tax breaks traces to data centre backlash; many projects are being overrun and it has become bipartisanly unpopular remarkably fast.
Driver is the visible wealth divide: trillionaires, $20 to $25 cocktails, offensive New York rents; if you are not a winner in Menlo Park or Manhattan, why support what is creating this.
The Equal Weight Trade and Correlation (Minute 25)
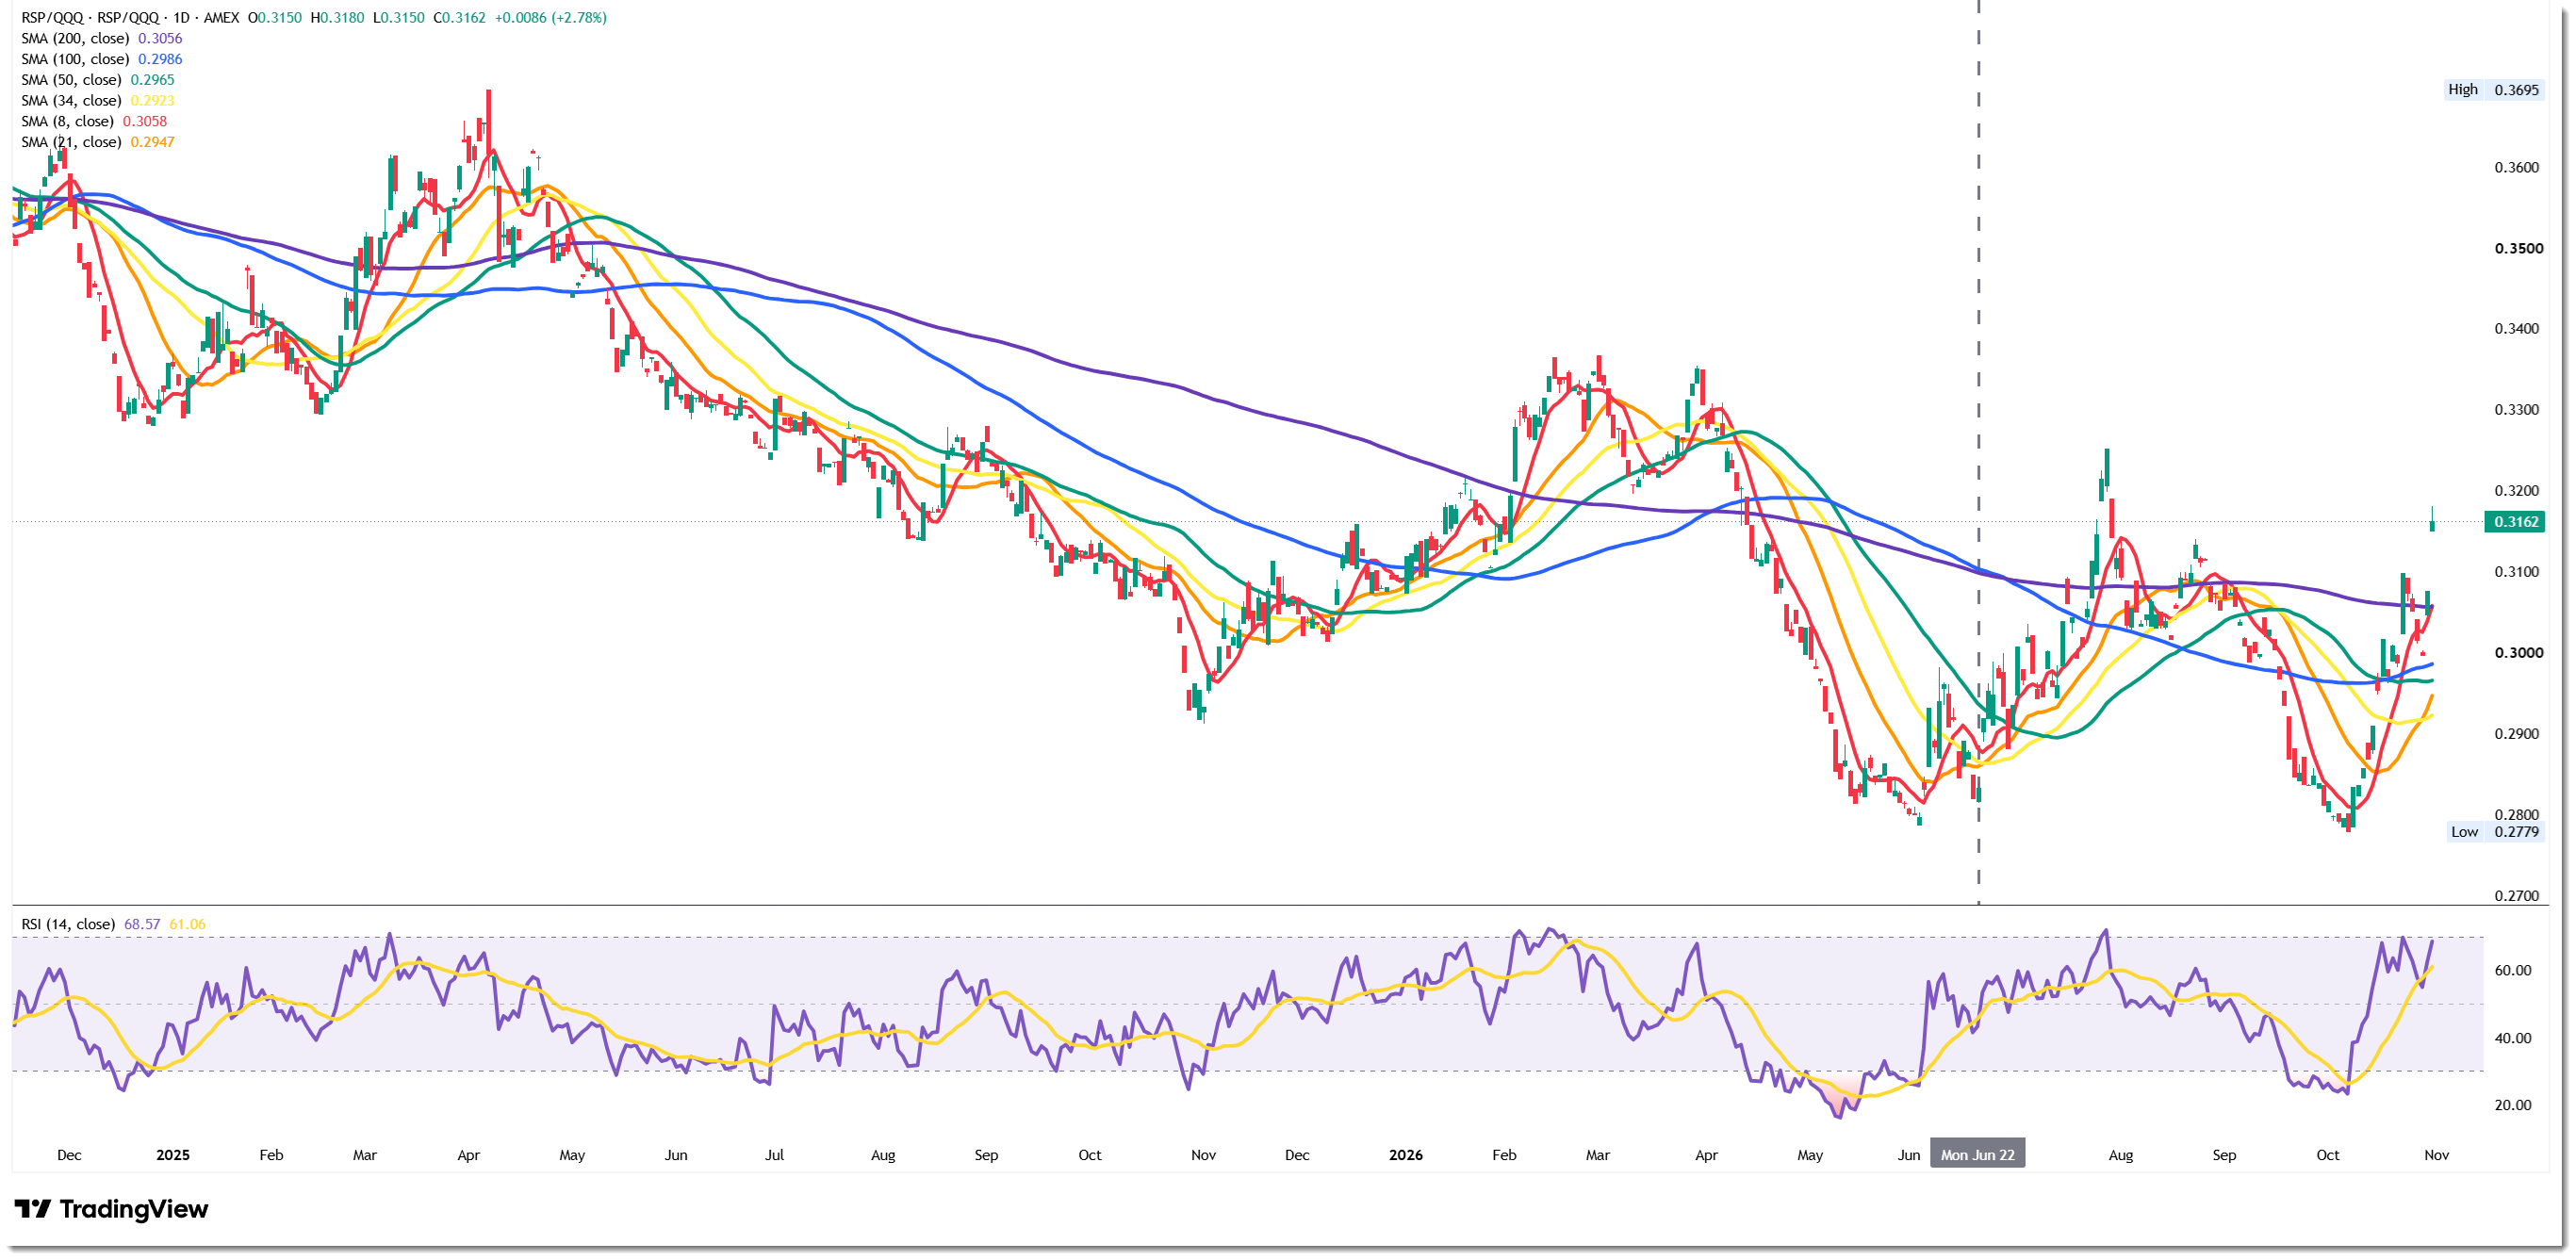
Anchor for the 🐿️’s BUSHY™ core beta book since early June: long equal weight S&P (RSP) versus the Nasdaq 100 (QQQ); ripped initially, pulled back hard in September, then almost made new highs and has held the book together.
One month implied correlation (black) and realized correlation (red) collapsing S&P High Beta / Low Vol mirrors RSP/QQQ; it is the same trade as pod shops grind correlation down.
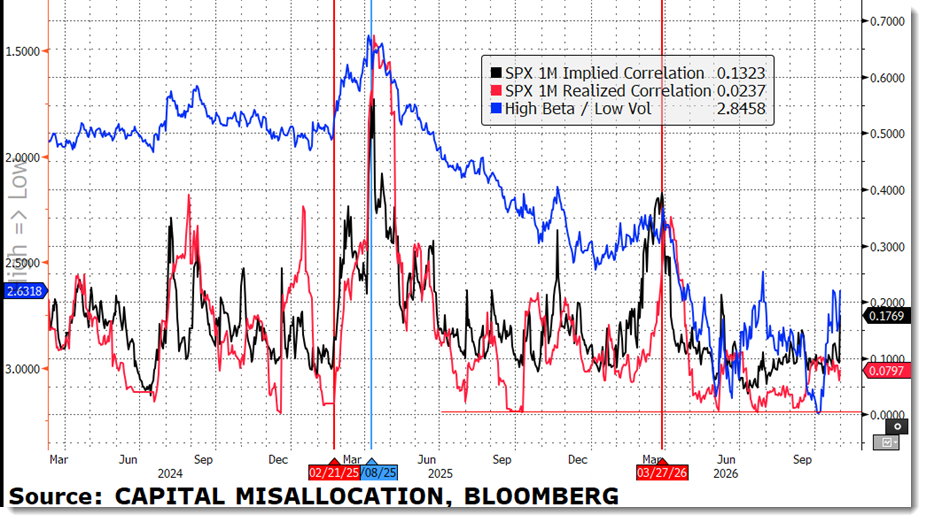
Mechanism: whatever works keeps getting bid, defensives and orphans get no bid, then reprice violently; since bonds bottomed around 8 October, high beta versus low vol repriced hard
Caveat: this is not a new bull market in mediocre mid curve businesses; many were simply funding shorts being unwound, driven by market mechanics.
If you act on anything provided in this newsletter, you agree to the terms in this disclaimer. Everything in this newsletter is for educational and entertainment purposes only and NOT investment advice. Nothing in this newsletter is an offer to sell or to buy any security. The author is not responsible for any financial loss you may incur by acting on any information provided in this newsletter. Before making any investment decisions, talk to a financial advisor.


