

In Episode 94: The free cash flow countdown on AI capex has hit zero, and the bond market is starting to say no. Benny joins from Milwaukee ahead of Brewers vs Dodgers NLCS Game 1, the Squirrel is back in Oxfordshire after a 15-hour drive through France, and the boys go around the houses: the pulled Firmus float on the ASX, hyperscaler CDS at junk levels, why 5% on the long end is anything but “agnostic”, two rate-sensitive stocks worth your attention, Brazil’s pension fund powder keg, and why France is the G7 debt story into April.
Show Notes
AI capex: the pulled IPO
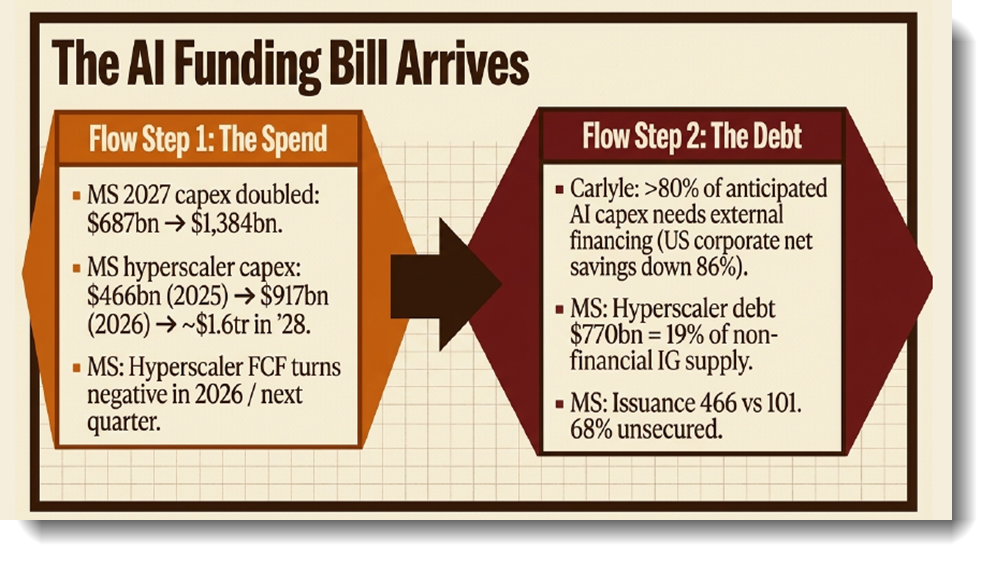
AI capex free cash flow countdown monitor now reads zero: the complex is no longer FCF positive as a group heading into earnings
Firmus, the Asia-Pacific CoreWeave CRWV 0.00%↑ lookalike, pulled its ASX listing at a mooted multi-billion valuation despite NVIDIA backing, after local long-onlys refused to wear it; a NASDAQ float is now the plan, where gamma squeezes and smoke and mirrors are possibly available
Hyperscaler CDS and rate transmission (Minute 5)
Hyperscaler 5-year CDS chart (black line is the 5-year UST as reference):
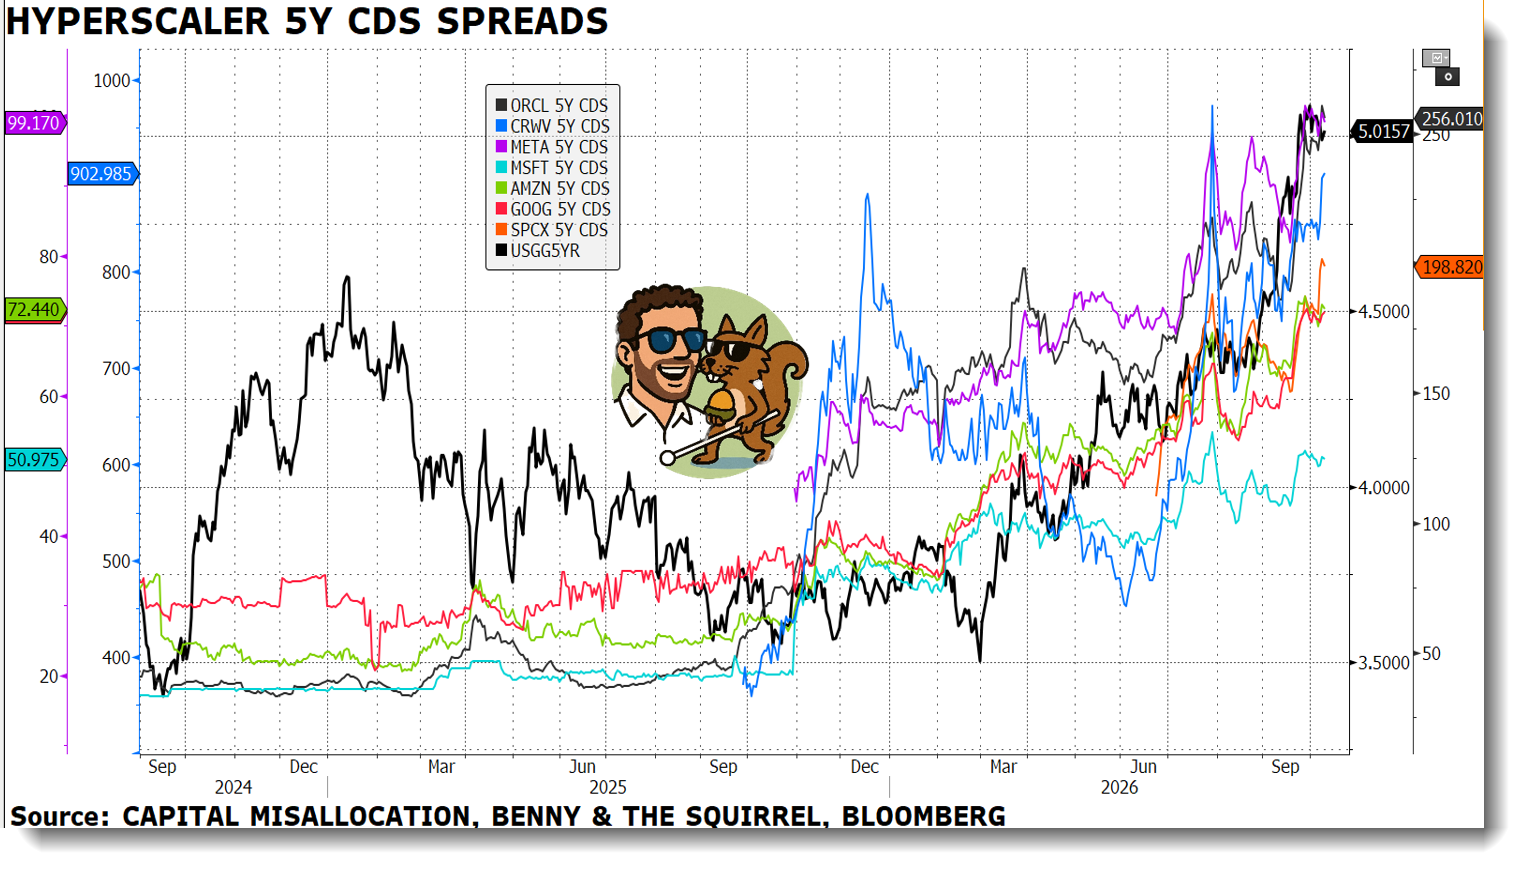
CoreWeave near all-time wides above +900bps, having been flagged on the show at 465-470 in late May/early June; Firmus-related paper near 200bp, which is BB/junk territory; Microsoft the only contained name
Most corporate debt and most non-US mortgages sit at five years and under; non-US mortgages are largely floating, hence the RBA’s near-instant transmission (Squirrel’s “most powerful central bank” line, qualified as best transmission mechanism)
ECB is chained to headline CPI, hence repeated policy errors (Trichet twice in the hall of fame); the Fed has far more discretion
Best of times, worst of times (Minute 9)
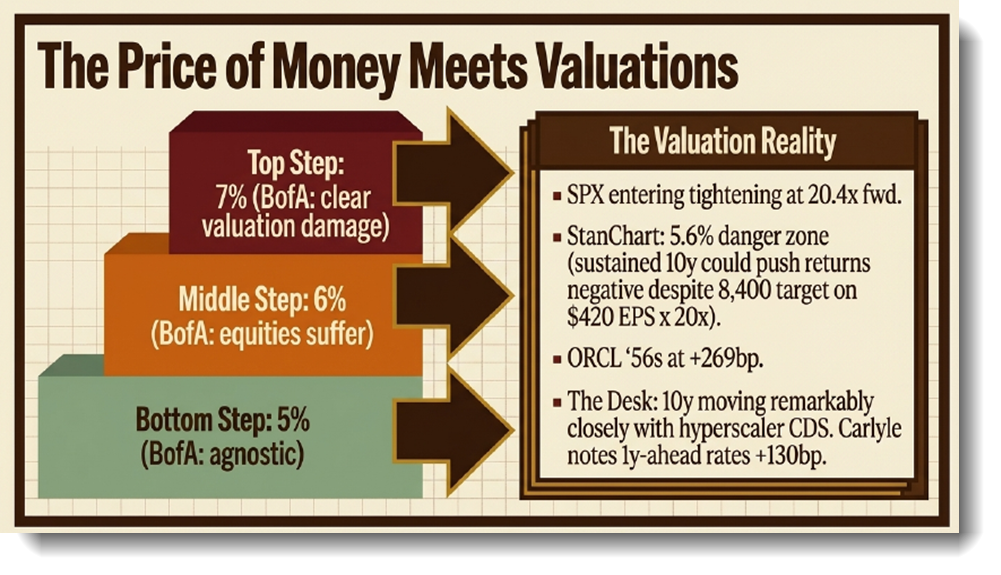
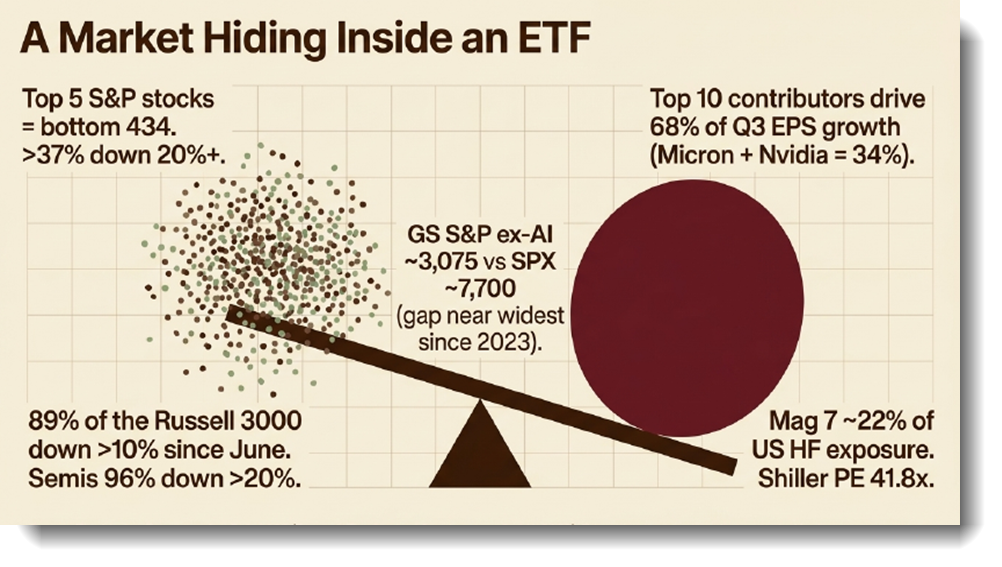
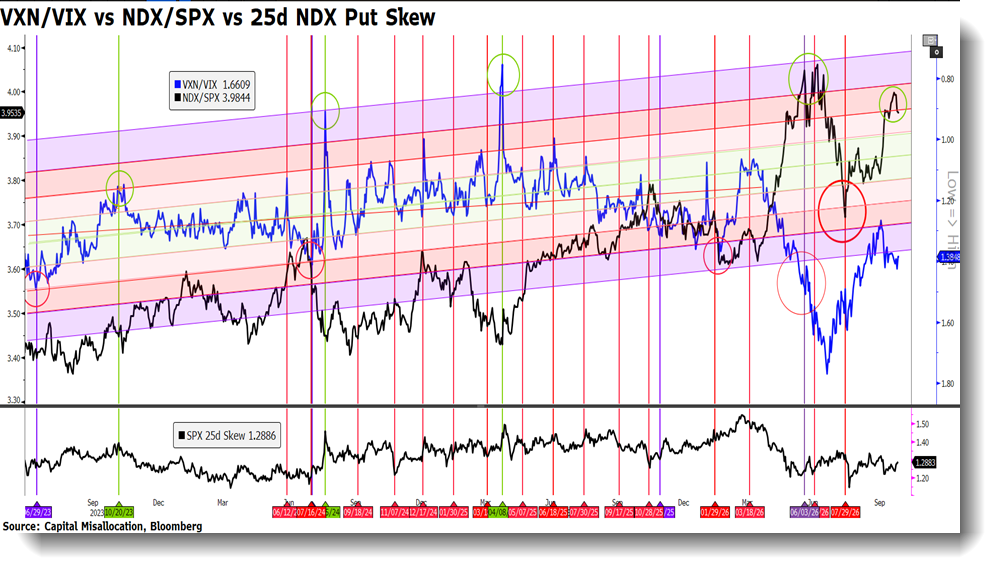
Bond investors and rate sensitives are hurting while AI capex and SPY/QQQ holders thrive; BofA framed 5% yields as agnostic for equities, but Hendry’s
Niederhoffer rule says 5% is too much
At some yield the average boomer rolls into the 10-year at 5% or TIPS at 3% real and coasts; high yields exist to attract capital (hunger games for capital), so always ask why the yield is being offered
The eight-name capex monitor (Microsoft, Meta, Google, Amazon, Oracle, Firmus, Nebius, CoreWeave) shows aggregate FCF at zero; the “funded from cash flow” cheerleader line no longer holds
Classic finance mistake: issuing paper when the narrative is best

AI valuations: infinity, zero, or negative (Minute 15)
Silicon Valley mindset: model labs are worth infinity or zero, and the average of the two is still infinity
Squirrel’s pushback: the downside may be negative, not zero (rogue agents hitting the grid, BP-scale liabilities, no liability framework or social contract for AI), so expected value must include a negative tail
Even the bull case is capped: Anthropic at half of global public market cap (roughly $120tn) is only a 30 bagger
Market structure: the causal barbell (Minute 21)
NASDAQ/S&P ratio has reflated after the Q2 leverage washout that smoked the high-beta AI trade; still below the prior line, so plenty of pent-up energy
Benny’s “causal barbell” essay lands this week: pod shops on one side (short vol, correlation zero), free unlevered beta on the other, with the active middle hollowed out
A cozy equilibrium that works until it doesn’t; owning CDS insurance has bled premium (CoreWeave the exception) while vol sellers get rich
Single stocks: Home Depot and Rocket (Minute 24)
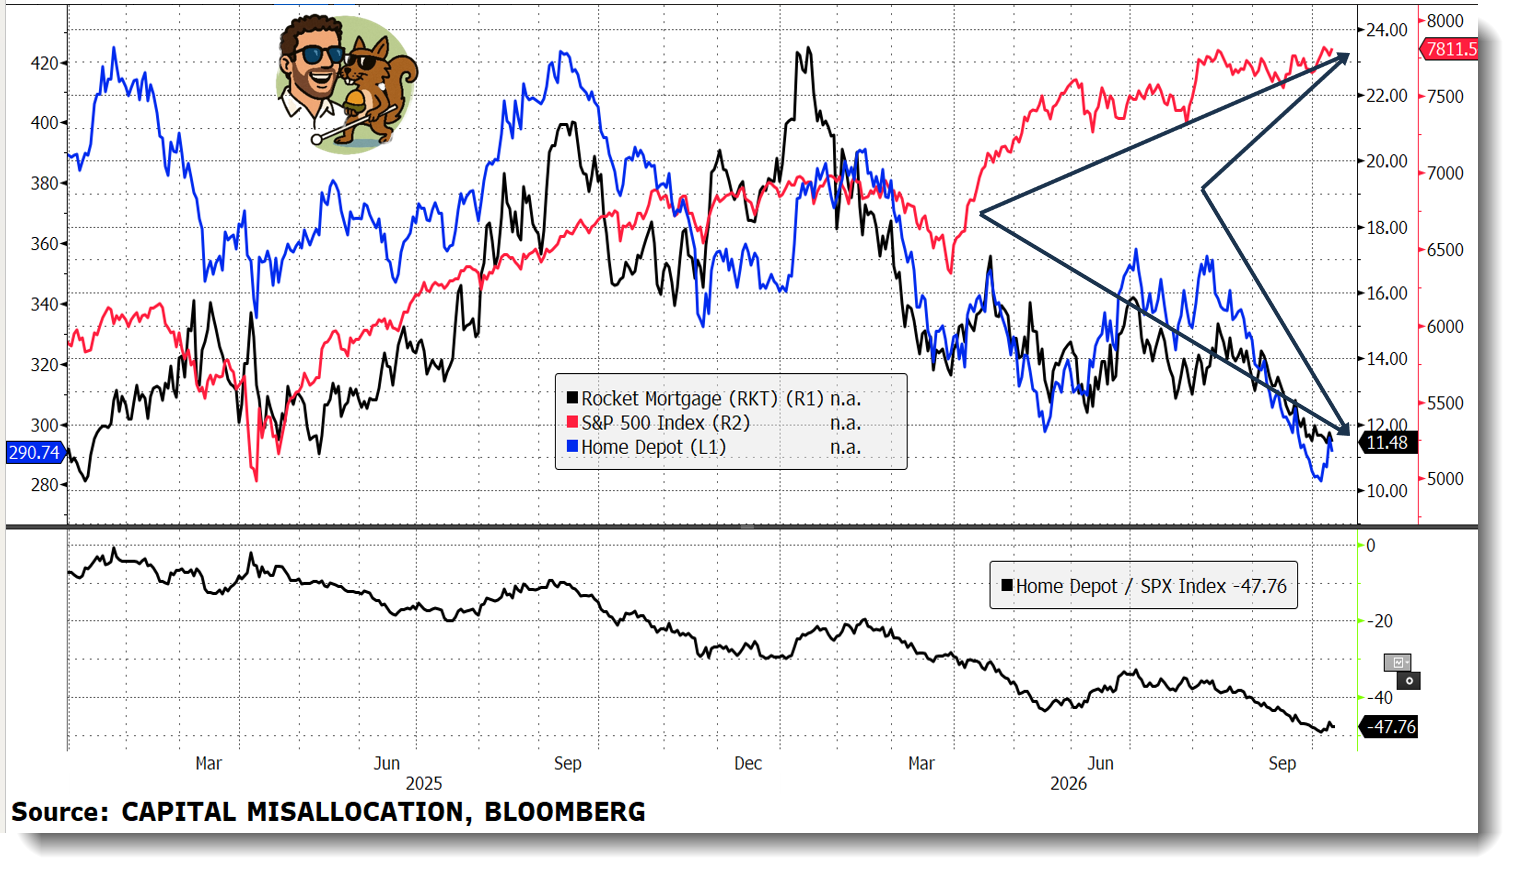
Home Depot: world-class operator, ROIC down from 38% in 2022 to sub-20; roughly $14 EPS this year versus $16-17 in 2022; at about $280 the stock is 20x troughish earnings, with a wipeout to 14-15x implying $200-220; a 3.3% dividend yield cushions versus Treasuries
Rocket Mortgage: an $11-12 stock with potential $2 of earnings; the Mr. Cooper deal (done at $22 last October) made it the second-biggest servicer, and the rate-driven selloff bought a free year for integration plus better AI tooling; a defined-use-case token consumer
For equity managers who cannot trade macro products, Rocket is the equity version of a SOFR trade; Benny frames it as a trade, not a position
EM: Brazil over Korea (Minute 29)
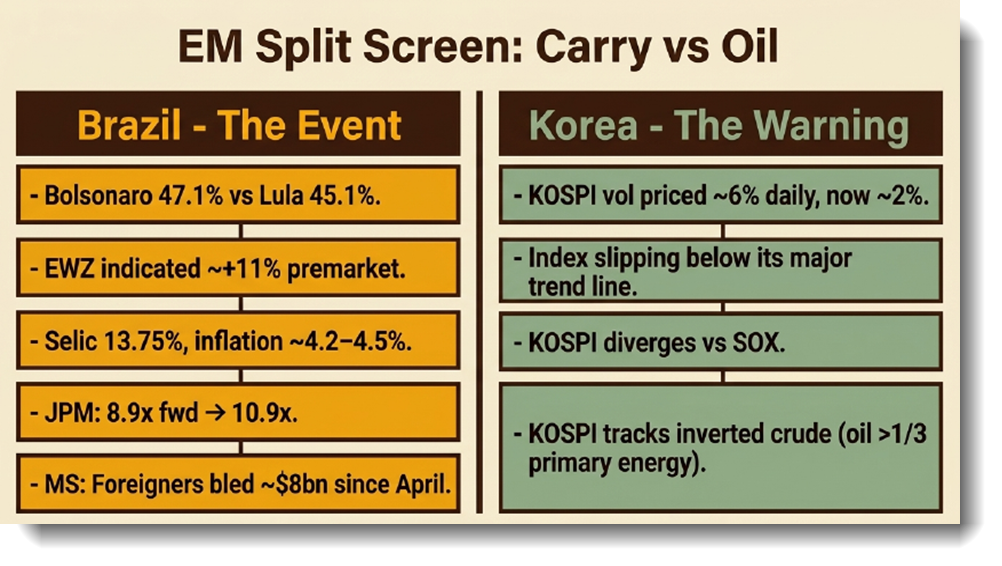
Brazil ripped on Flavio Bolsonaro’s unexpectedly strong first round; the 25 October runoff is seen by Brazil-watchers as a formality
Korea has been the EM bull market on memory and DRAM; Squirrel sat it out (PTSD) but notes it remains cheap, prints surpluses, and the currency looks too weak
Since the June memory-mania peak: EWZ up 29% versus EWY down 13%, a roughly 40-point pair trade in 3-4 months, with correlation near zero
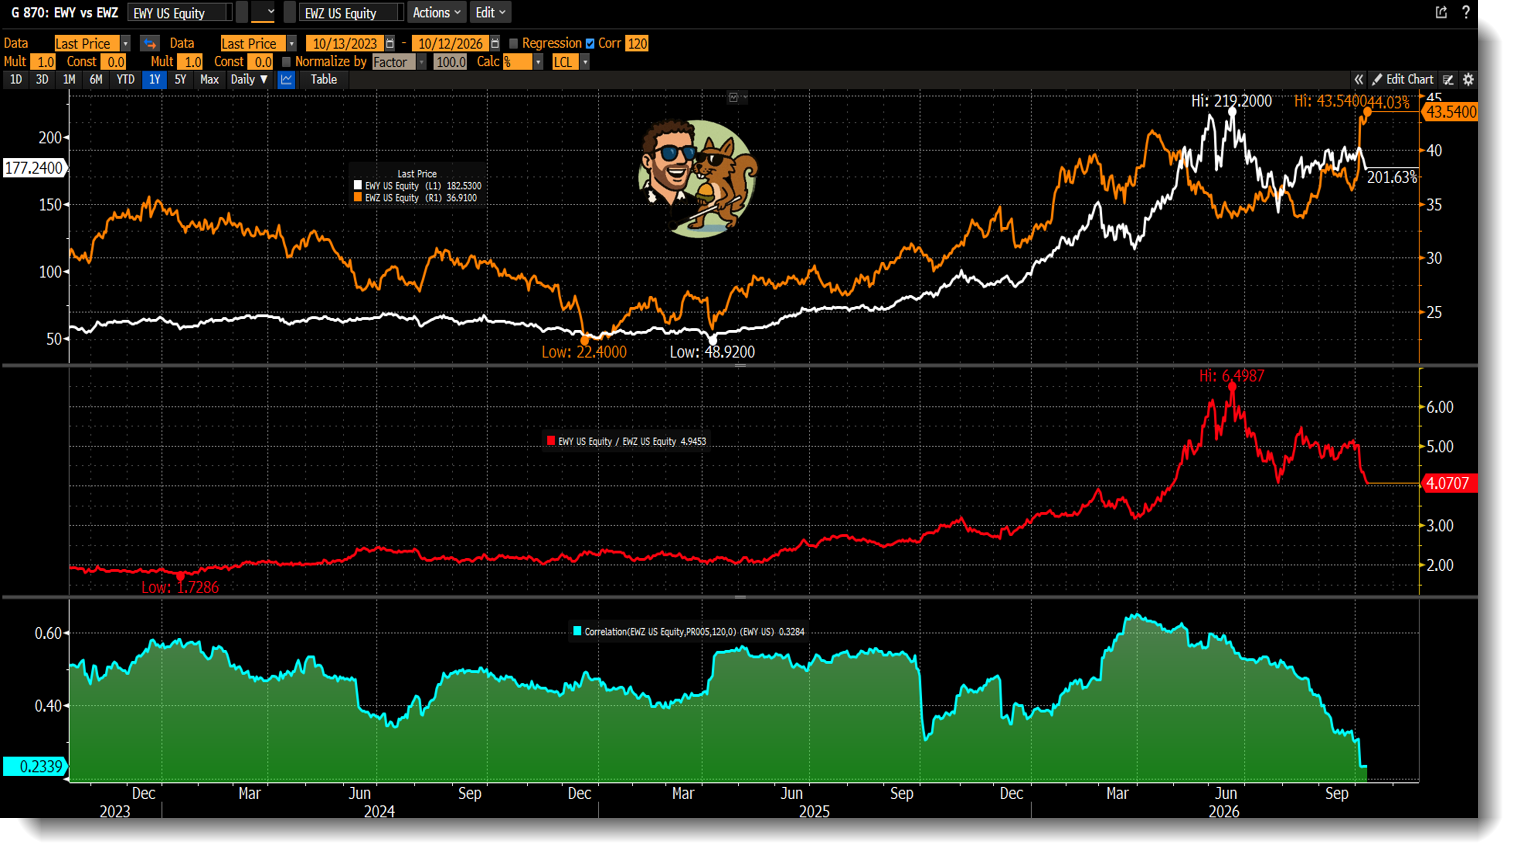
Brazil thesis: a bet on the Bloomberg Commodity Index plus 8-9% real rates pulling in global money
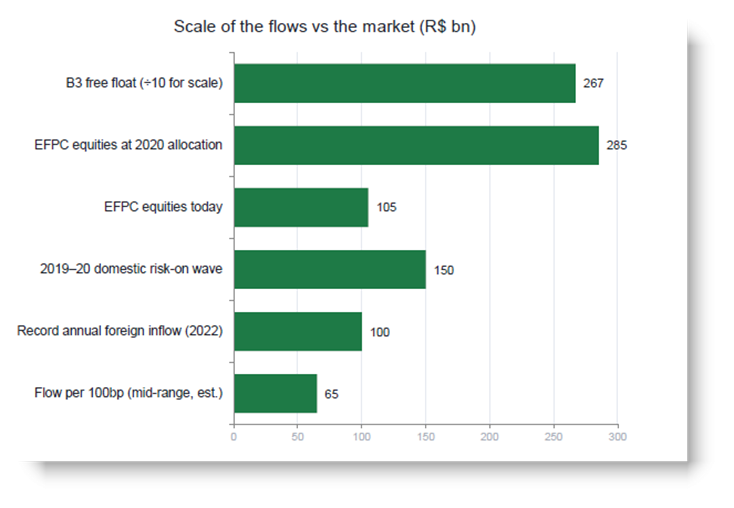
The belly of the curve is the real story: local pension funds hold de minimis equity allocations because real rates meet their actuarial bogey; even a modest erosion of fiscal dominance under Bolsonaro sends them into a very tight free float where there is not enough stock
Squirrel’s “wait for the runoff” call was overtaken by the strength of round one (last week’s EWZ and BRF moves); the 12-18 month view is pension flows driving equities
Capacity constraints and the bond rotation (Minute 33)
Capacity cuts both ways: shorting is capacity-constrained with pod shops dominant, and on the long side holders lift offers, so price is whatever clears the system (uranium miners, Brazil)
Open question: when does money actually rotate out of stocks and into bonds?
Benny holds bonds only as a hedge: parts of his book he does not control are short bonds, and discretionary shorts in utilities plus long oil need protection; not yet a true believer, and duration is off the table
France: the G7 debt epicenter (Minute 36)
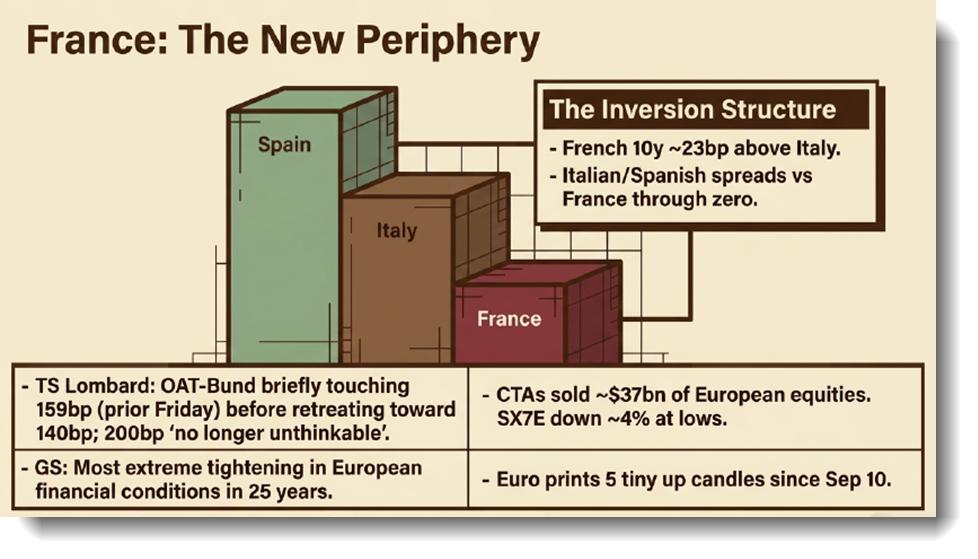
Squirrel’s drive through France felt incredibly normal, yet bond markets are waking up to an emerging political crisis
The old pattern (Le Pen scares the market, centrists rally and box her out) may be breaking: the horseshoe is in full effect and an April runoff of Le Pen versus Mélenchon looks increasingly likely
Marine Le Pen is not her father’s daughter: she expelled him, talks debt brakes, and is tacking to the center on the Meloni template
Our view: give populists the ball! After 30 years as the ghost opposition, the dog that caught the car should get to drive; if it fails, the left gets to say it told you so
If you act on anything provided in this newsletter, you agree to the terms in this disclaimer. Everything in this newsletter is for educational and entertainment purposes only and NOT investment advice. Nothing in this newsletter is an offer to sell or to buy any security. The author is not responsible for any financial loss you may incur by acting on any information provided in this newsletter. Before making any investment decisions, talk to a financial advisor.


