

For Episode 88, a jet lagged Squirrel joins Benny from London to unpack a hawkish Warsh rate hike, stocks and bonds selling off together, the MOVE index ripping, and why nobody cares that the SPRs are empty.
Plus: BofA's 33% earnings growth met with total silence, the AI credit recycling machine keeping index spreads pinned, the dispersion trade propping up a lifeless VIX while single stocks get murdered, and why energy at 3% of the S&P today could be 8 to 12% within five years.
Show Notes

The Fed Week Gauntlet
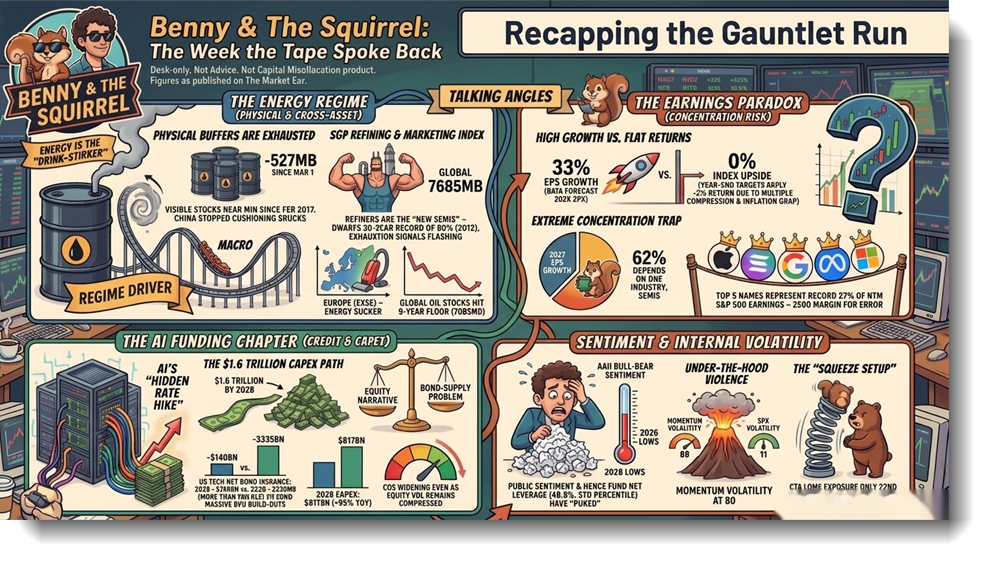
Warsh hikes and the Fed comes out surprisingly hawkish. Squirrel bought front-end bonds (levered 2-year note exposure via TUA 0.00%↑ ) before the meeting but could not bring himself to add after, leaving him in limbo on rates.
Market reaction: stocks and bonds both sold off post-presser, around a 15bp reversal from the pre-meeting move, followed by a 5 to 8bp rally on Thursday. MOVE index ripping higher.
The energy spike helped set off the rate volatility, echoing the March war-driven bar event.
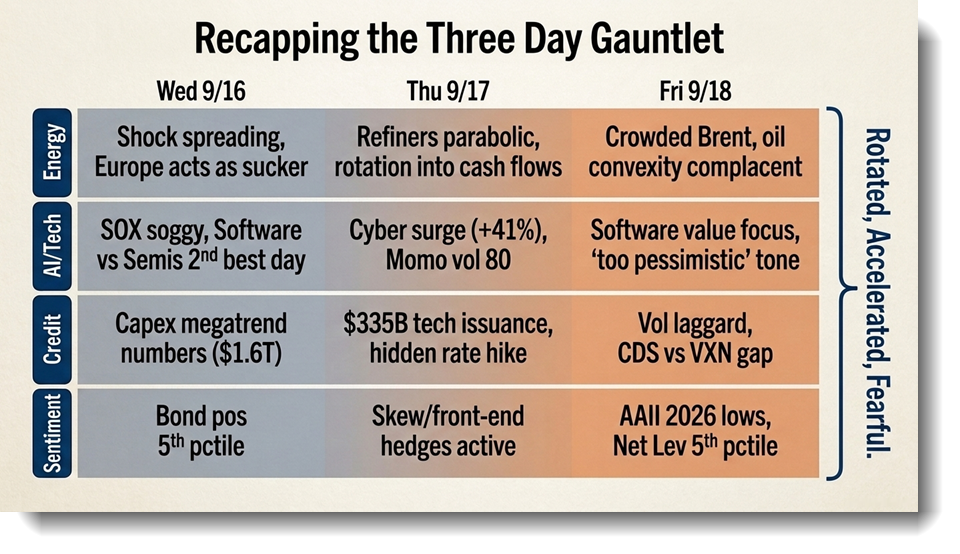
Earnings, Energy and Positioning (Minute 3)
Bank of America posts 33% earnings growth and the stock is flat: can earnings growth ever match prices at these levels?
Bond sentiment at rock bottom; the AI capex mega trend keeps driving earnings, and index credit spreads stay subdued despite chaos under the surface.
🐿️ has trimmed a large crude position that was hedging his long risk assets, but is not ready to add risk back. He describes himself as in no man’s land.
US Buffett indicator at 244% of GDP, way off trend. Professionals have to be involved, but retail viewers do not.
The Case for Bonds (Minute 8)
For anyone not benchmarked: sit in bills or buy bonds. No credit risk, capital back, plus an embedded call option if the market rolls over.
Bonds are in “most hated” status: BofA high net worth allocation to bonds at a multi-year low, comparable to energy in 2020 or tech in 2022. Consensus assumes AI issuers and governments will issue bonds forever.
Undersupply of duration at the long end as issuers refuse to lock in 5% coupons; payer swaptions are expensively priced, showing the market is positioned one way.
Wall Street has made a habit of getting forecasts wrong, which supports the bond call option logic.
Priced-In Earnings and Distortions (Minute 12)
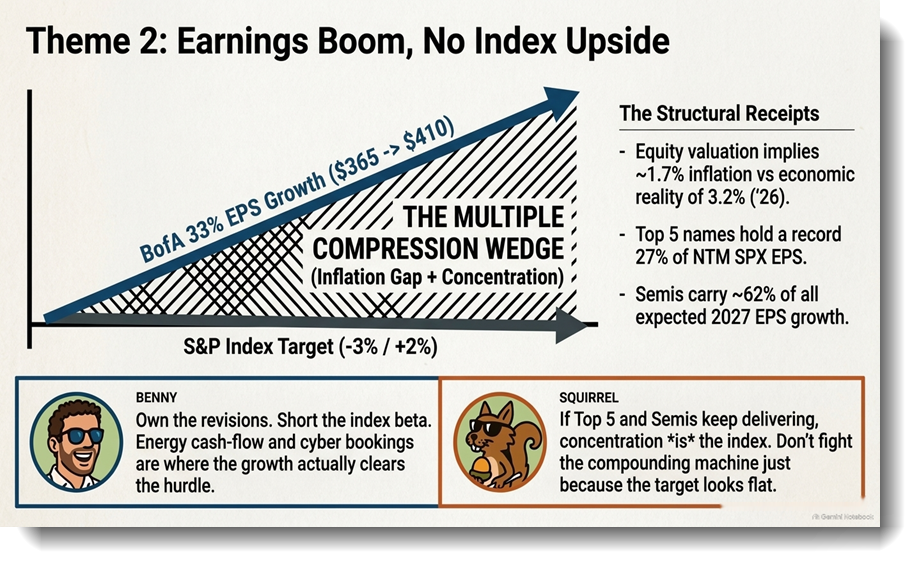
Valuation is not a momentum signal, and at this stage individual earnings prints are almost unhelpful to process.
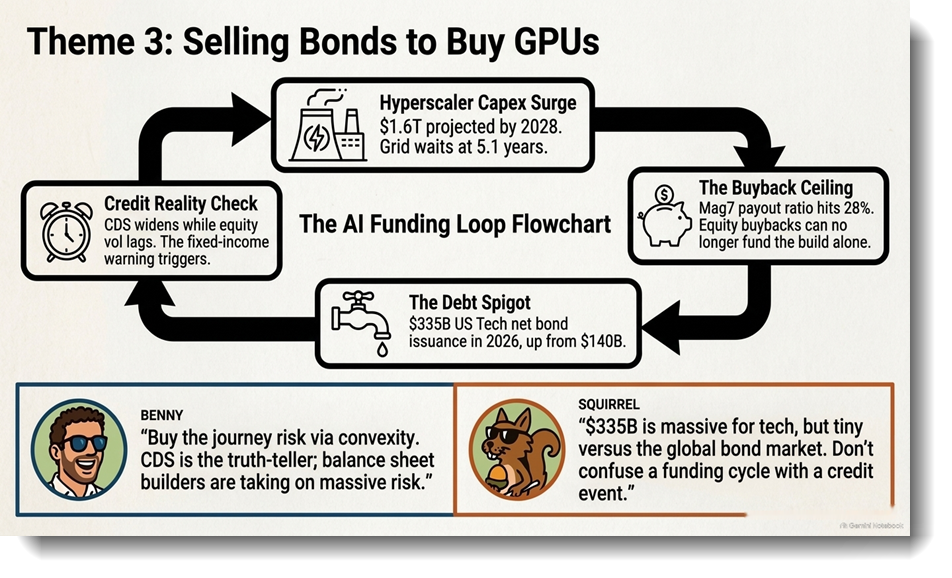
AI credit mechanics: hyperscaler credit spreads are blowing out while index spreads stay pinned. Passive inflows hit sector constraints, so money gets recycled into weaker names (Boaz Weinstein publicly complaining about Stellantis spreads versus its terrible credit metrics), and banks hedge for BIS regulatory reasons.
The shift from active to passive: unlevered beta went from roughly 1% fees twenty years ago to nearly free, removing the human “speed bumps” that used to absorb risk in the system.
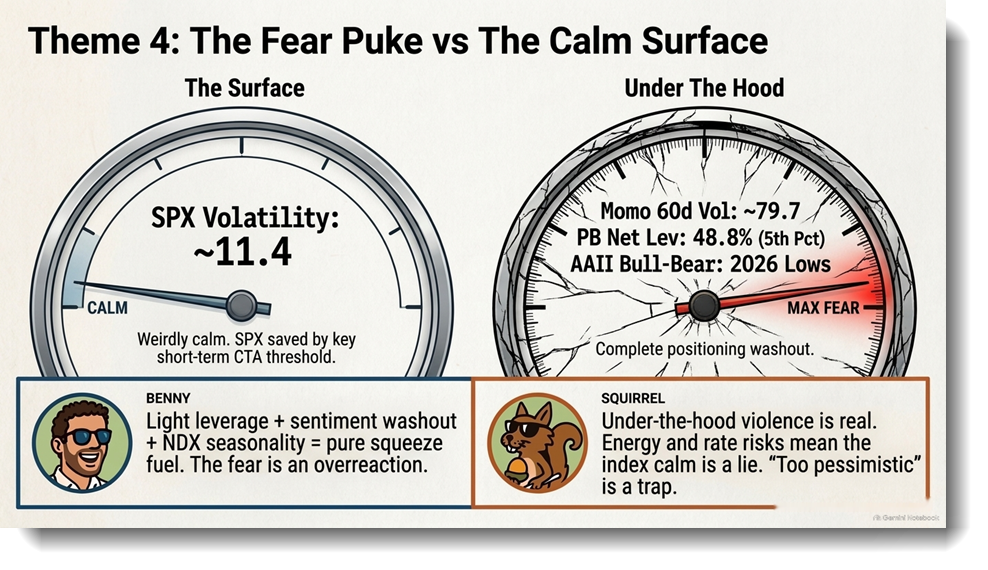
Dispersion and the hollowed-out middle: pod shops and near-free passive dominate, single-stock and cross-sector volatility at 10-year highs while the index sits in the low teens, and implied correlation stays floored by the dispersion trade.
Pod shops and private equity sell smooth return streams that pensions need, but the old mental and market models no longer match a grossly distorted market reality.
If you act on anything provided in this newsletter, you agree to the terms in this disclaimer. Everything in this newsletter is for educational and entertainment purposes only and NOT investment advice. Nothing in this newsletter is an offer to sell or to buy any security. The author is not responsible for any financial loss you may incur by acting on any information provided in this newsletter. Before making any investment decisions, talk to a financial advisor.


