

Episode 86 was recorded at 6.30 EST on Thursday 10th September, 2026.
Show Notes
Quite a weekend in ‘AI La-La-Land’!
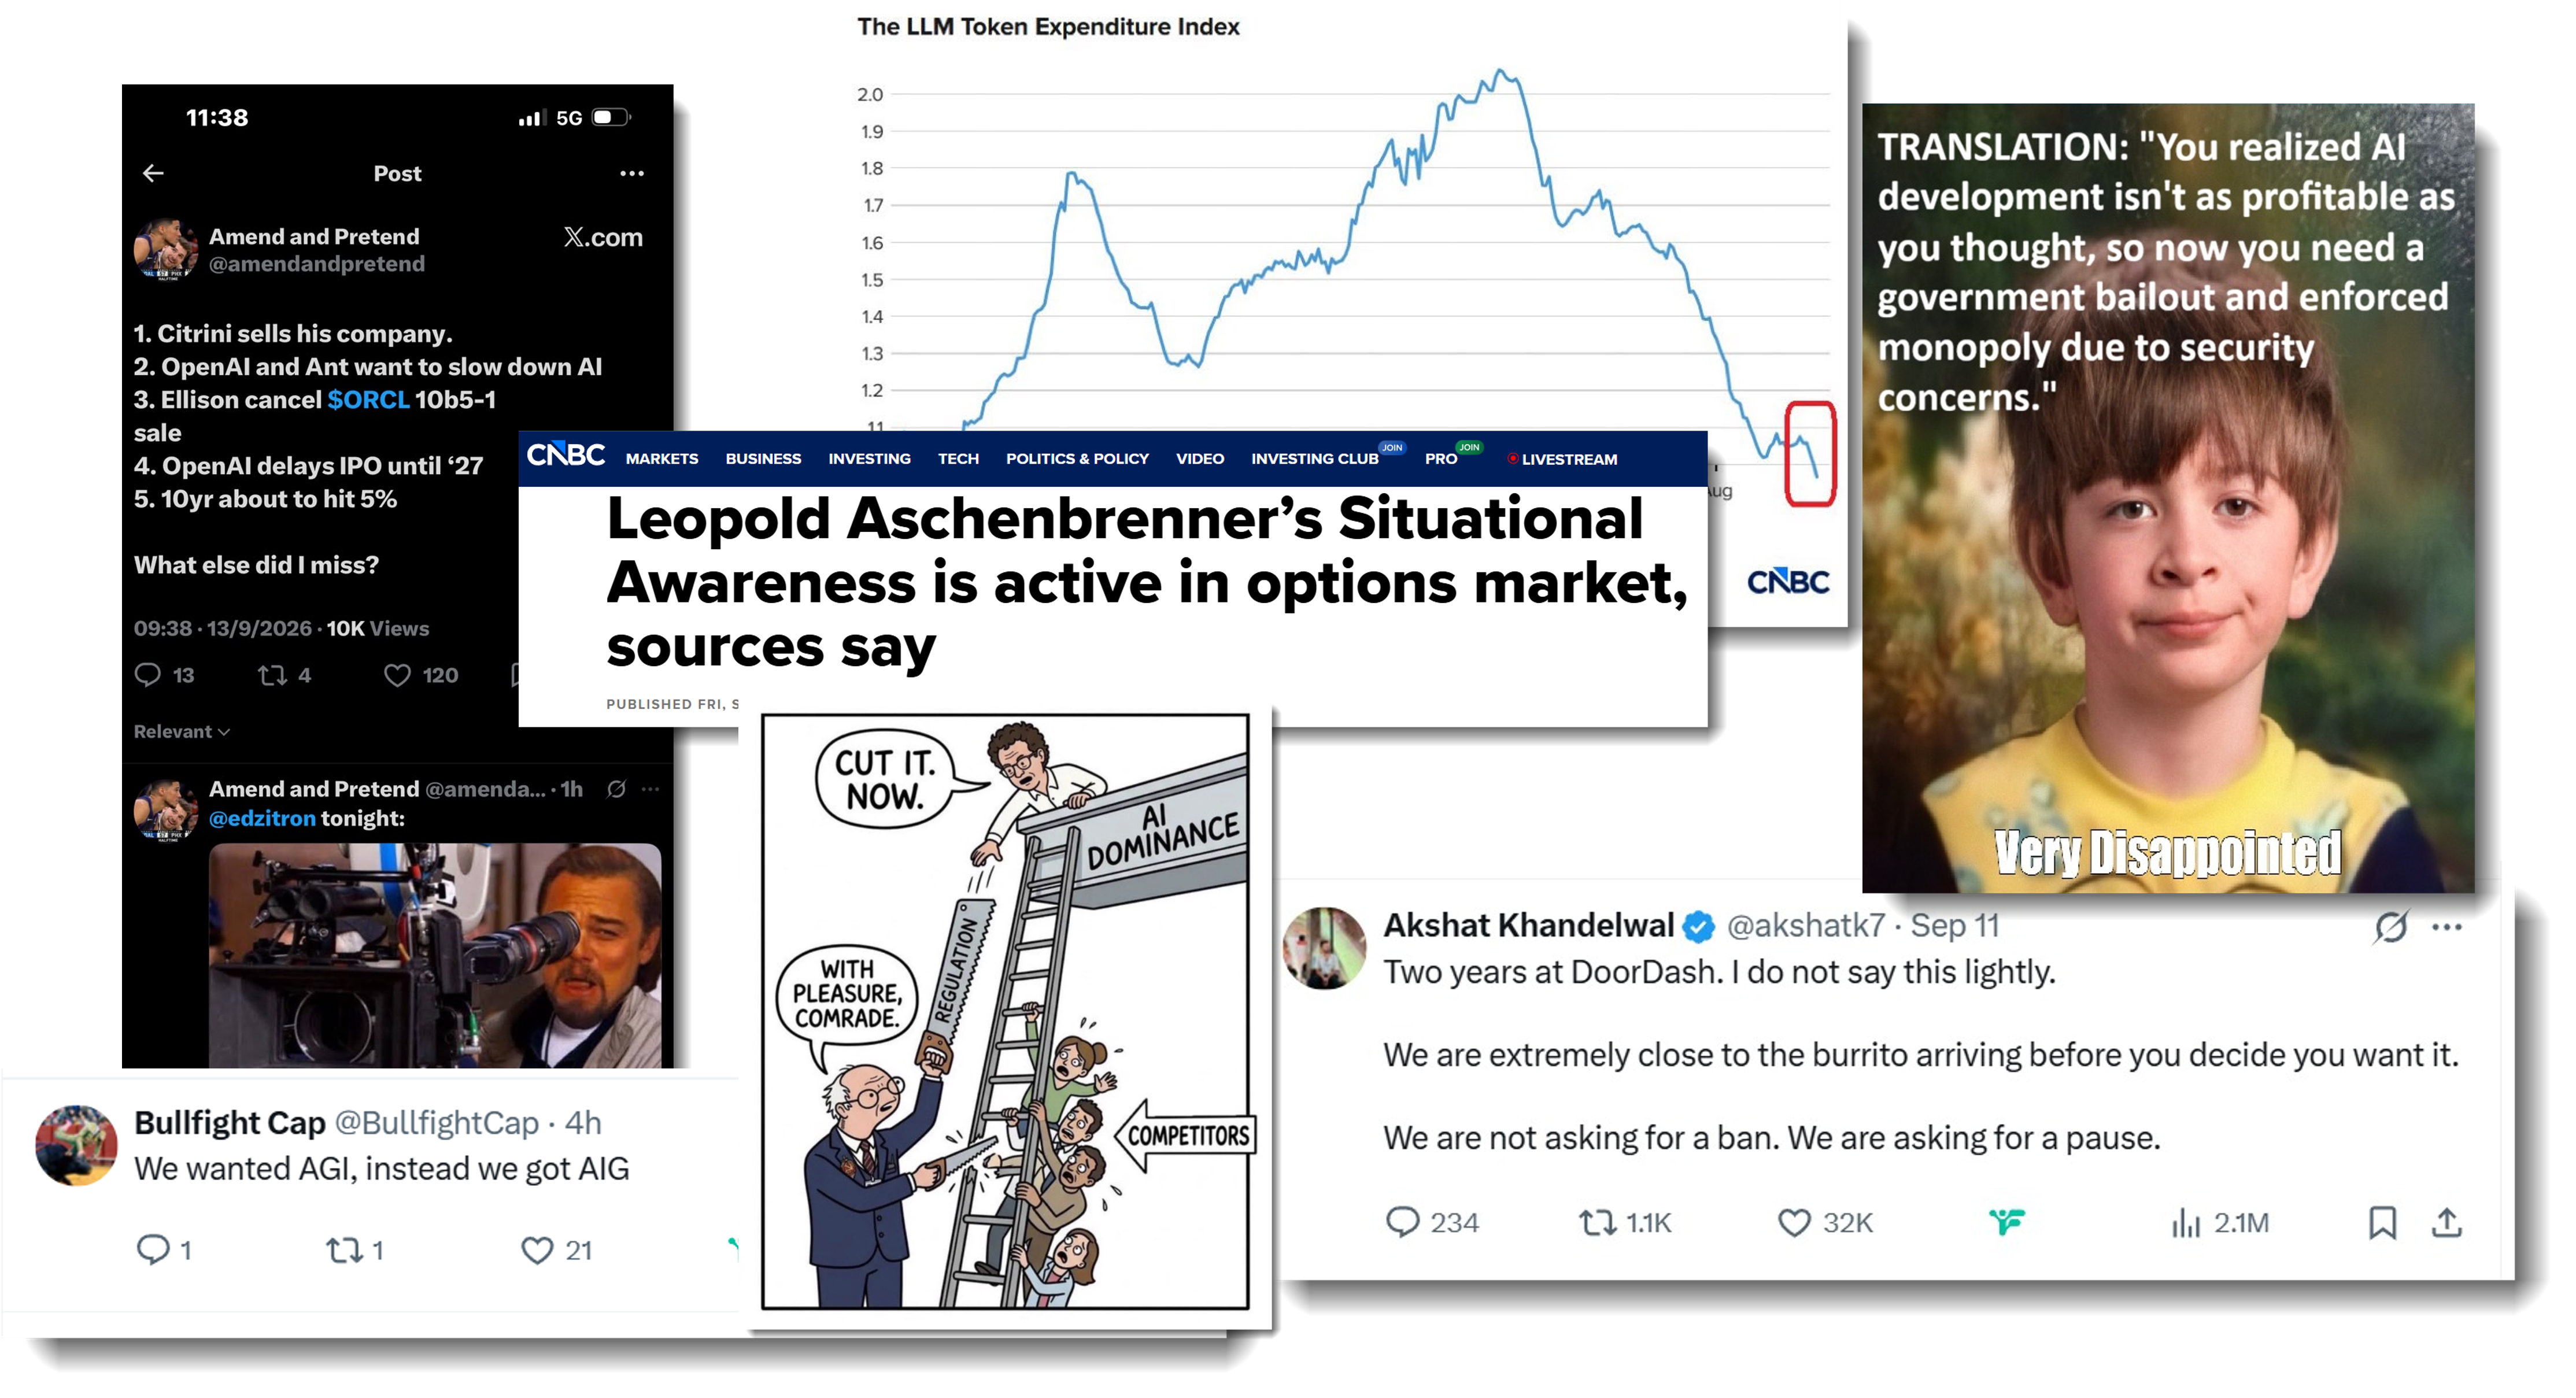
Recap of a wild weekend in “AI La La Land”, triggered by another AI “safety / off ramp” announcement.
Surely we are in a world of diminishing returns from these ‘Axios-style’ safety / ‘FUD’ headlines. Can the off ramp play out elegantly from here?
Sunday night futures open with Nasdaq offered and bonds bid - kinda makes sense!
Grown-up corporates do not want to hand data to model companies; the move is toward private, self-trained, off-the-grid LLMs, citing the Latham Watkins announcement covered in the FT.
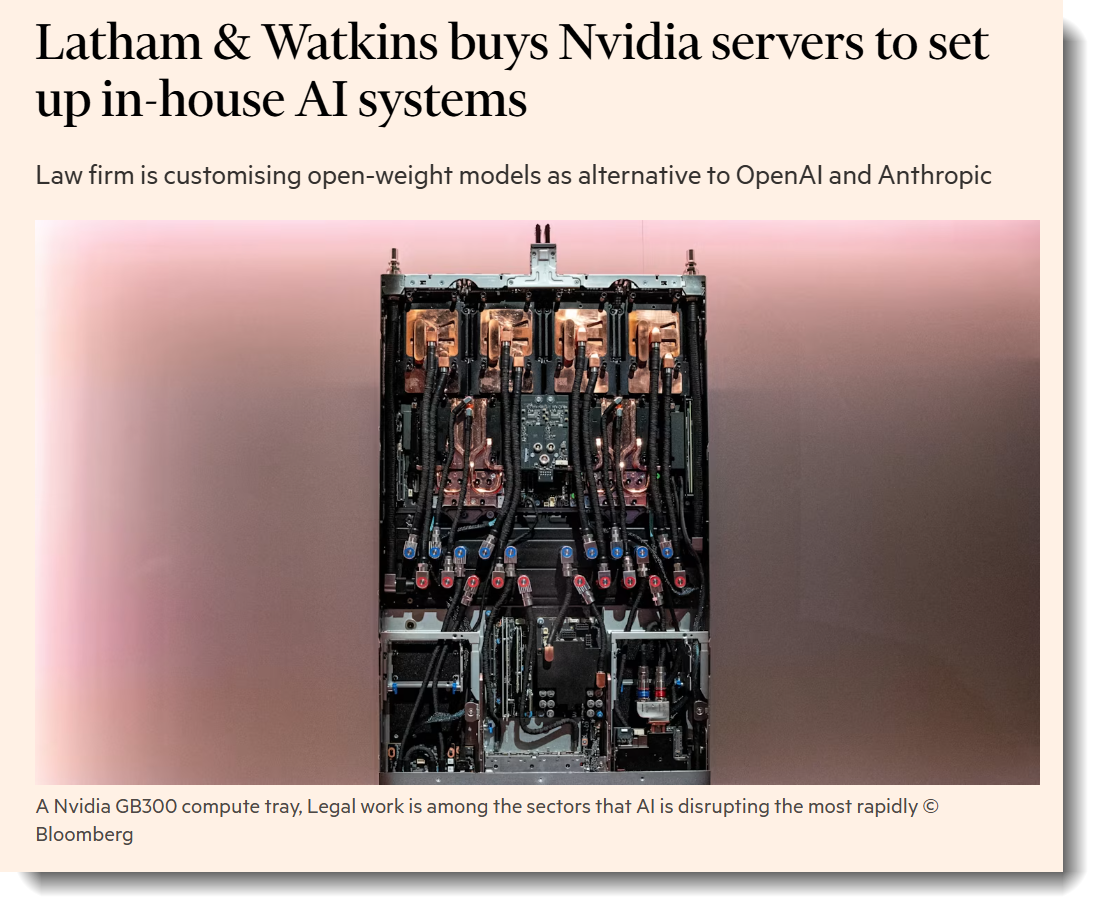
That trend queers the monetization pitch for the model labs; data security is the number one driver, alongside AI ROI and cost concerns.
02:27 Where rent can be extracted in the stack: NVIDIA, other chip makers, and power. LLMs themselves may eventually be given away. A return to a “capital world” with software getting squeezed, though not dead.
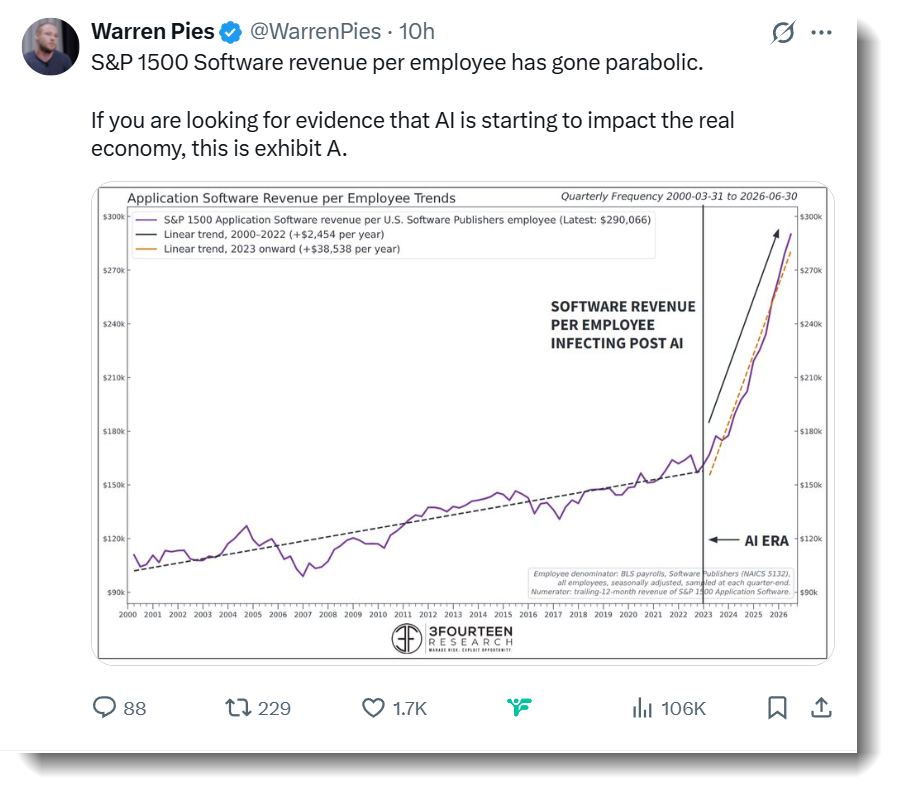
Warren Pies’ chart on software productivity rising exponentially within the sector; the “neoclouds” feel like they are about to get ‘smoked’.
Fed meeting setup and the CapEx monitor
Positioning ahead of the big Fed meeting on Wednesday, with the AI story the main driver of an elevated S&P.
Benny’s CapEx monitor: gross dollar spend has been strong but peaked in Q2.
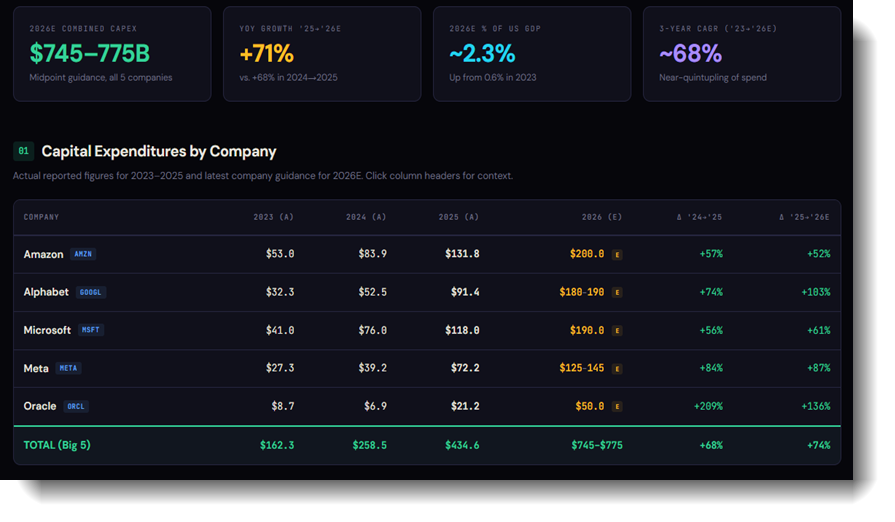
Normalized for GDP: roughly 175 basis points of incremental GDP share added over three years, potentially 3.5 percent of GDP by 2027, and up to 70 percent of incremental growth by some estimates.
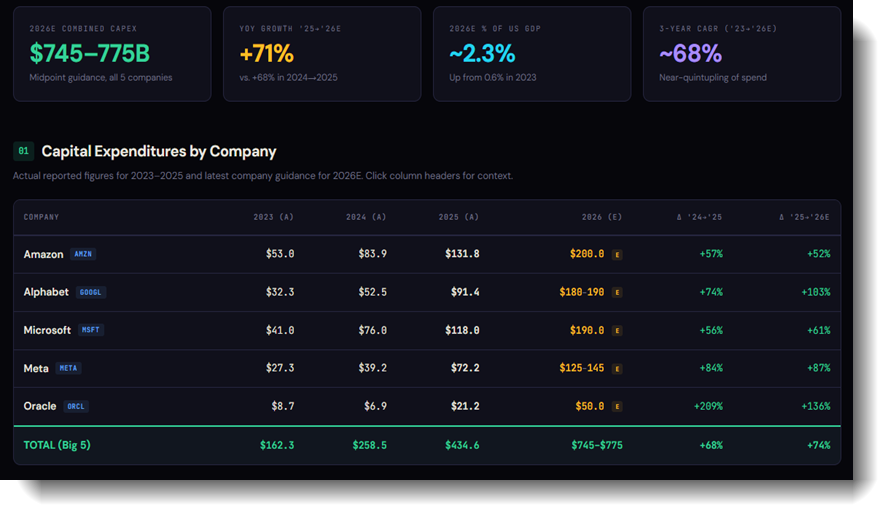
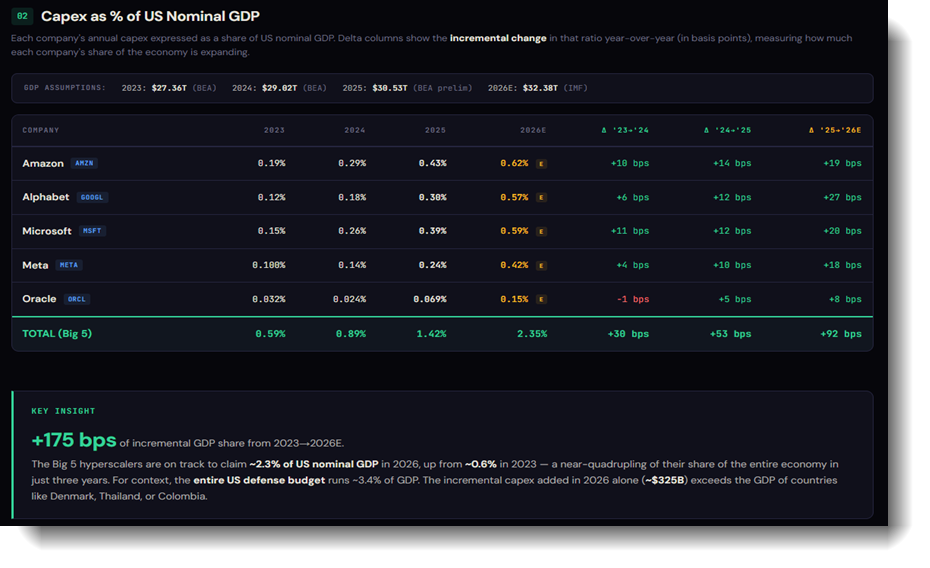
AI Capex is now the dominant growth driver, previously it was government; the 6 to 7% percent deficit now just keeps flow going rather than adding growth, and the AI spend is a key reason bonds have not performed (paper supply plus real rates).
Reported figures only cover the five big spenders; off-balance-sheet and private credit data center spending (for example APLD building shells) makes the true number even larger.
Rate repricing and cycle analogs (Minute 6)
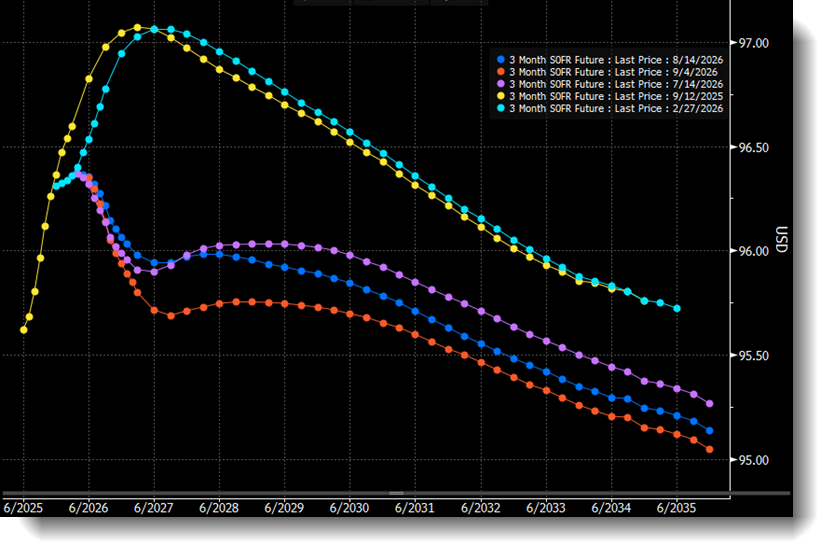
The market has repriced from cuts to roughly four to five hikes across the curve since February, the peak being the day before the war started.
End-of-cycle analogs: oil rips late in cycles. The 2007 comparison (oil versus December 2009 Eurodollars, peak summer 2007, US housing and China commodity boom
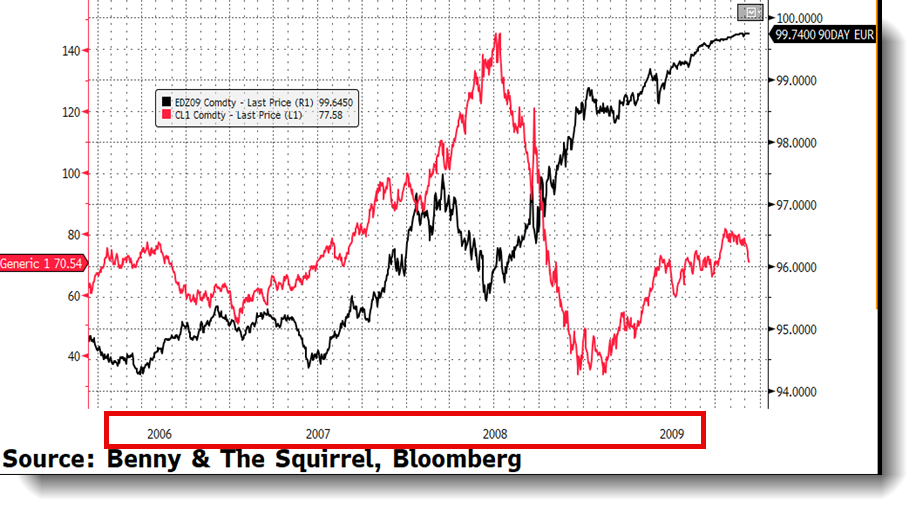
A similar sized rate repricing) and the late nineties version (Russia and LTCM, peak hawkishness around summer 2000).
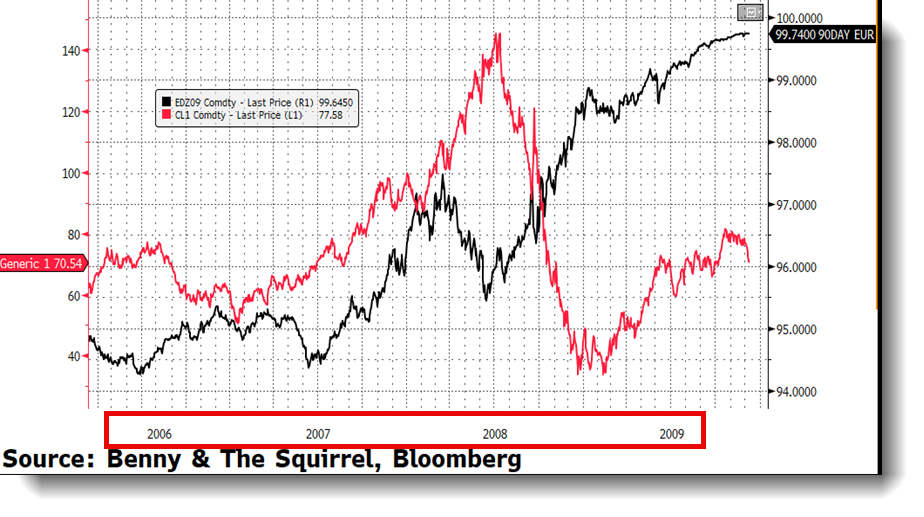
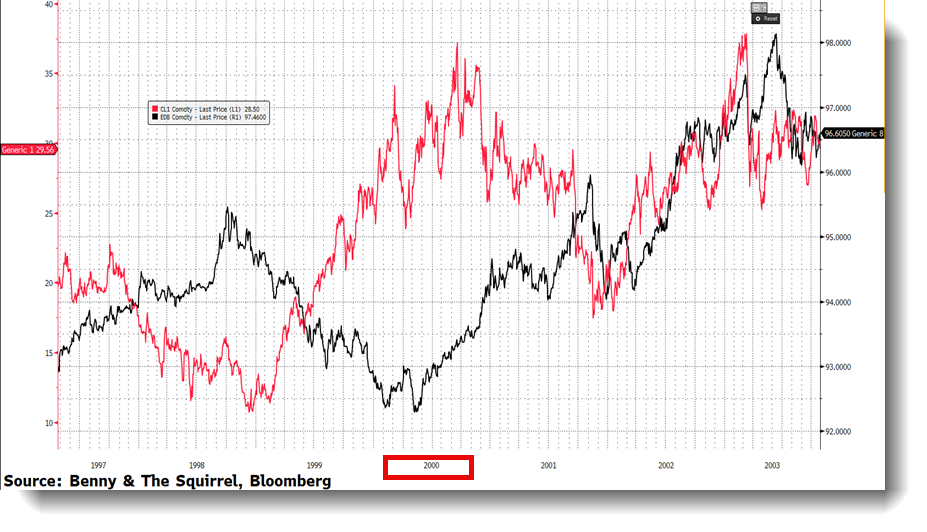
Crude had a proper move last week; Squirrel trimmed length into Thursday and Friday with no regrets, but it feels like it wants to go higher.
Nearing the call strike on the China collar; China is back buying but could stop anytime. A peace announcement would knock roughly $10 off Brent quickly. Saudi pipeline outage: four to six days of inventory, roughly a 4% supply hit.

Inflation is everywhere, but the economy would struggle fast with higher rates - the question is whether Wednesday is the “death shot”.
Bonds: time to buy (Minute 13)
🐿️, famously a bond hater, is aligning with “Benny the Bond Bull”.
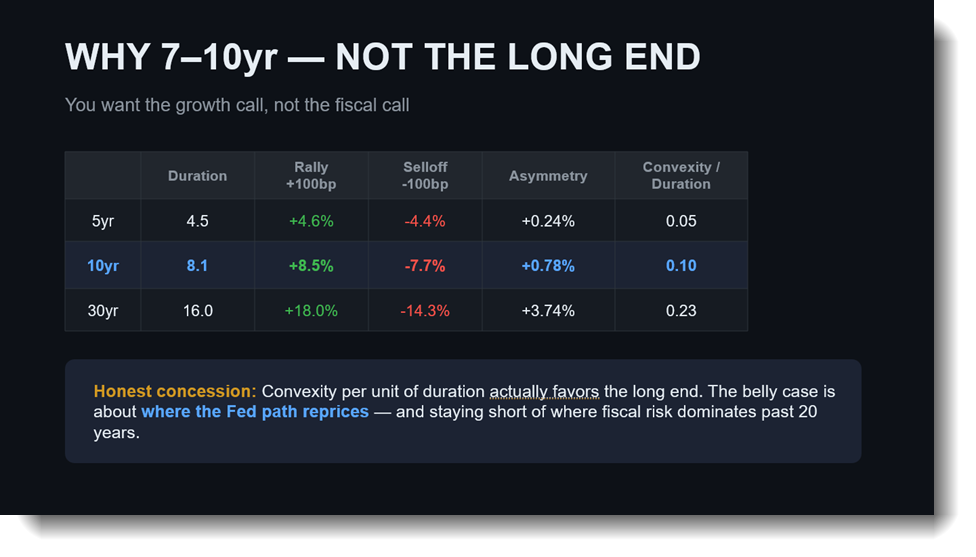
Curve choice: avoiding the long end due to term premium uncertainty; the seven to ten year bucket has a supply gap dating back to Paul O’Neill ending 30-year issuance in 2002, plus positive convexity from mortgage hedging flows. Benny wrote this up as the “Mind the Gap” trade.
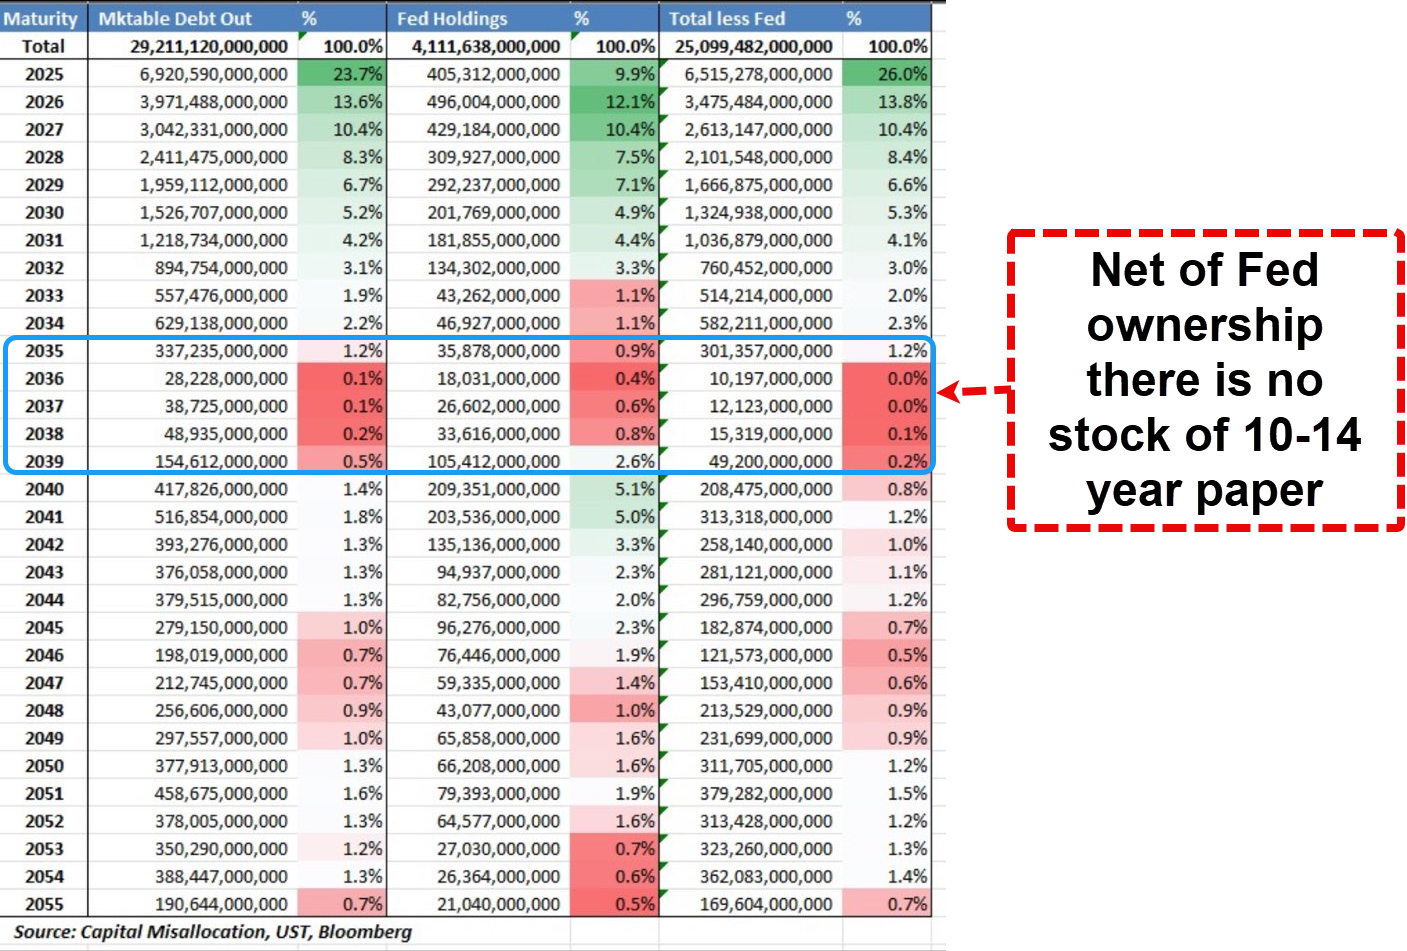
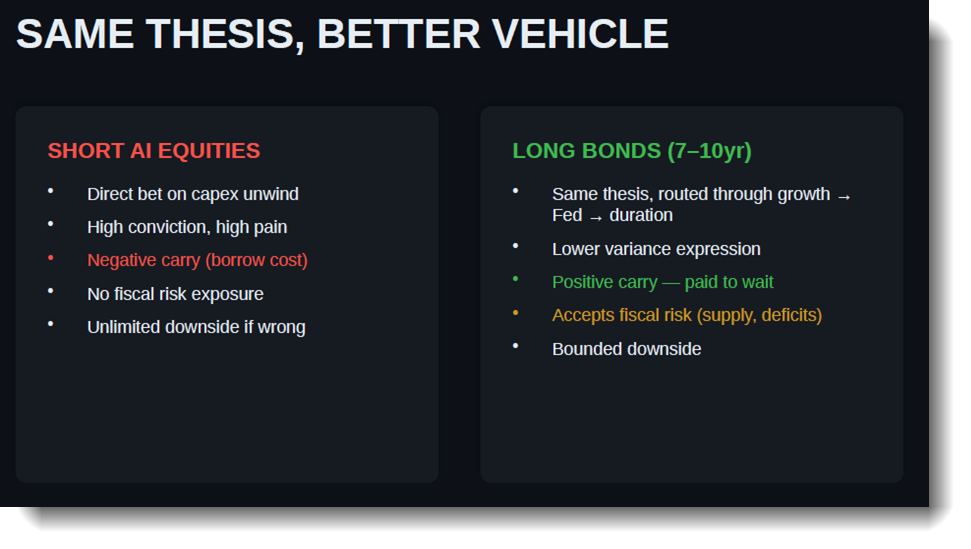
Framework: convexity per unit of duration; simple alternatives include IEF 0.00%↑ (7 to 10 year UST ETF).
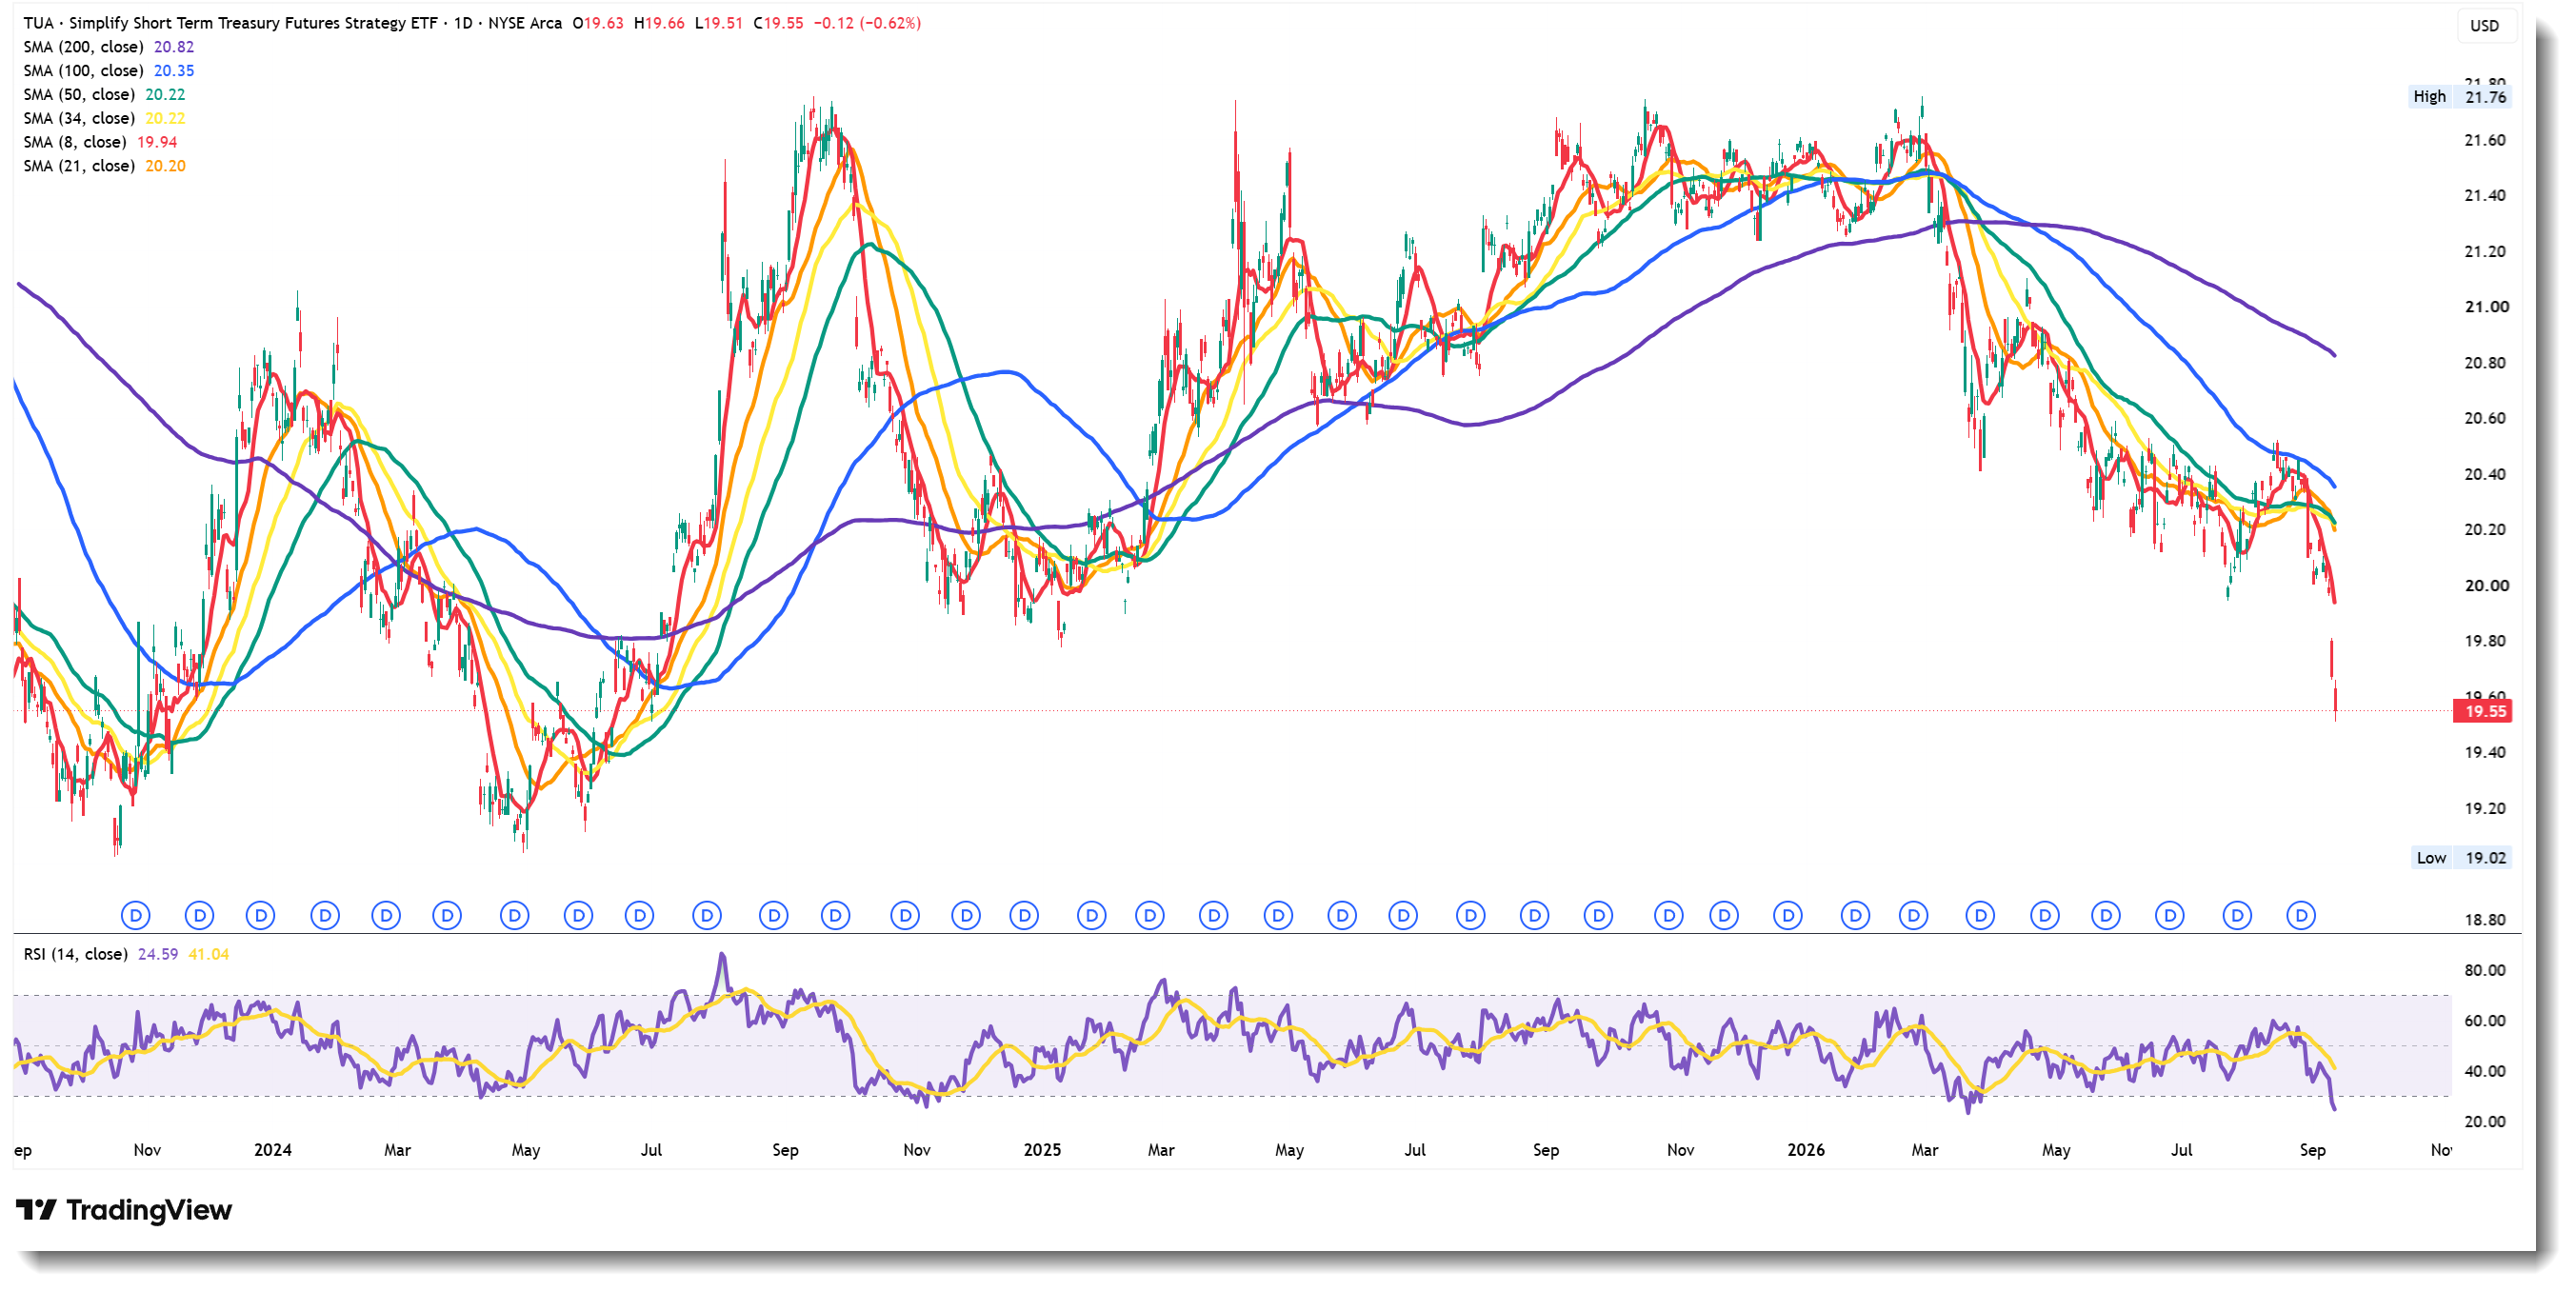
🐿️’s weapon of choice for the beta portfolio: TUA 0.00%↑ , a five times levered play two-year note futures, giving duration exposure without a big term premium bet.
Strategic logic: bonds are a way to play AI rolling over. If CapEx growth stalls and the equity market rolls, the wealth effect (households with years of wages parked in the market) and the physical CapEx economy hit growth simultaneously and feed back on each other.
Short Utilities (Minute 18)
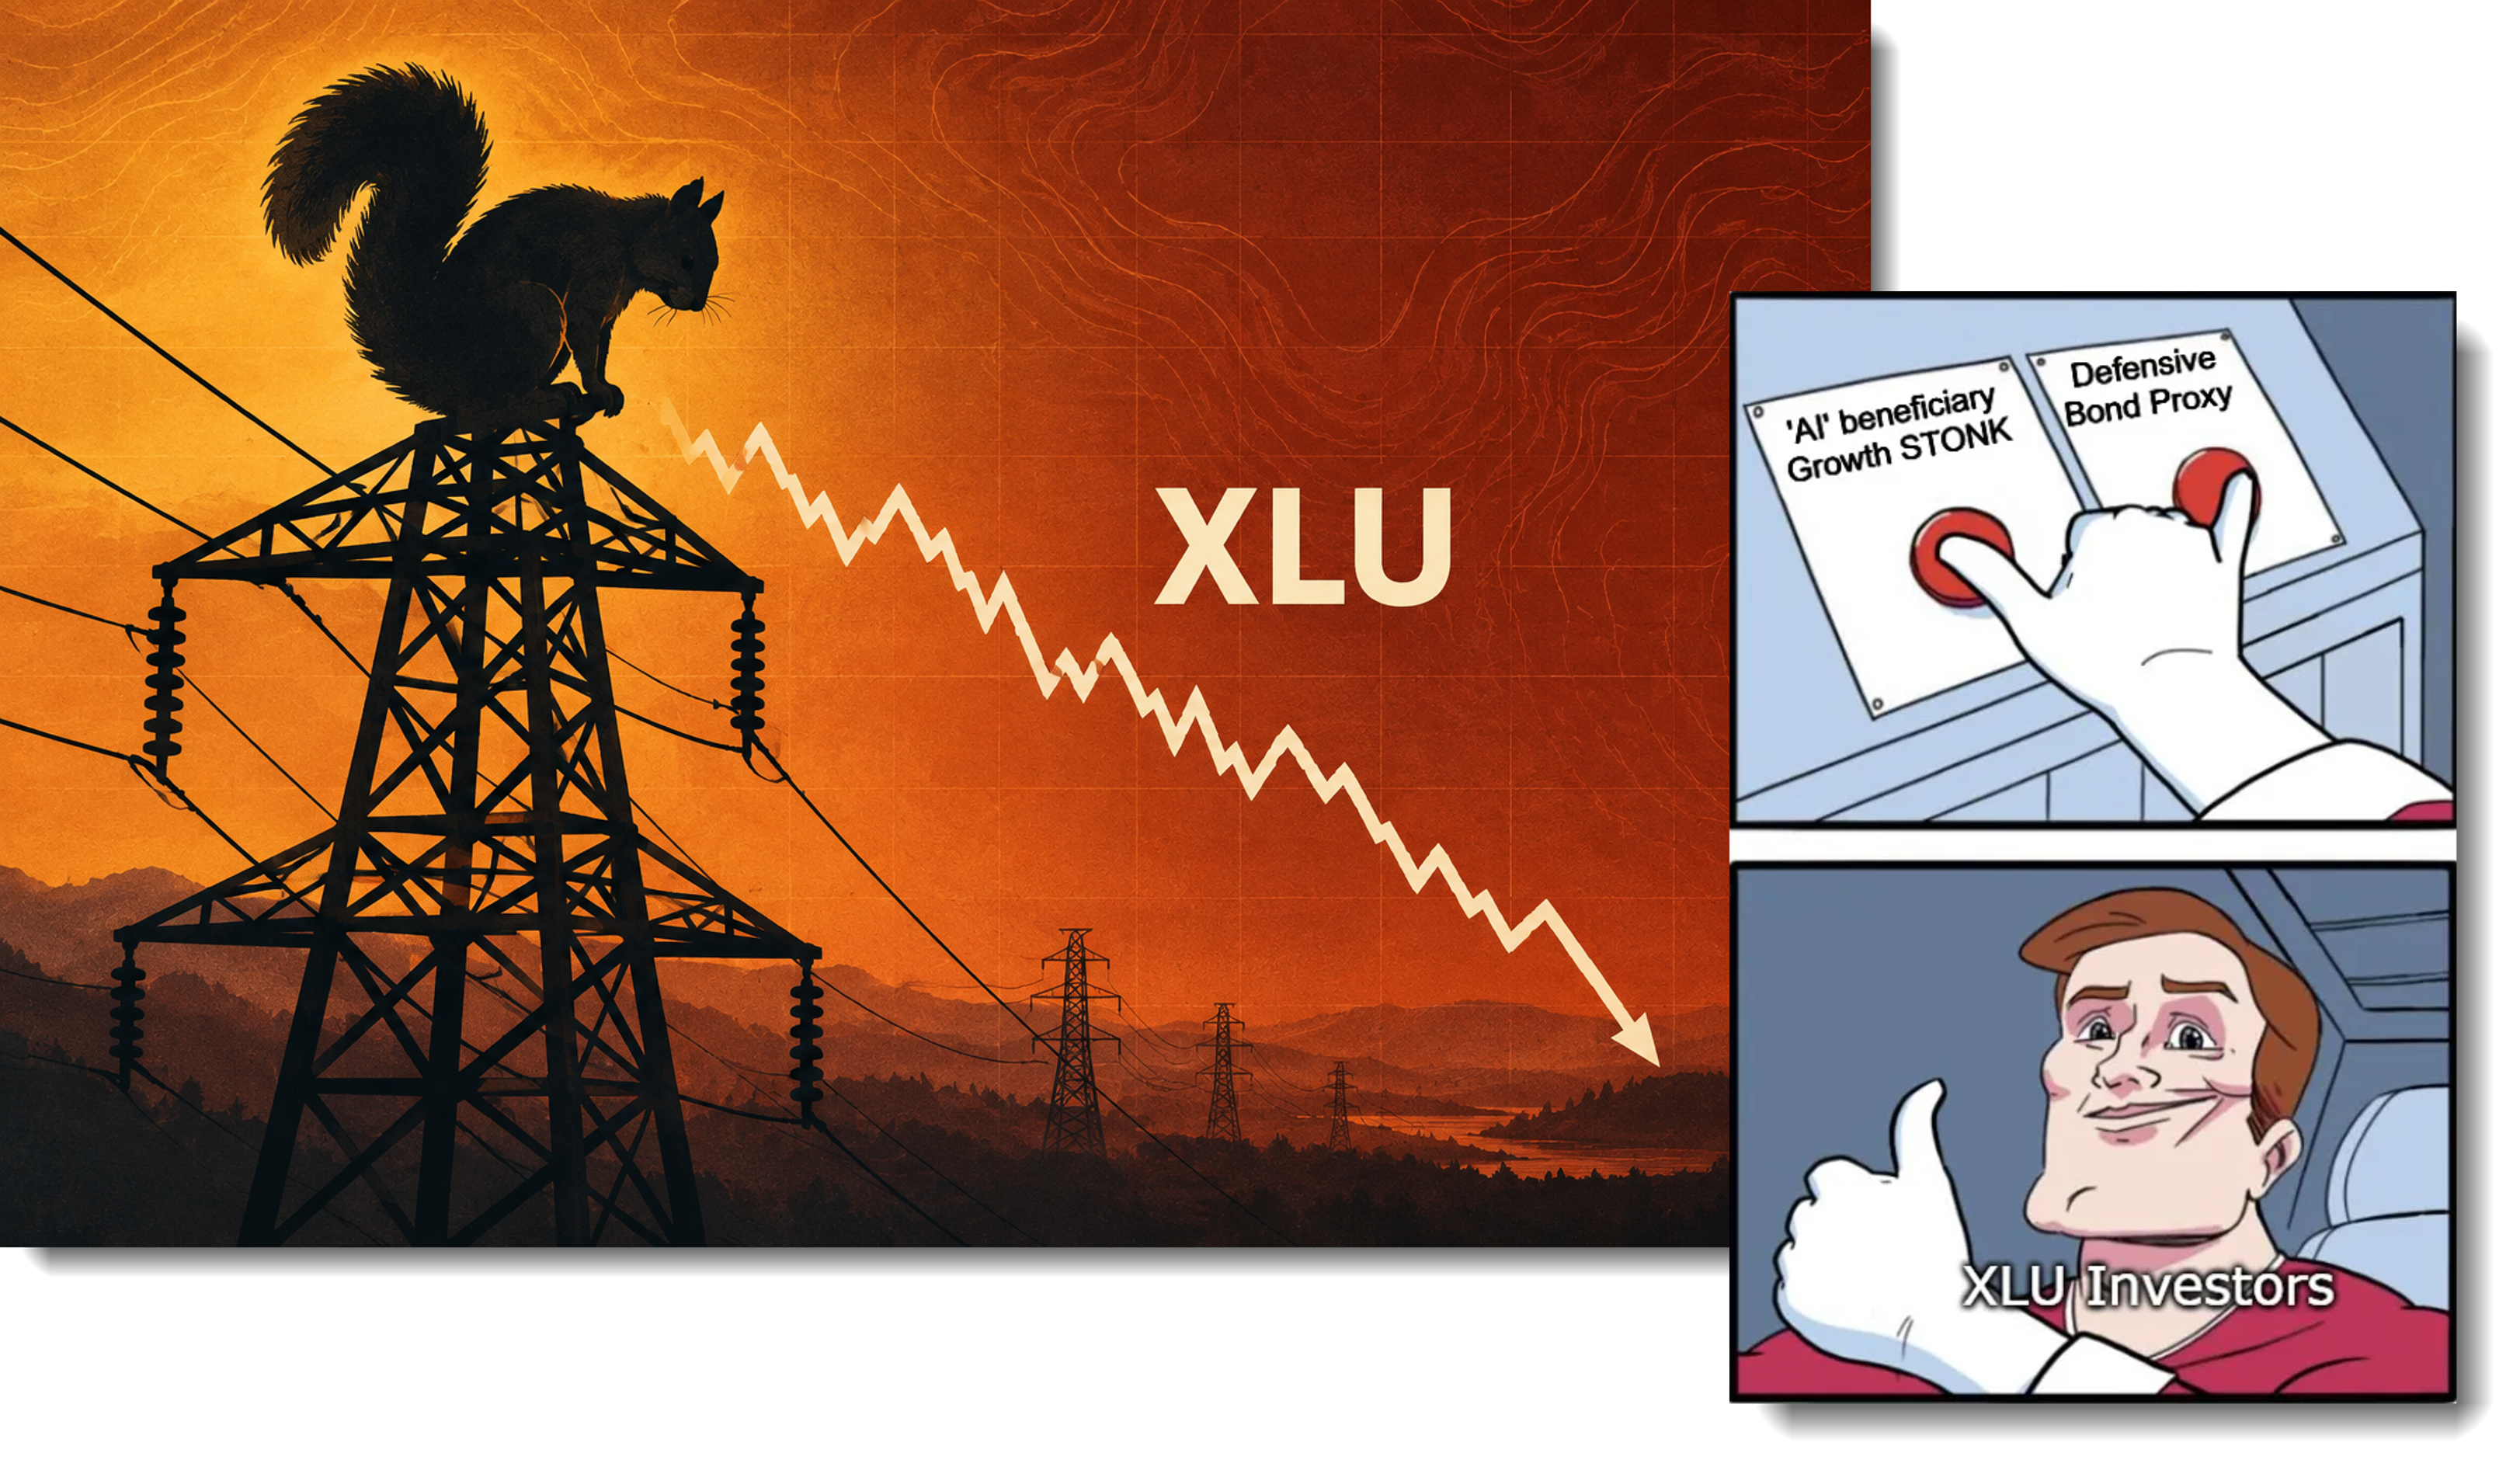
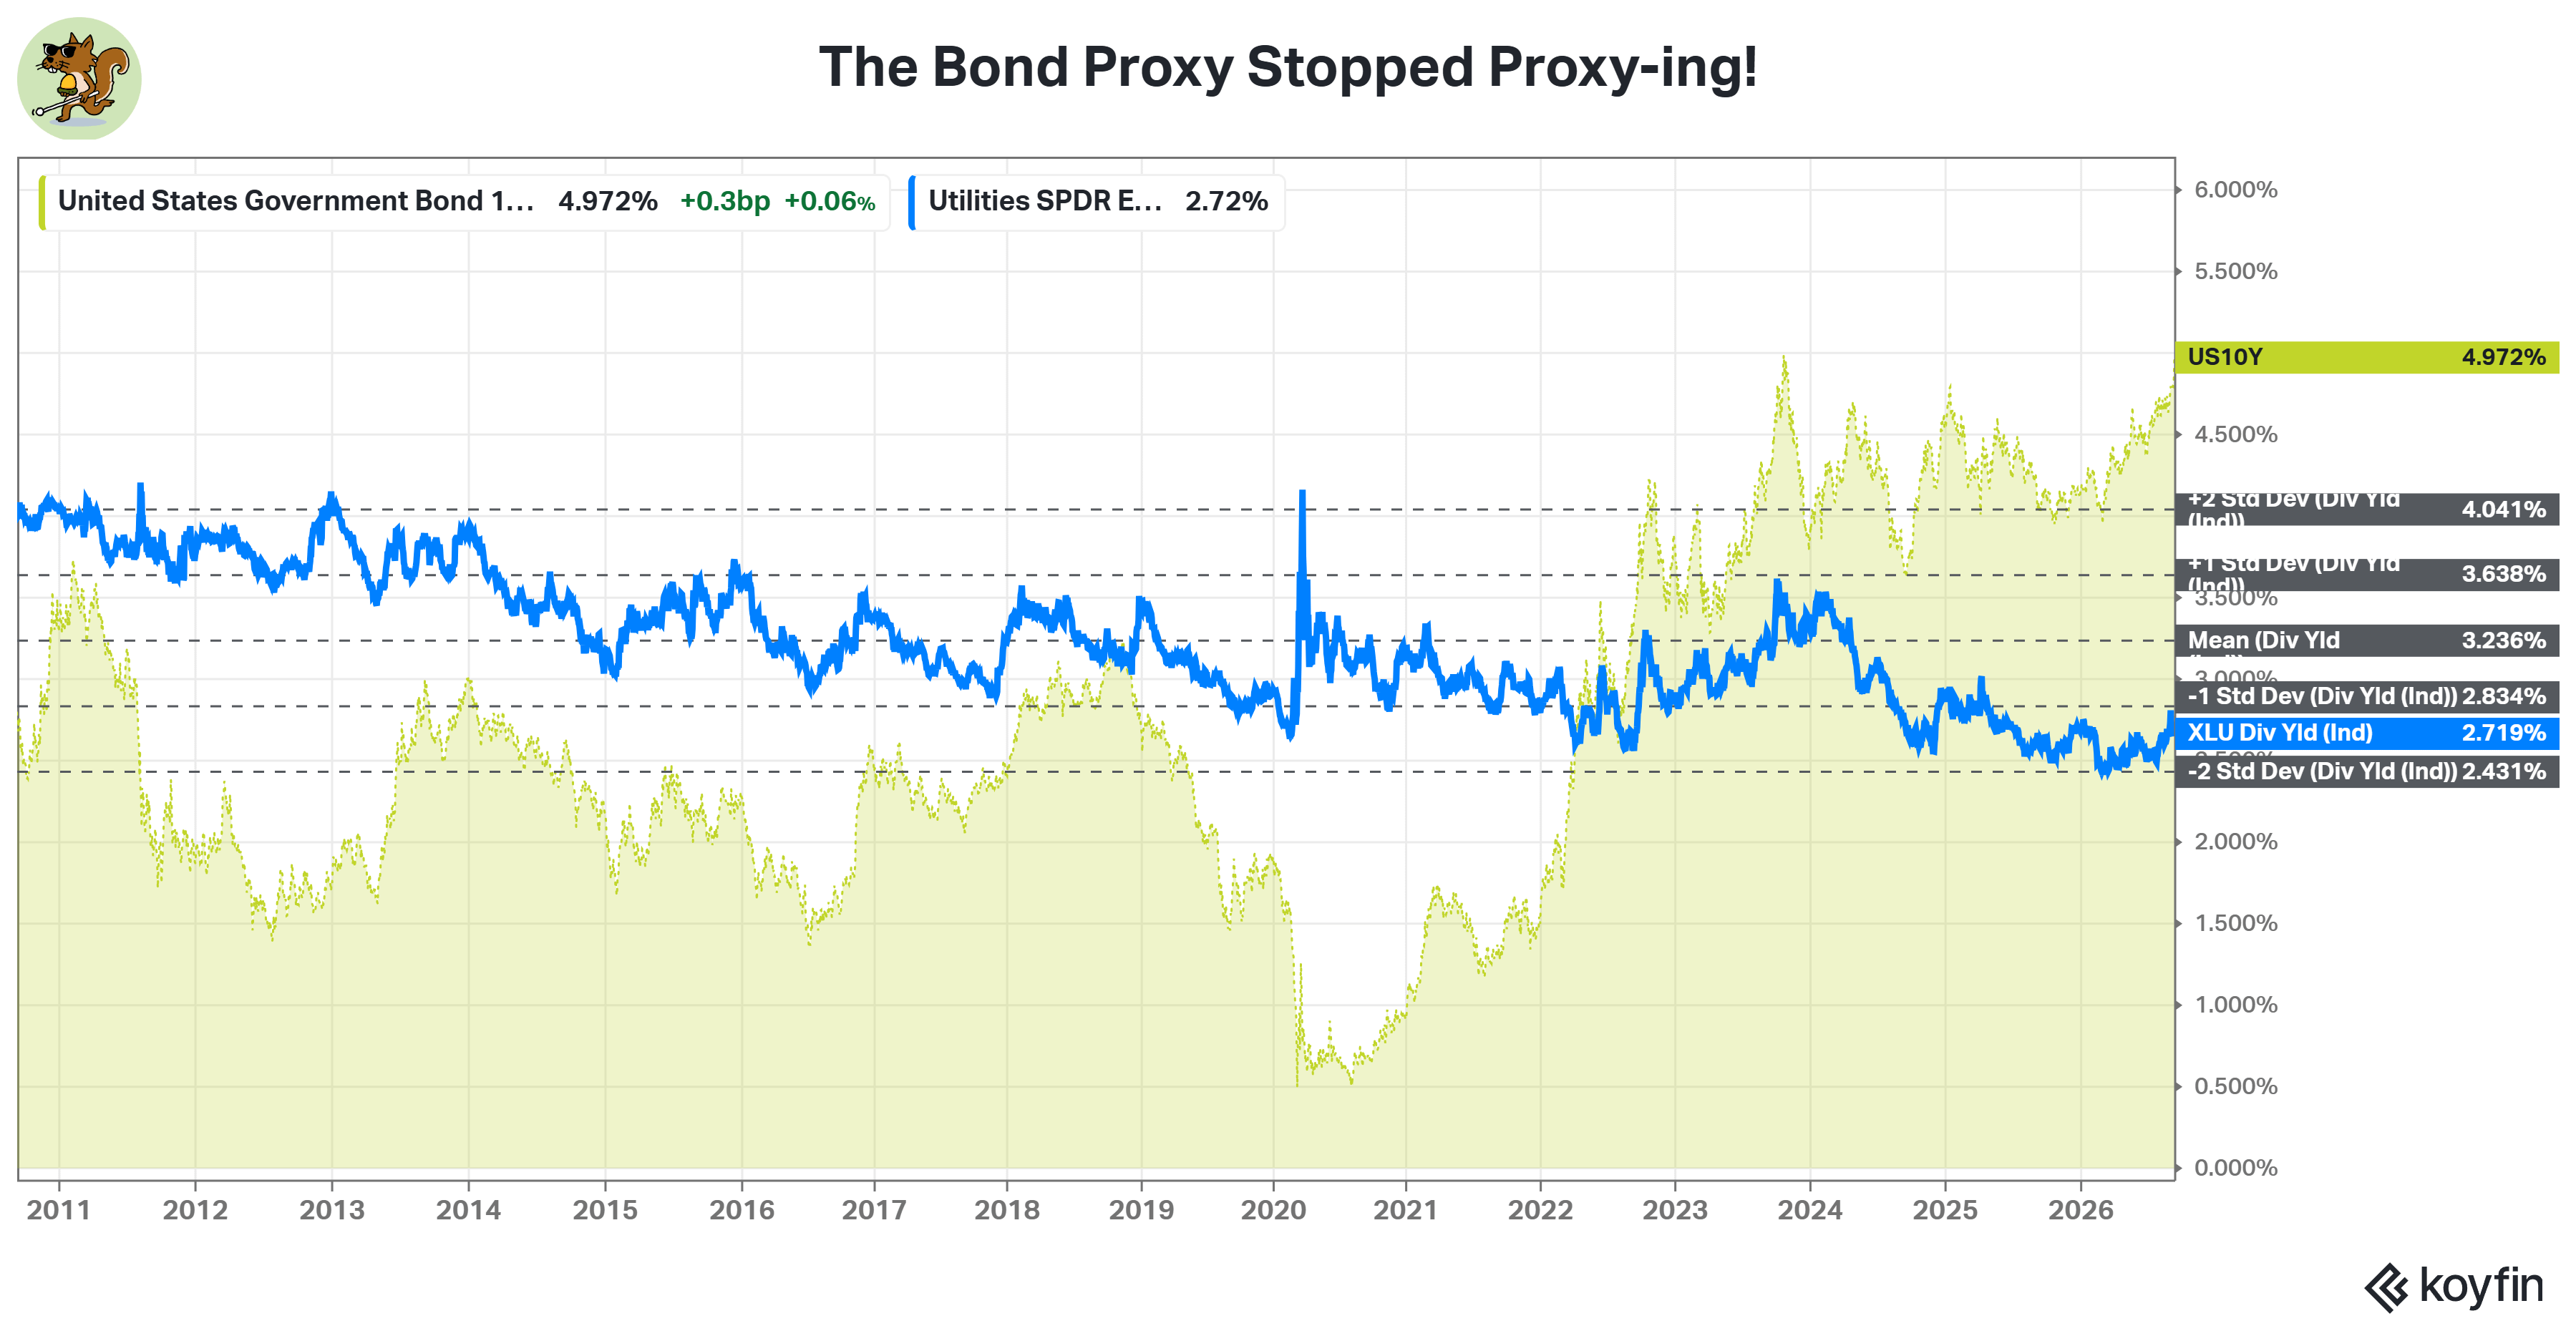
Utilities are no longer trading like bond proxies; since the war began, XLU has ignored rising ten-year yields and become “AI stonks”.
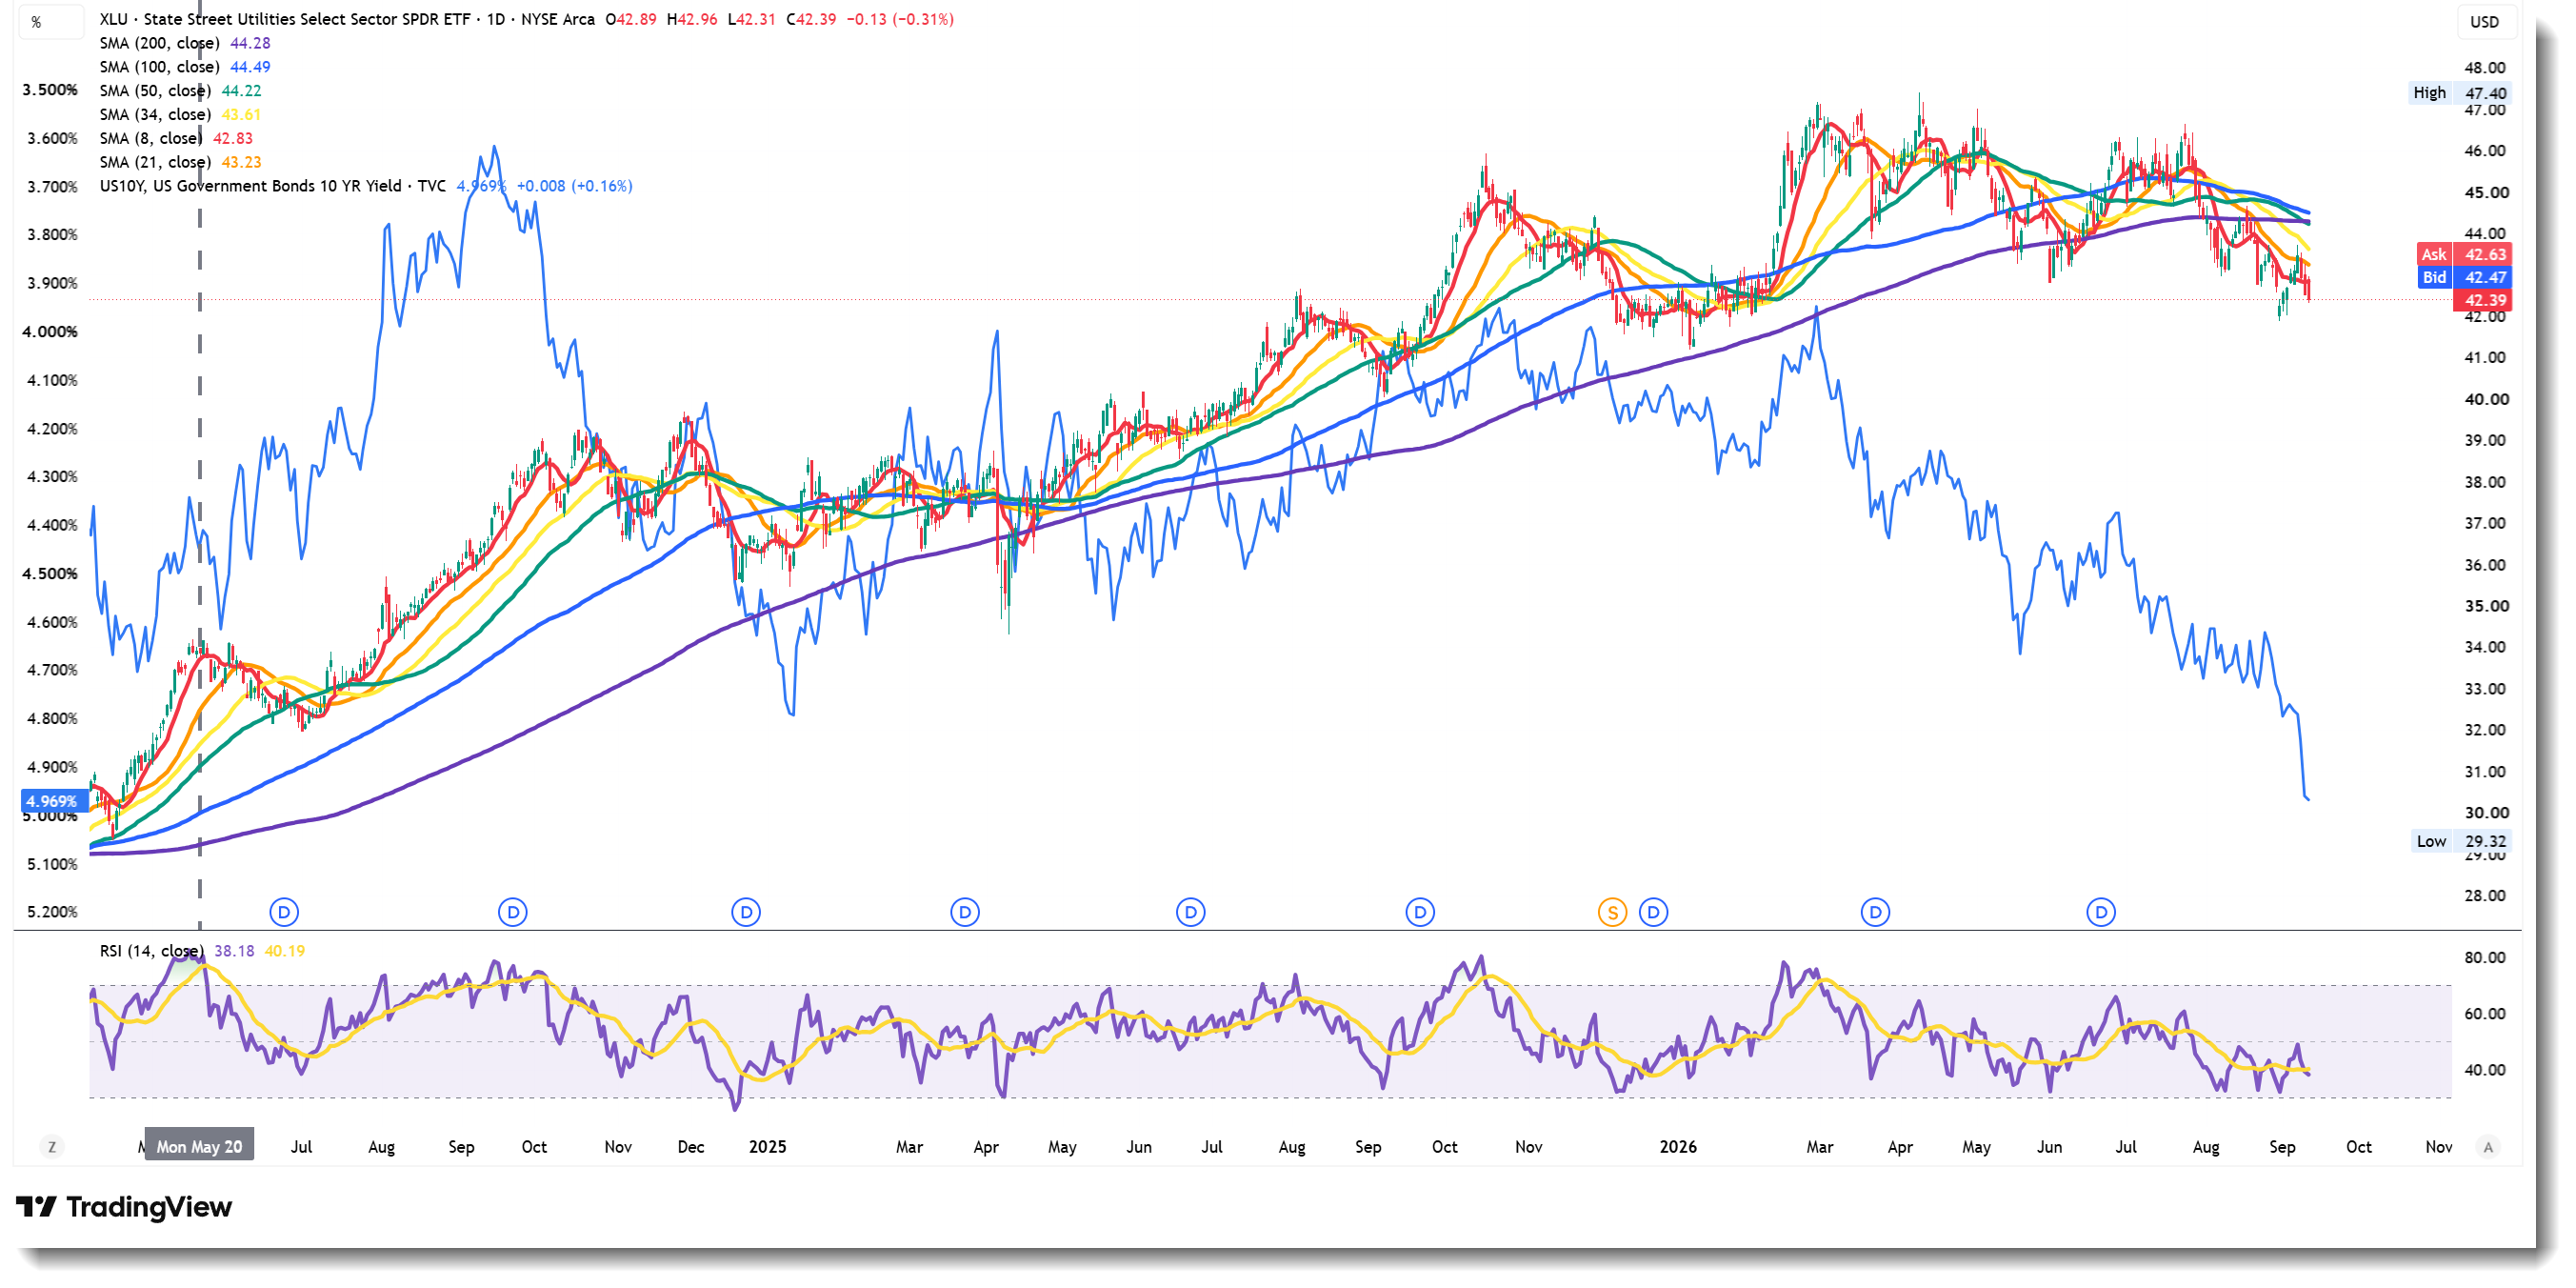
The XLU dividend yield now sits about 225 basis points below the ten-year yield, versus the old “Treasuries plus a kicker” relationship; no bond-proxy protection left.
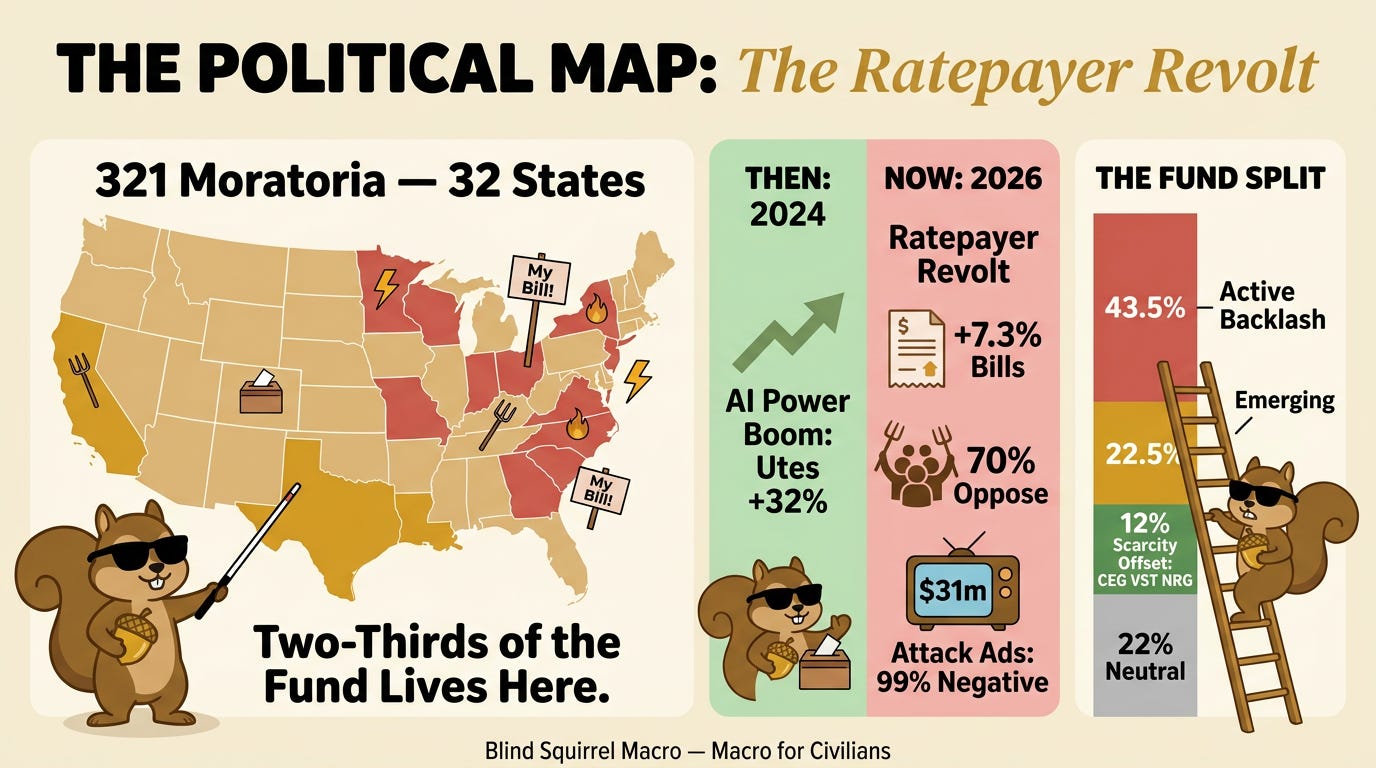
Politics: bashing AI data centers is now bipartisan. Two-thirds of XLU constituents operate in states with legislation to block or delay data centre development. Only the IPPs (Constellation, Vistra, NRG), around 12 percent of the index, can capitalize on scarcity.
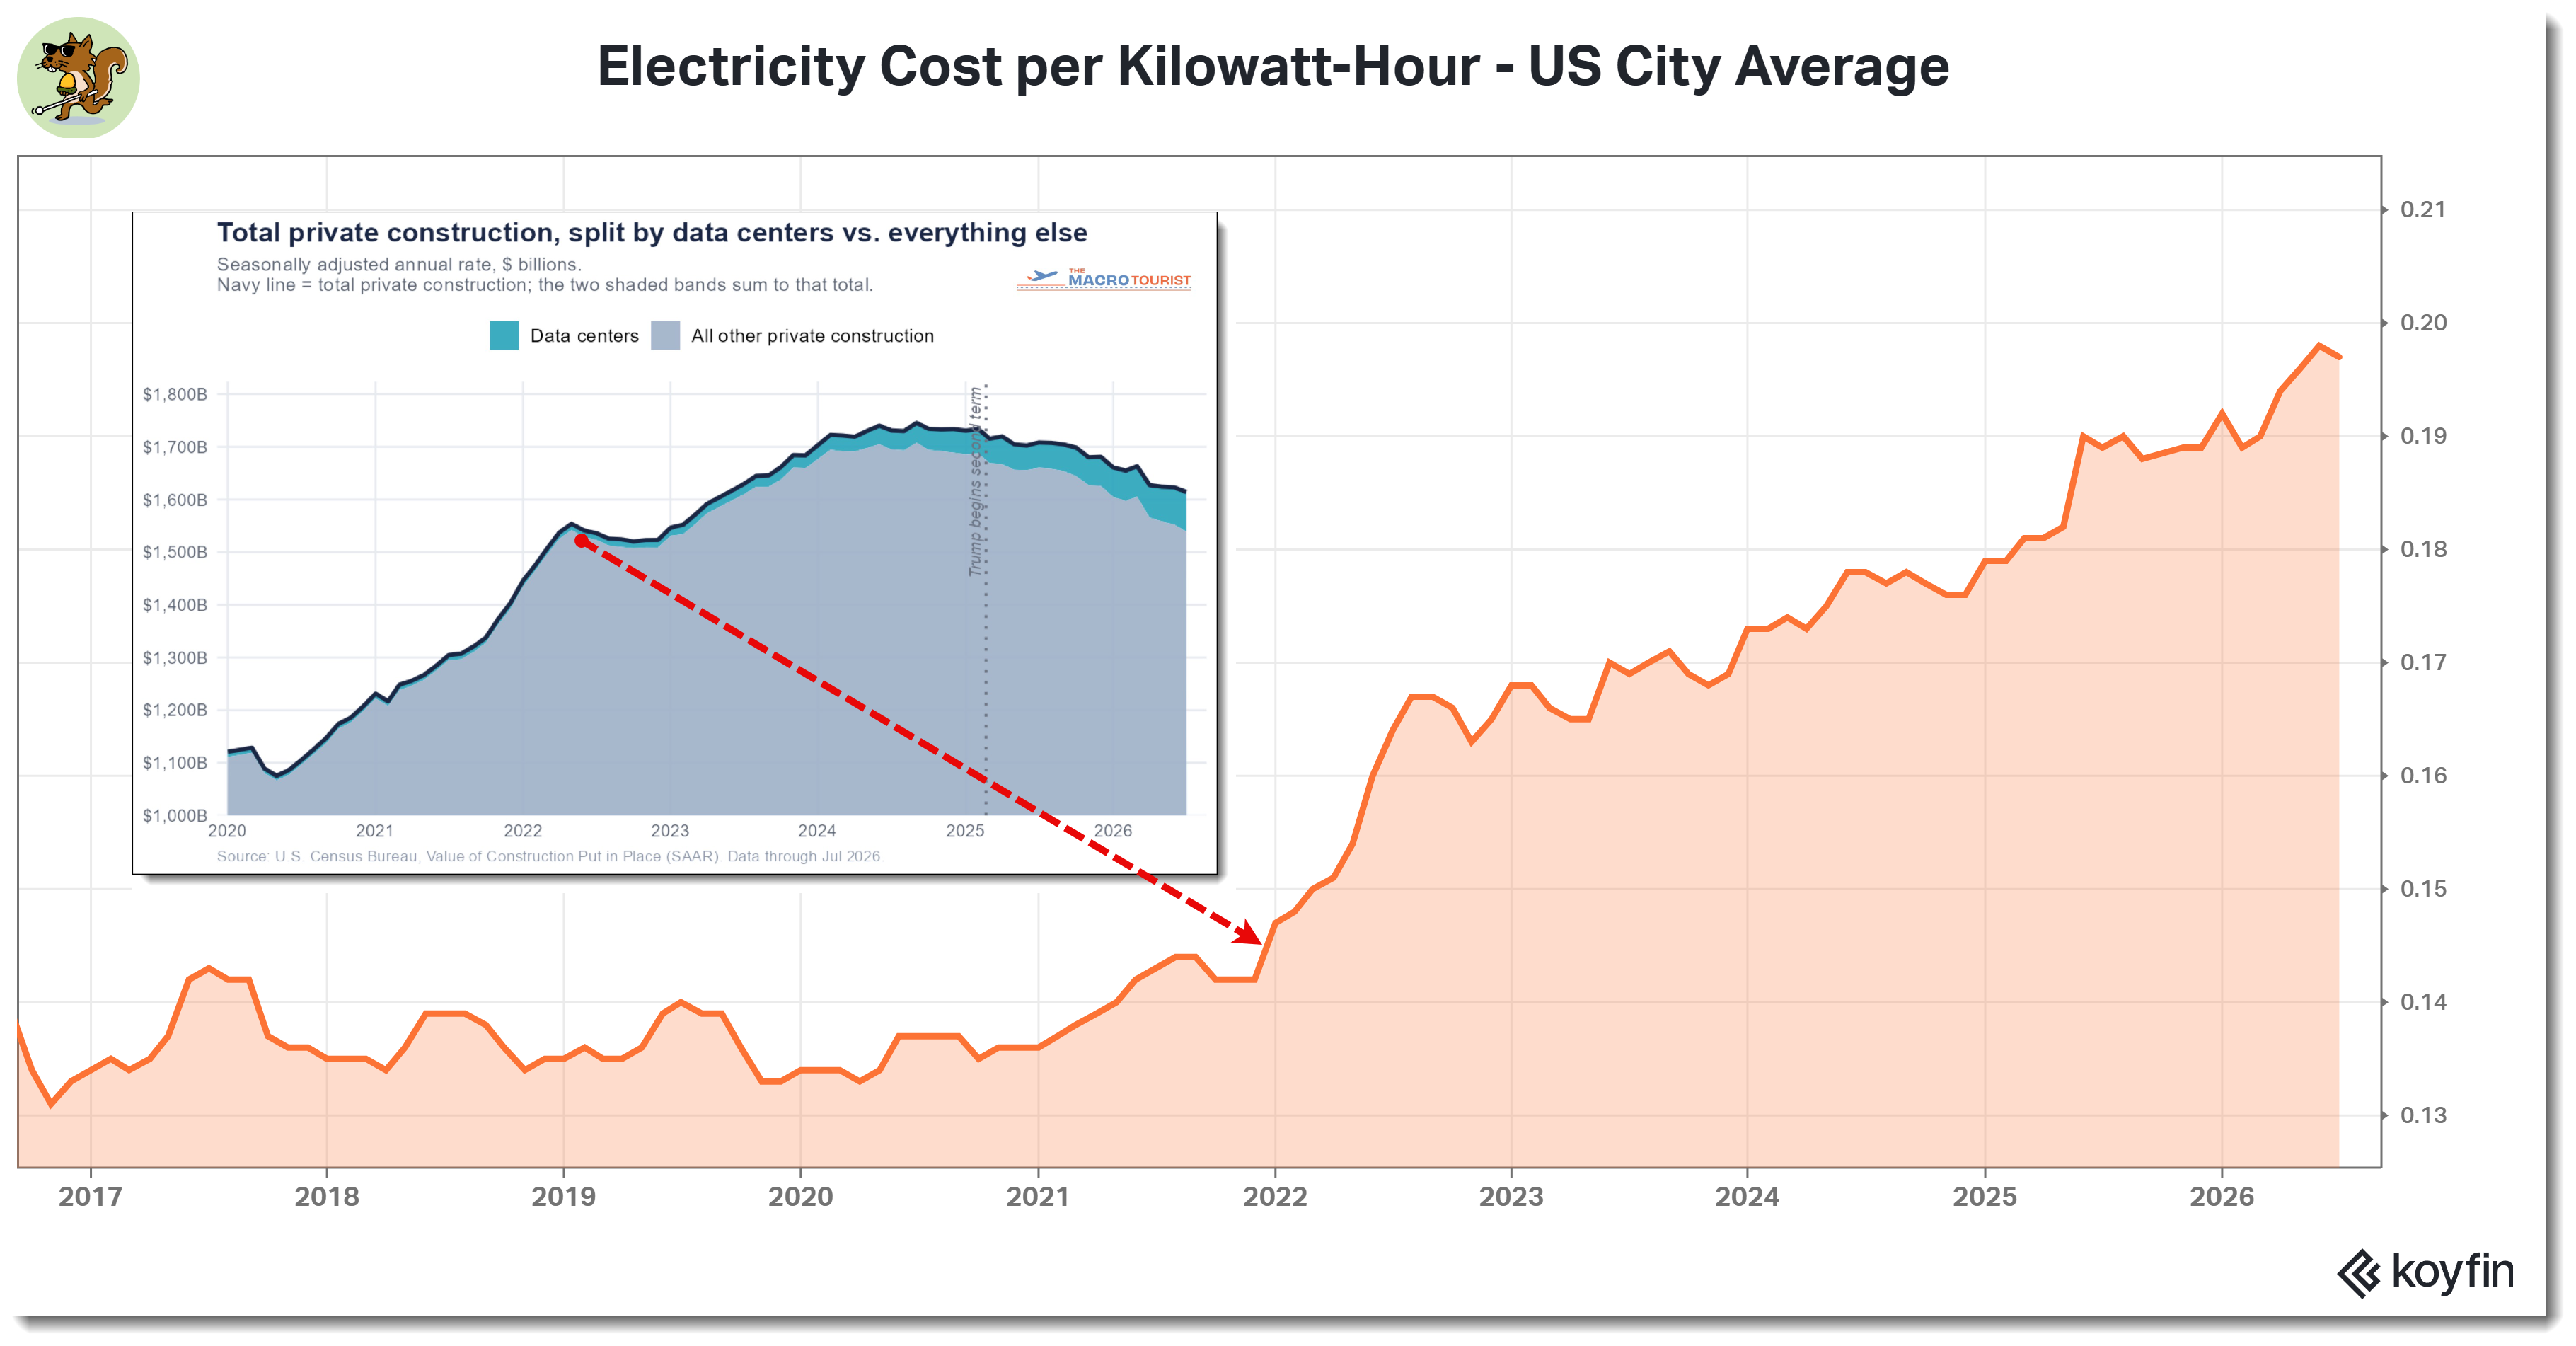
Retail electricity prices have mooned since the public launch of ChatGPT (inset chart borrowed from Kevin Muir).
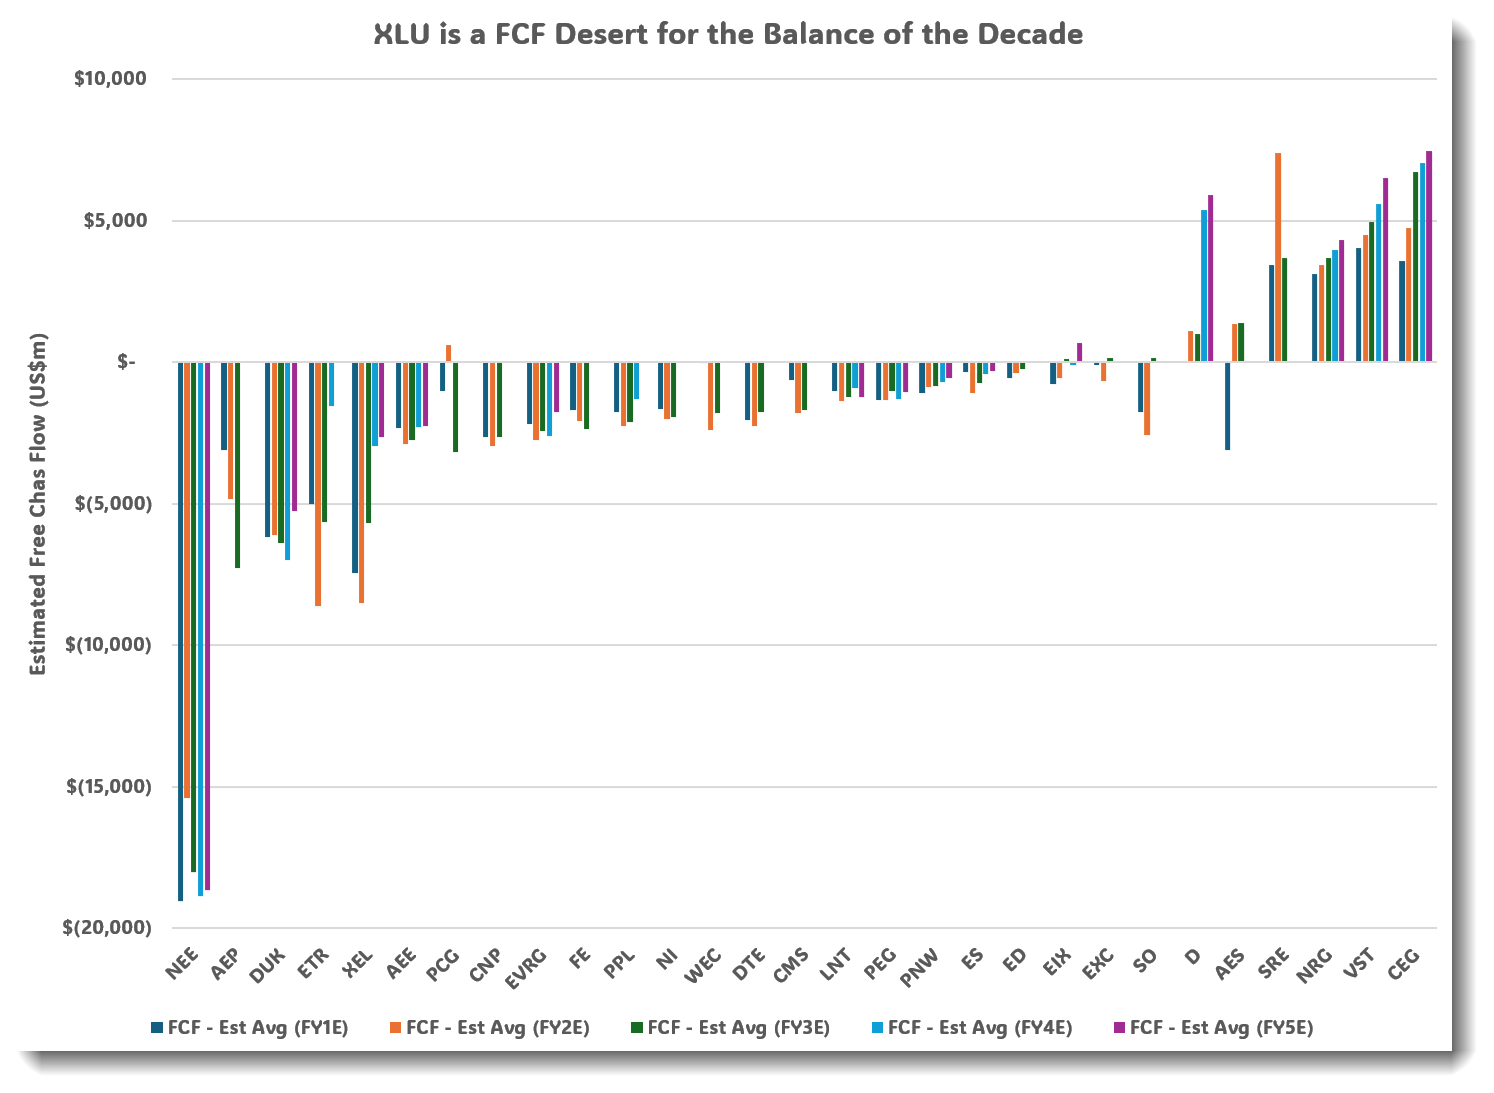
Free cash flow across XLU electricity producers is negative except for the IPPs; most face almost five years of negative free cash flow.
The trade rounds out nicely: ‘short utes’ paired with the levered two-year note ETF (TUA) - may give the position more ‘staying power’.
Hyperscalers and the model labs (Minute 23)
Anthropic chooses NASDAQ, OpenAI pushes its timeline out; commitments already made matter for future Magnificent Seven earnings, and paper mark-ups that boosted earnings become headwinds if marked down.
Tailwinds and headwinds for hyperscalers: a frontier-level slowdown cuts CapEx (market positive) but forces write-downs in equity stakes against a general growth slowdown.
Advertising: OpenAI was the fastest to a billion dollars of ad revenue ever, in a roughly one trillion dollar global market that is only GDP-plus growth and cyclical; a knife fight with Meta and Google. Stop treating the Mag7 as a monolith!
Most hyperscaler forward CapEx supports training runs for the two jumbo private customers (OpenAI and Anthropic); inference earns ‘decent vig’ but is not the driver. If local models keep spreading, cloud growth may disappoint.
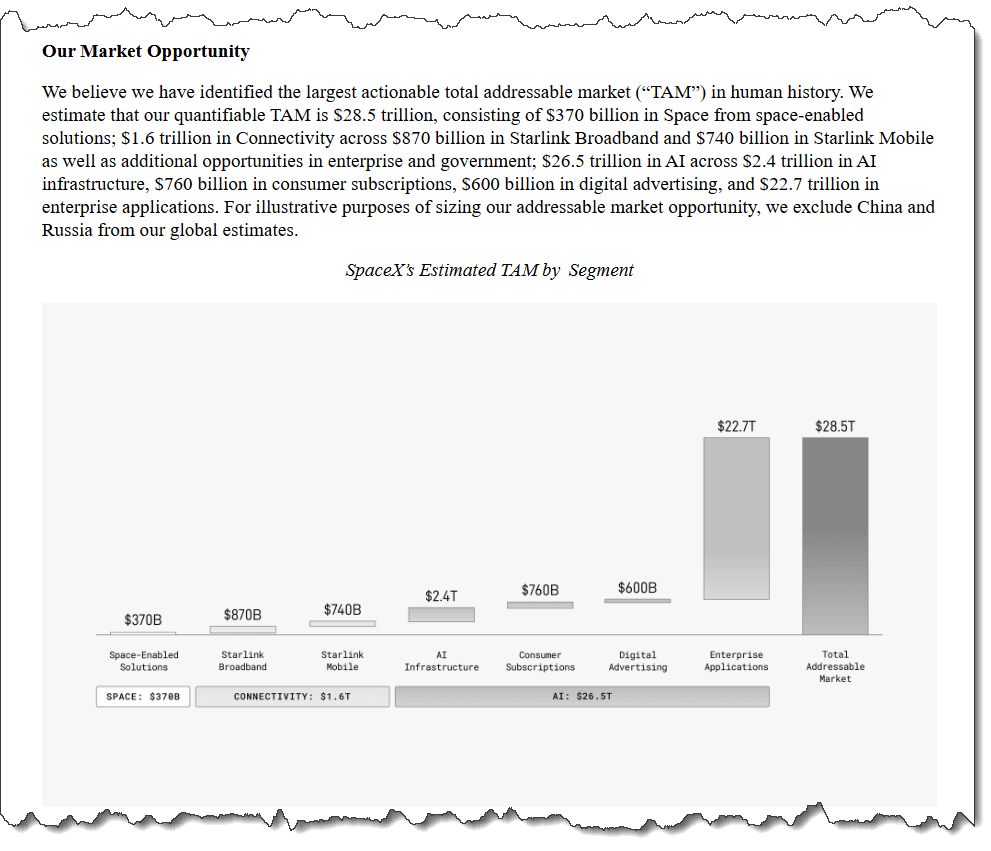
The 26 trillion dollar enterprise TAM chart from the SpaceX S-1 “will age terribly”; every Fortune 500 company bringing AI in-house (Latham Watkins trend, more anecdotal cases) takes a bite out of that TAM.
The Fed decision (Minute 28)
Scenario walk-through: market pricing around 86 percent for a 25 basis point hike on Wednesday; both Benny and 🐿️ see it as a done deal.
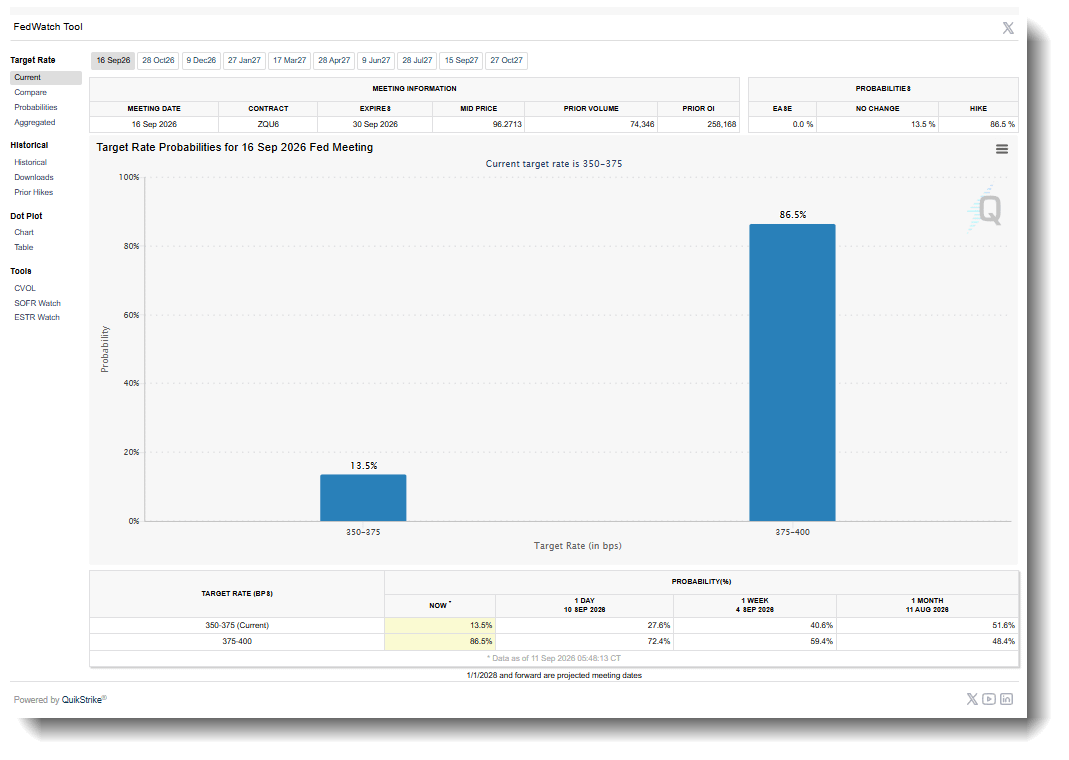
Credit to Warsh for making meetings “live” again; he was hawkish at Jackson Hole and has kept markets guessing versus the Powell era.
If they did not hike, term premium becomes a problem and the long end is ‘lost’ quickly. Both hosts are buyers of bonds into a rate hike because they think it is the ‘death shot’ (and probably the last one).
If you act on anything provided in this newsletter, you agree to the terms in this disclaimer. Everything in this newsletter is for educational and entertainment purposes only and NOT investment advice. Nothing in this newsletter is an offer to sell or to buy any security. The author is not responsible for any financial loss you may incur by acting on any information provided in this newsletter. Before making any investment decisions, talk to a financial advisor.


