

This week broke most correlations in the book!
Show Notes
French politics and OAT
French OATs now trade wider than Italian BTPs
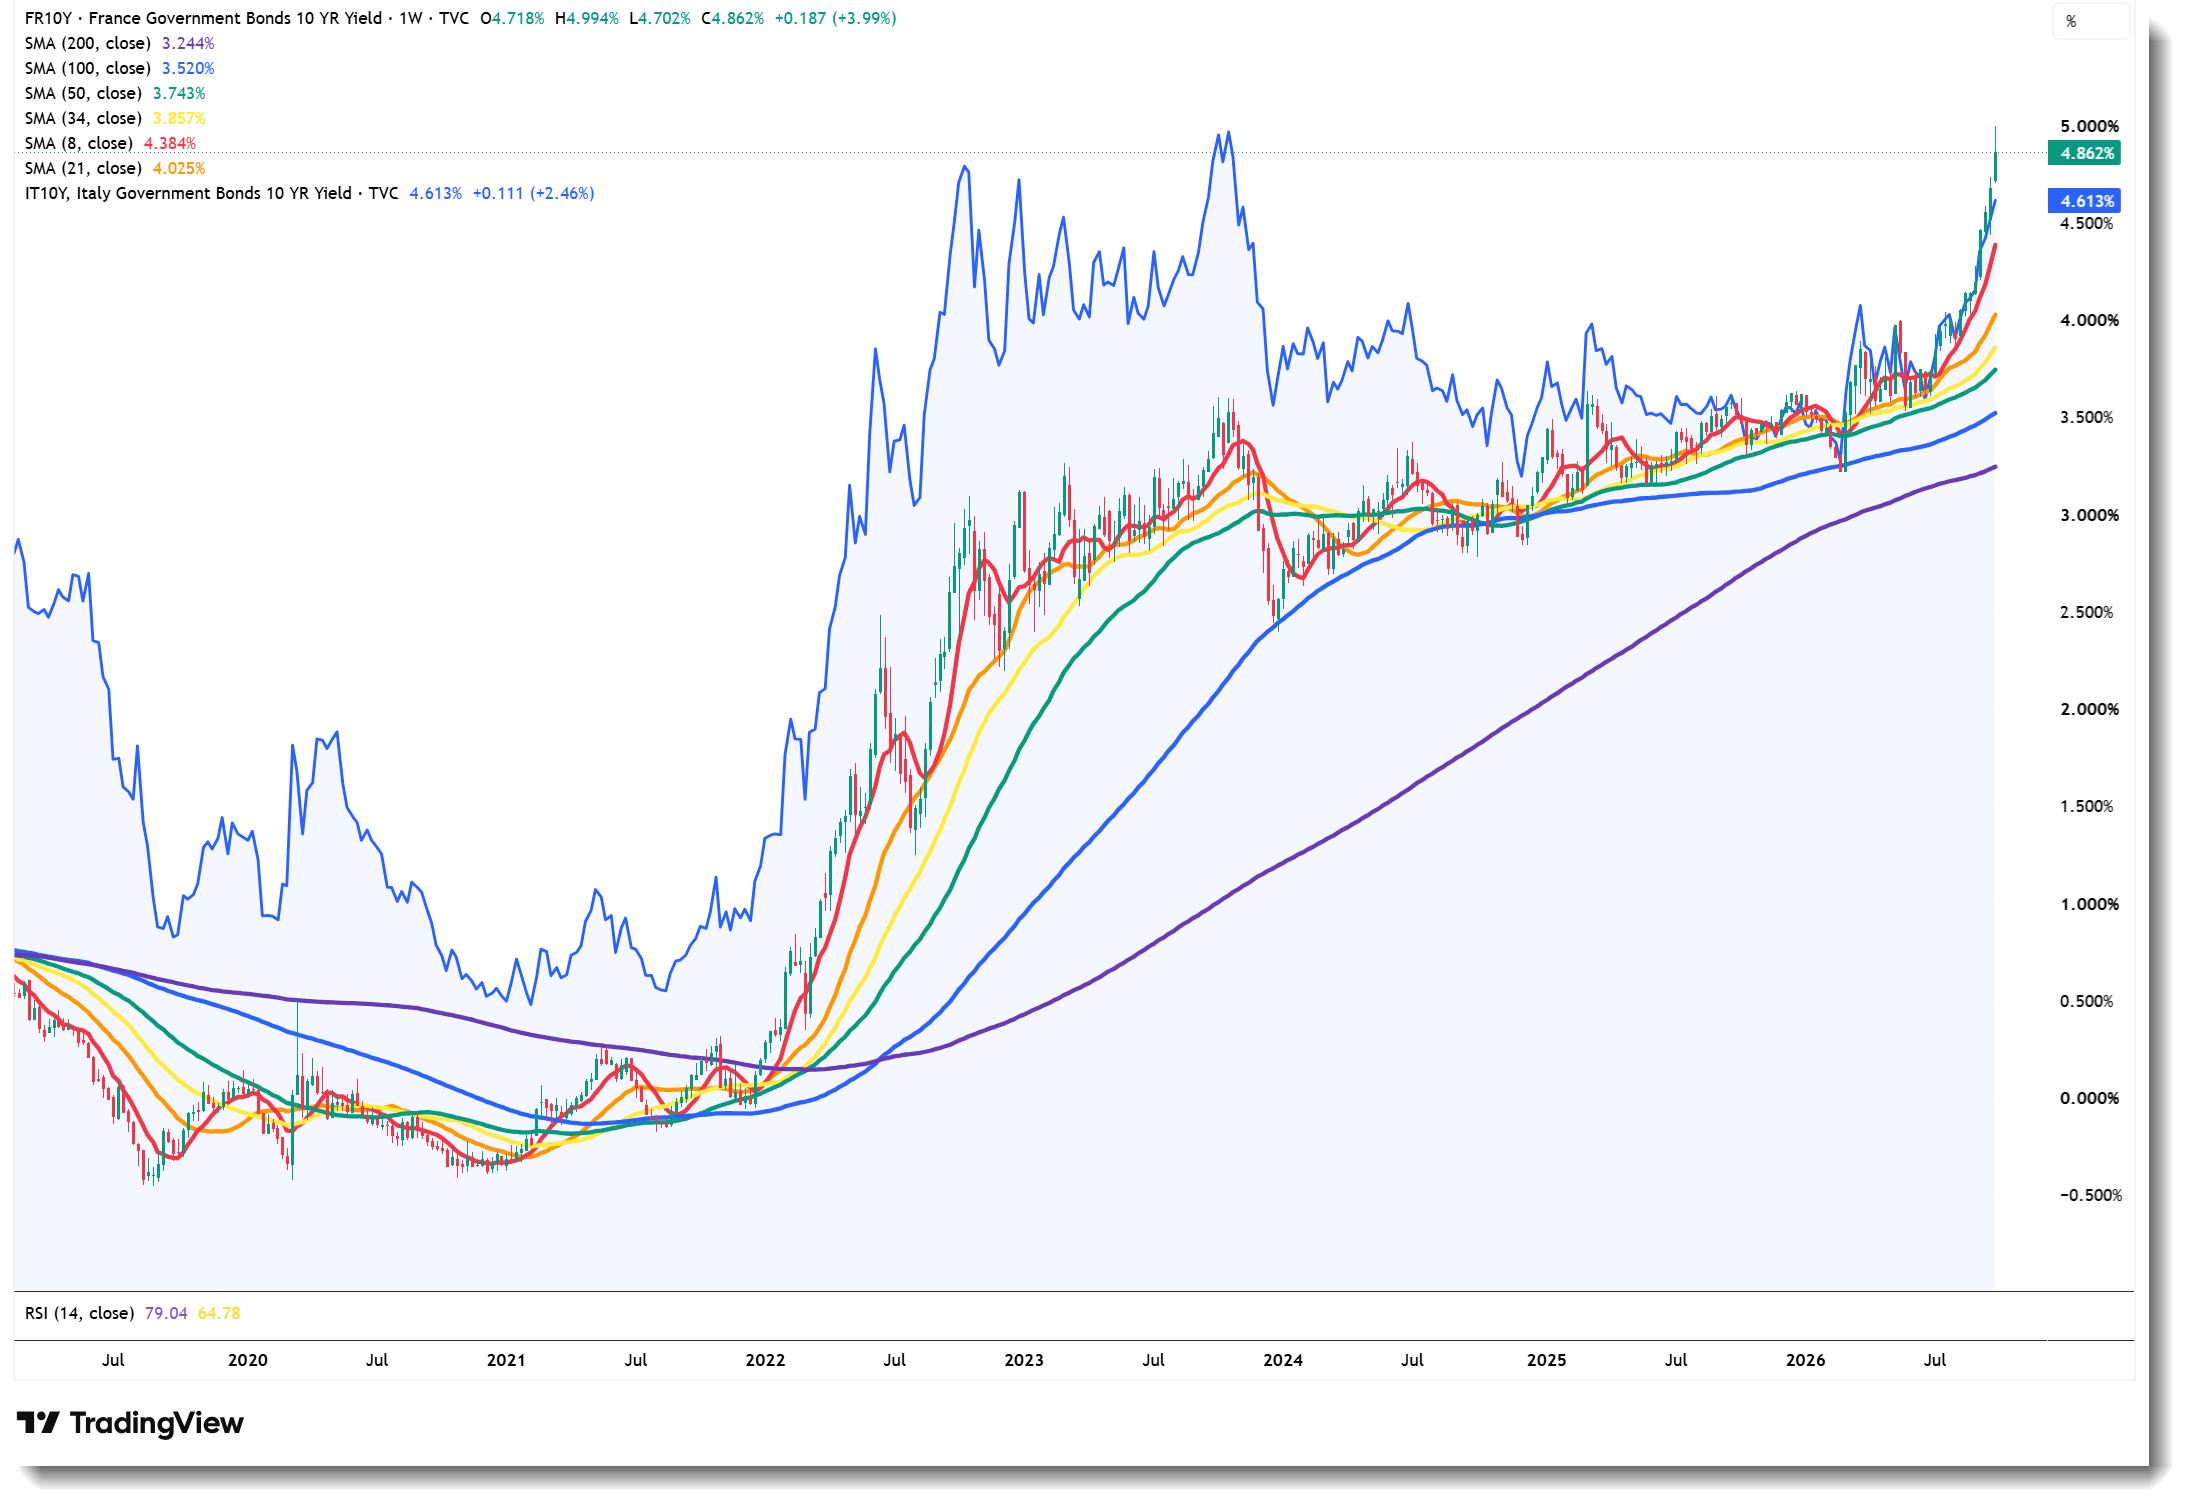
Framed as an old-fashioned political crisis: markets waking up to the risk of a Le Pen vs Mélenchon second round in next year’s presidential election, with no centrist to rally around
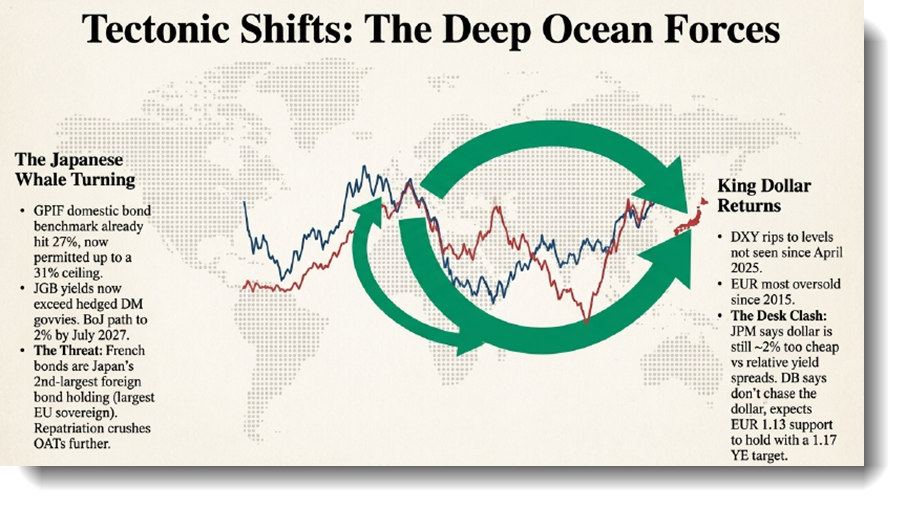
Exacerbated by Japanese sovereign selling…
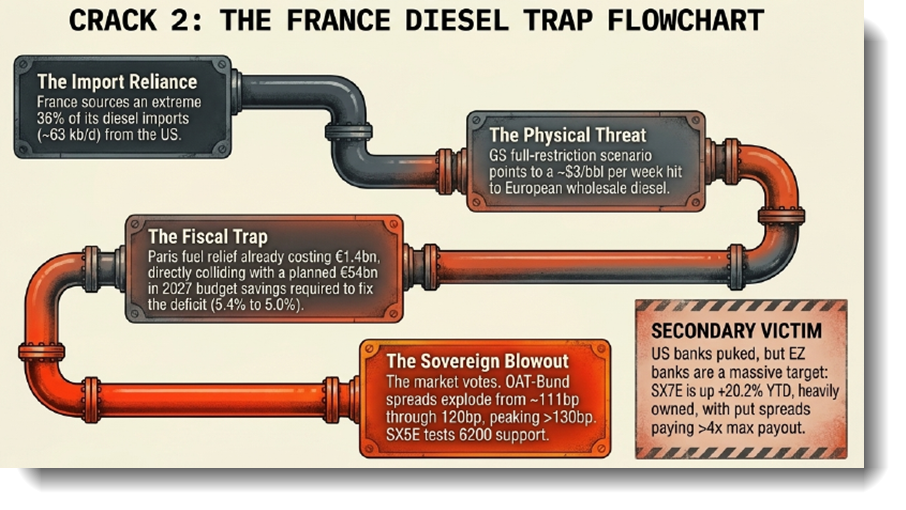
,,, and the global diesel crisis
Carry trade unwind and rates deleveraging (Minute 3)
Second major carry unwind this year; in deleveraging, price is irrelevant and positioning is everything
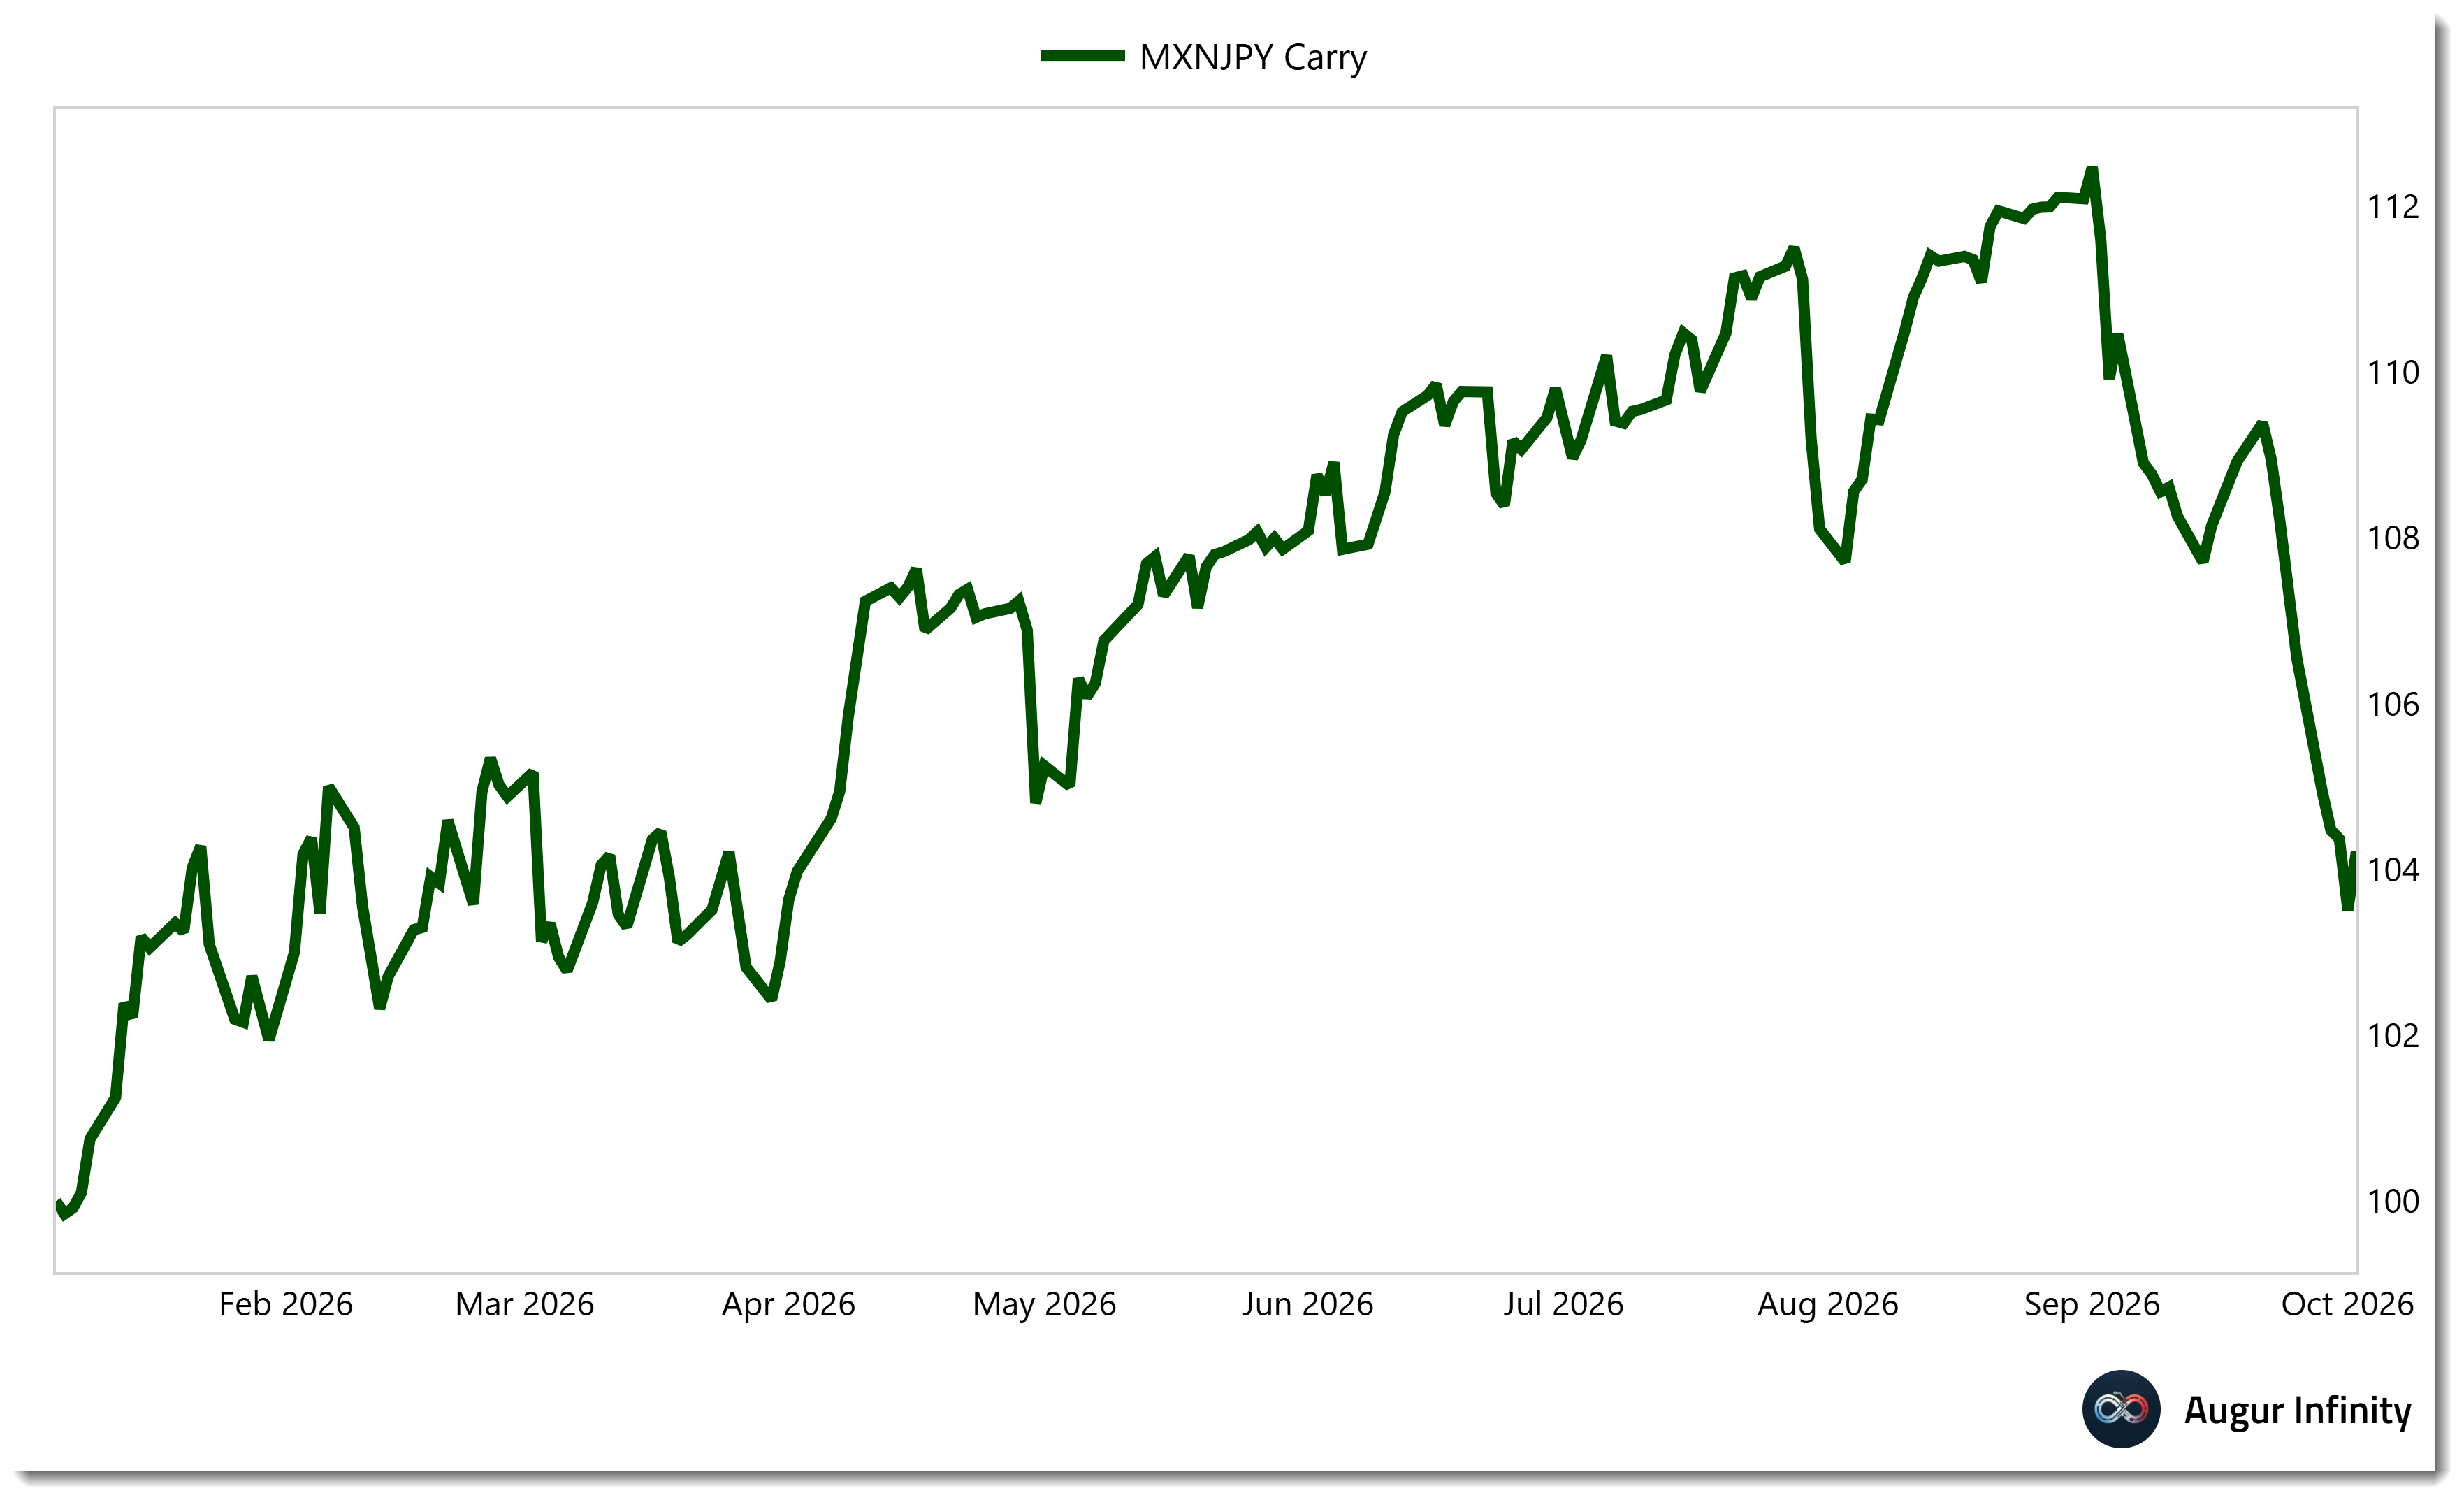
Mexican peso/yen carry trade gave back 8 of its 12.5 year-to-date point gains in September alone
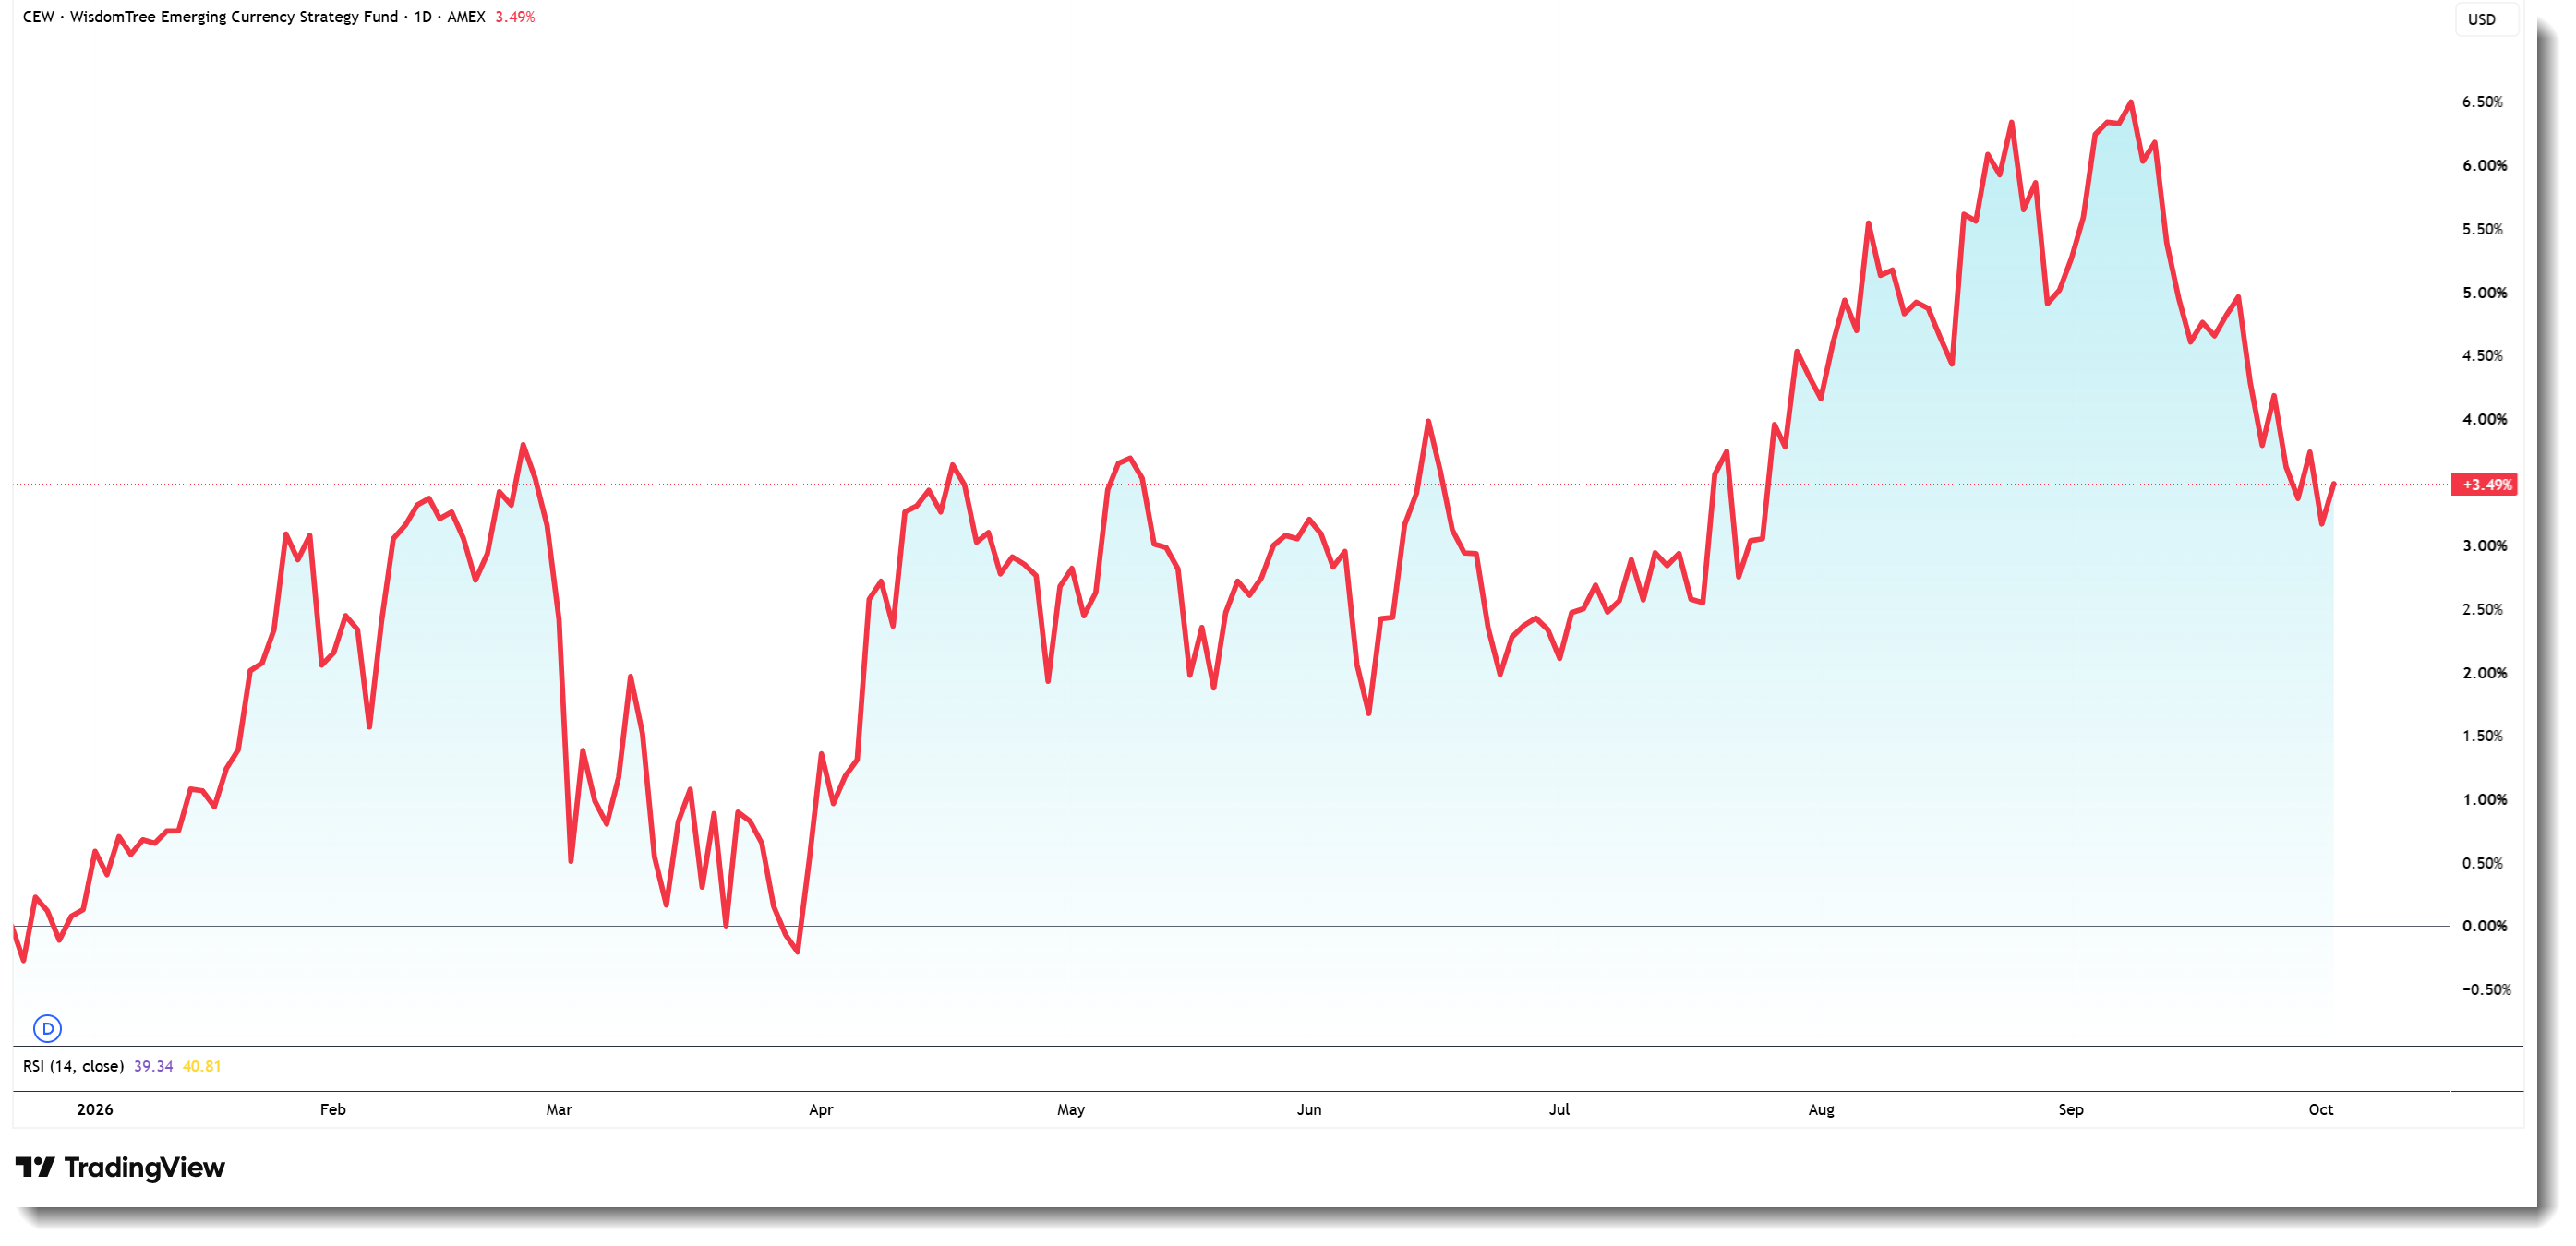
WisdomTree EM currency fund surrendered half its year in 30 days
Friday’s jobs report: 29k headline miss with wage disinflation, yet rates finished higher on the day, a sign that forced deleveraging overpowered the data
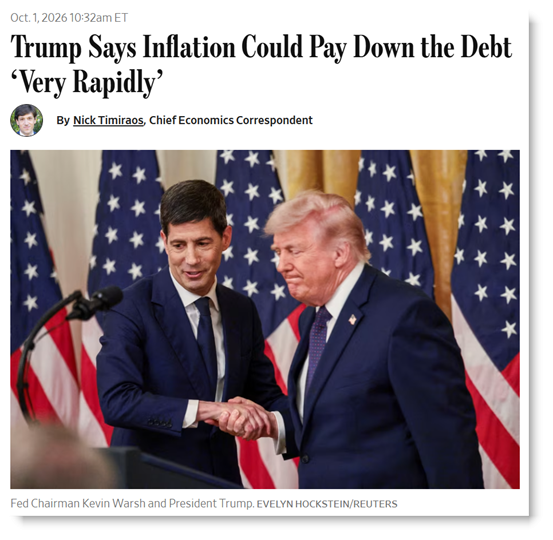
Hawkish central bank rhetoric viewed as a show; the administration is “saying the quiet part out loud” that inflation is the debt paydown playbook, since no politician will choose debt deflation or austerity
Equity internals: a hidden bear market (Minute 9)
Median and mean stocks down roughly 25% while indices sit near highs; around 70% of the S&P 500 trades below its 50-day moving average
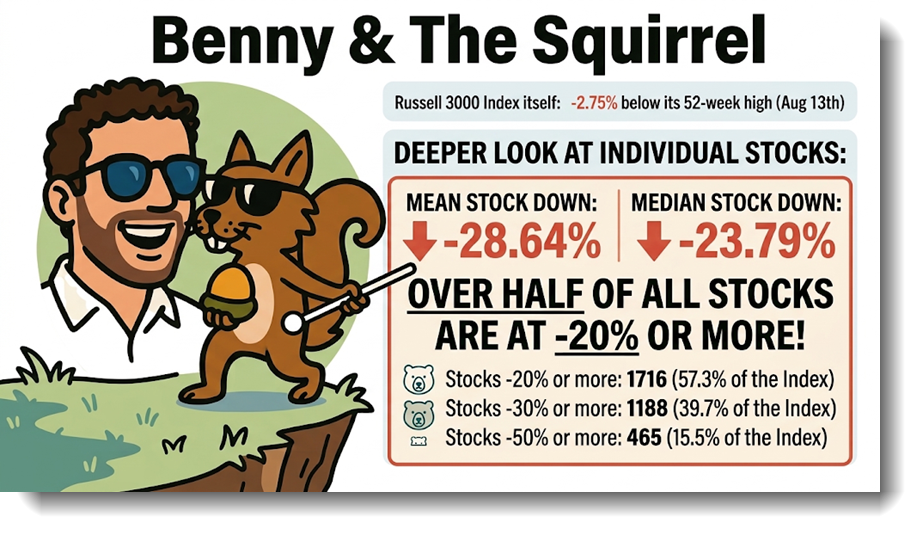
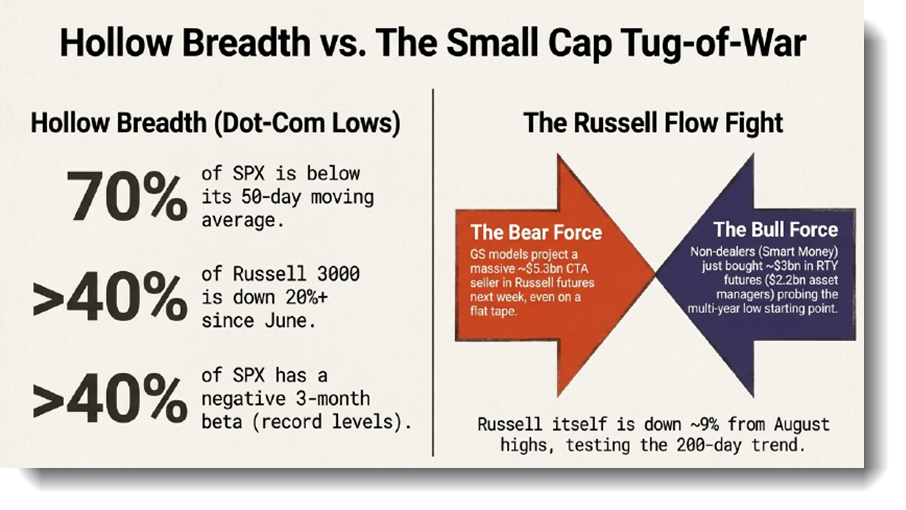
Rate-sensitive and non-AI small/mid caps are orphaned; September was brutal for long-only stock pickers
Hunger Games thesis: in a competition for capital, the outer districts (illiquid periphery) pay first
Higher yields plus higher energy costs squeezing the levered economy; real estate and private credit/equity players growing visibly nervous
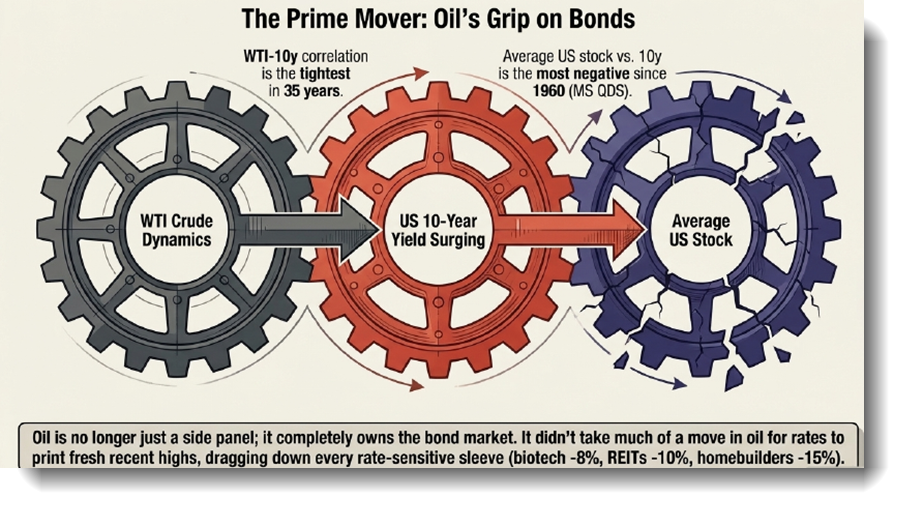
Only just over 1 of the 3 to 4 hikes priced through next year seen as realistic; December ‘27 SOFR position rallied 30bps (95.07 to 95.36) before reversing with rates
The AI put and Russell Resilience (Minute 16)
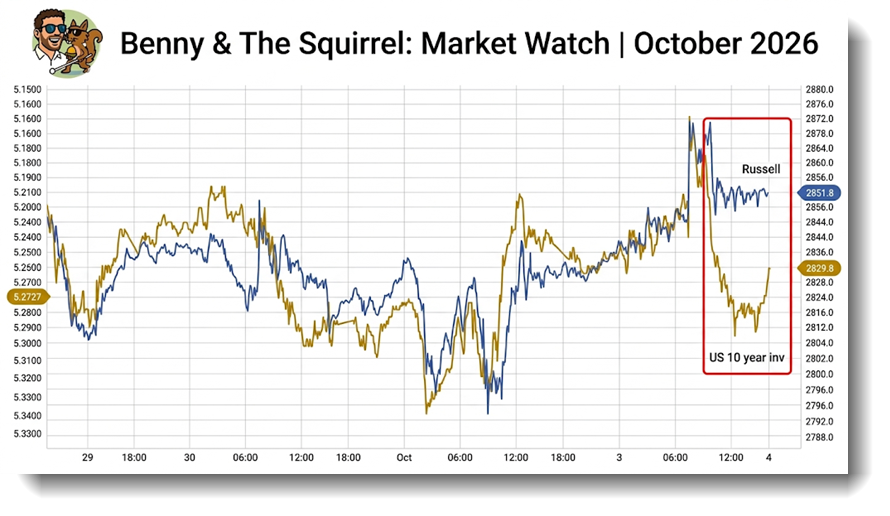
Russell held up during Friday’s rates flush because the index is now loaded with AI second-derivative names, not “our grandfather’s Russell”
Bank of America’s “AI put” framing: AI capex offsets weakness in the median consumer and corporation
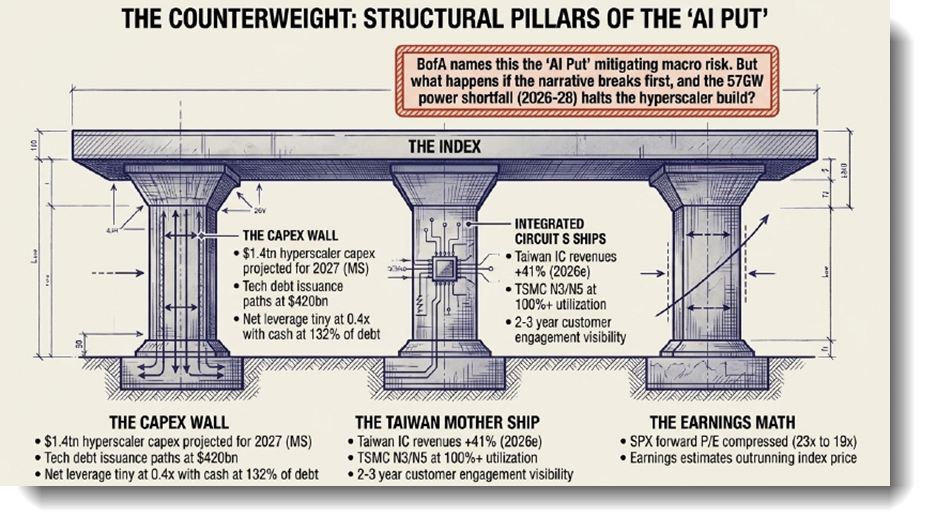
Friday’s price action read as a rates clearing event (someone carried out), not a fundamental signal
Cracks in Credit (Minute 18)
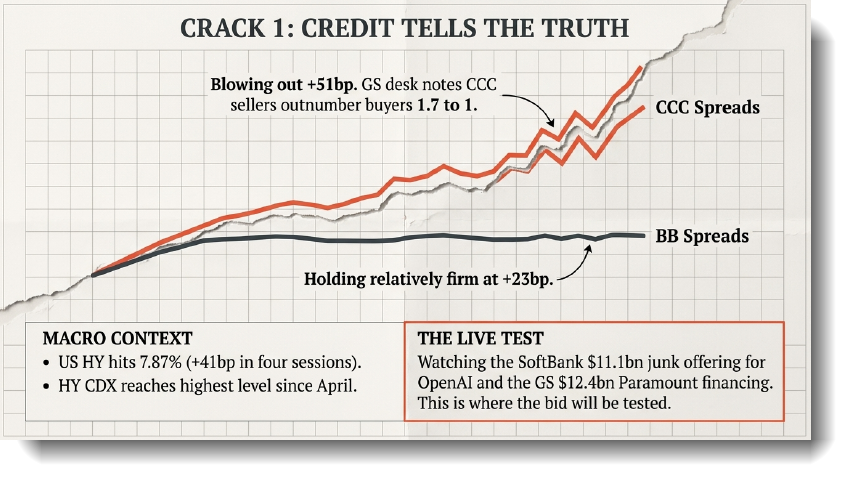
Triple-Cs and private credit deteriorating, with dealers effectively making their own markets
European banks gave back a quarter of their year-to-date returns in 72 hours at the start of the quarter
New issue stress: Paramount opened 6 points under; SpaceX also traded poorly, while Nvidia and Amazon deals held firm
Anthropic IPO flagged as a critical test: US markets cannot afford it to be pulled after OpenAI’s withdrawal; the “tourniquet” on liquidity may need to loosen around the October Fed meeting to preserve it
Contested election risk, and positioning (Minute 25)
Historical pattern of post-midterm equity strength, with the only failures tied to oil/inflation spikes (Suez, 1973-74)
Key mispricing: options markets underweight a contested election scenario, including a possible refusal to seat new members in January; suggested trade is funding December/January SPX puts with November election vol
Duration avoided despite 5%+ nominal yields; preference for 2-year paper and reinvestment risk, with TIPS-derived real rates dismissed as too illiquid to trust
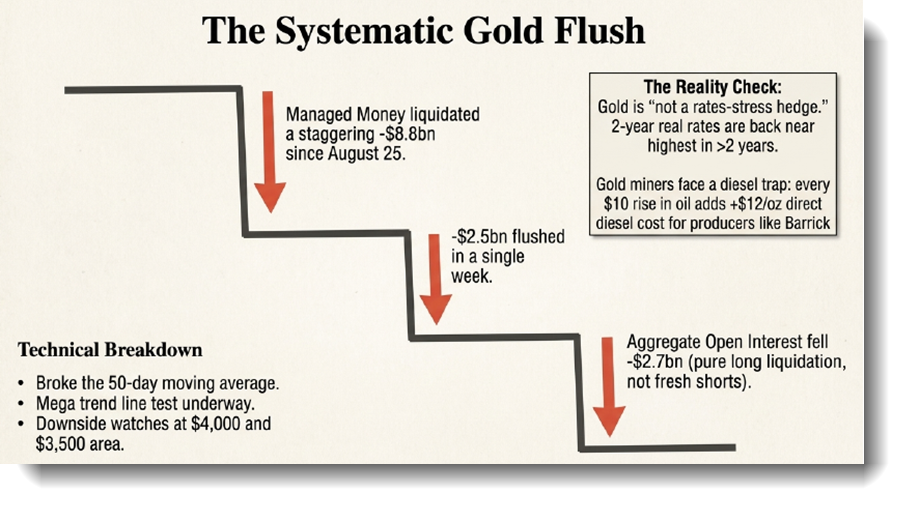
Gold favored over 10s and 30s at $4,100: real rates no longer drive it
If you act on anything provided in this newsletter, you agree to the terms in this disclaimer. Everything in this newsletter is for educational and entertainment purposes only and NOT investment advice. Nothing in this newsletter is an offer to sell or to buy any security. The author is not responsible for any financial loss you may incur by acting on any information provided in this newsletter. Before making any investment decisions, talk to a financial advisor.


