

This week broke most correlations in the book!
Show Notes
Correlation chaos
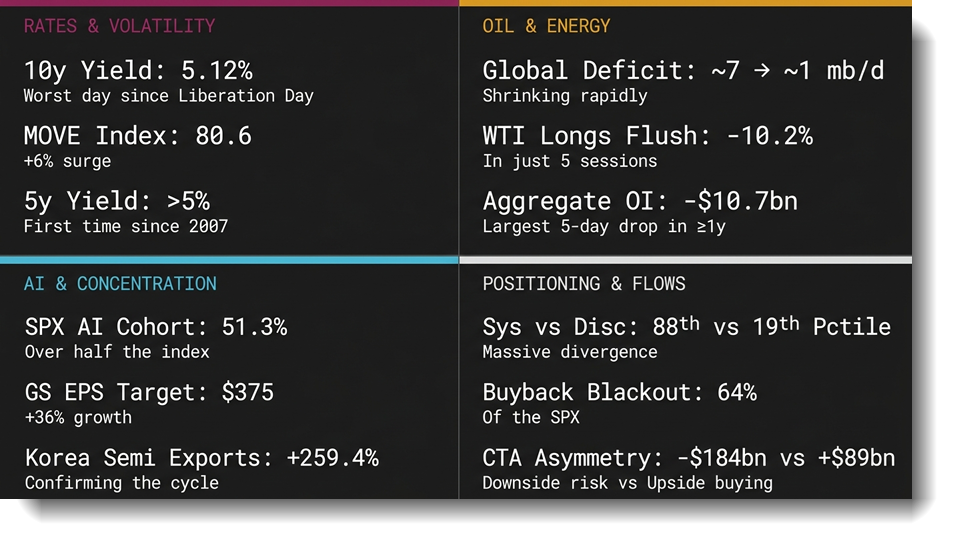
The theme of the week is market divergences and breaking correlations
Correlation breakdowns are hurting levered macro and pod shops; unlevered beta investors unaffected; machine models handle slow correlation shifts but not fast ones. Heavy “taps on the shoulder” in fixed income relative value pod shop world
Benny reiterates his bond bull call from prior weeks despite rates rising since; long end blew through 5 percent and payer swaptions are expensive with few willing sellers
Treasury market now in “price discovery” mode; the level of yields, not just rate of change, suddenly matters
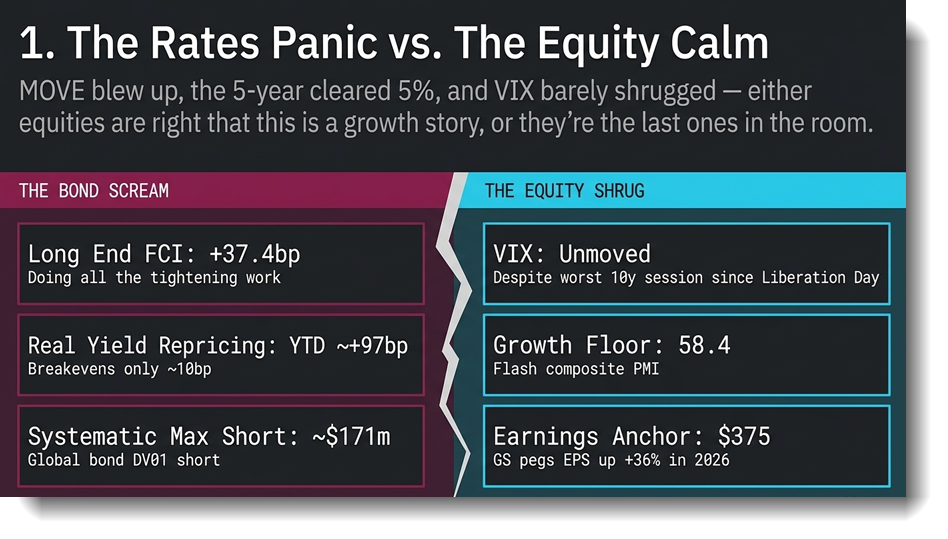
Why equities have not blown out despite rising rates: markets run in regimes, the 1970s saw stocks and rates rise together, and the post 2022 regime still has more COVID era liquidity and credit capacity than expected
“Zombie return of risk parity” - stock bond inverse correlation reappeared this week for the first time in years
Dominant narrative is US growth beating expectations on data center capex; a cohort believes Warsh has two to three more hikes in him
Capex booms flatter earnings via capitalized costs versus fully recognized revenue; Julian Robertson’s 1998 fund closure cited as precedent for being right too early
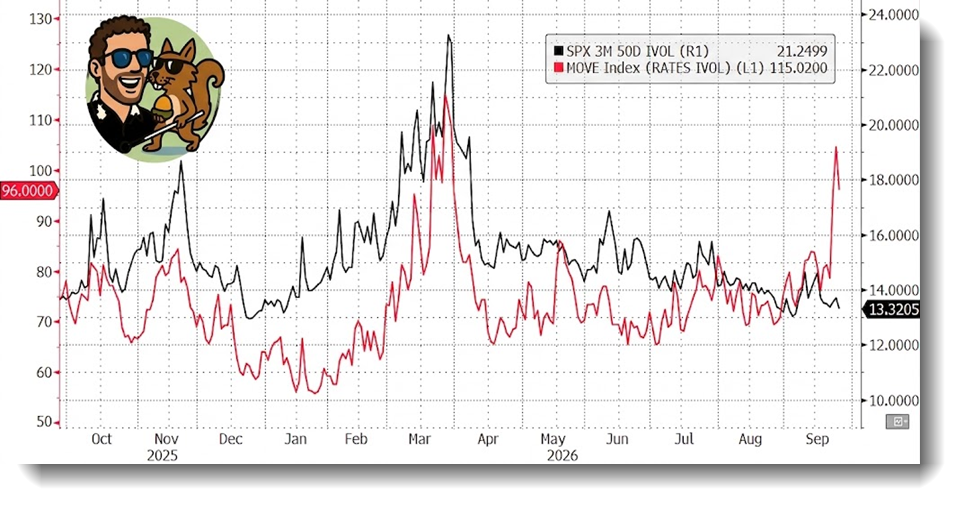
S&P implied vol calm at 13 while MOVE index exploded; equities falling as bond vol spikes
Positioning and fiscal dynamics (Minute 10)
The Squirrel bought more bonds this week; over 15 percent of his NAV is in trend followers currently max short fixed income, so a long adds some balance
Administration likely to intervene in markets; Benny’s biggest career mistake was fighting the machine post GFC
Bond market signaling it may not fund deficits indefinitely; must think dynamically about how a yield spike forces private capex cuts that then roll growth over
Squirrel believes hyperscaler spenders will blink earlier than consensus; the economy ex data center capex is in much worse shape
September hike may, with hindsight, prove the one that pushed things over the edge; consistent with historical Fed “death shot” behavior
AI capex and Meta (Minute 13)
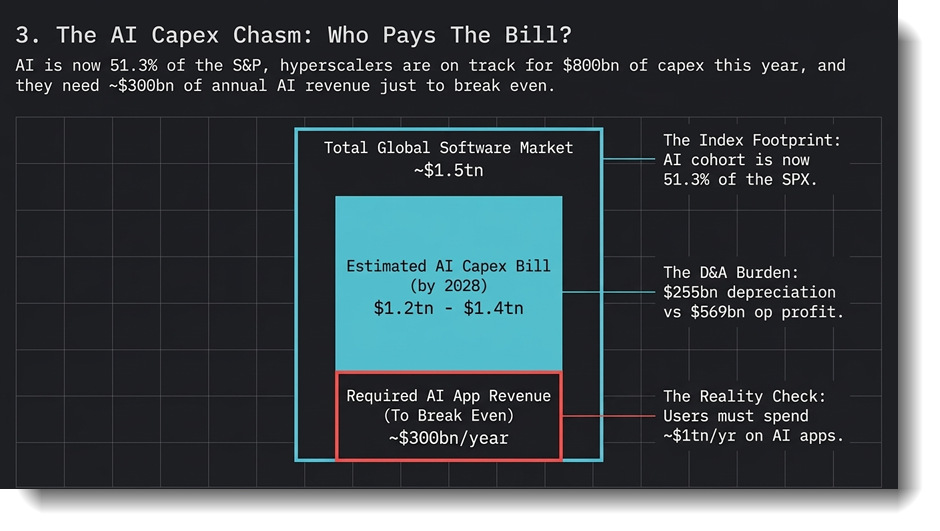
AI on and off balance sheet commitments now $3.3 trillion, 40% higher than the roughly 2 trillion figure cited on the pod three months ago; Latest weekly AI capex token pricing monitors here 👇.

Maintenance capex keeps rising; hyperscalers need real revenue, hence Anthropic deals with Salesforce and Accenture and OpenAI being the fastest ever to $1 billion of ad revenue; target pools are $1 trillion of global advertising and $1.5 trillion of software
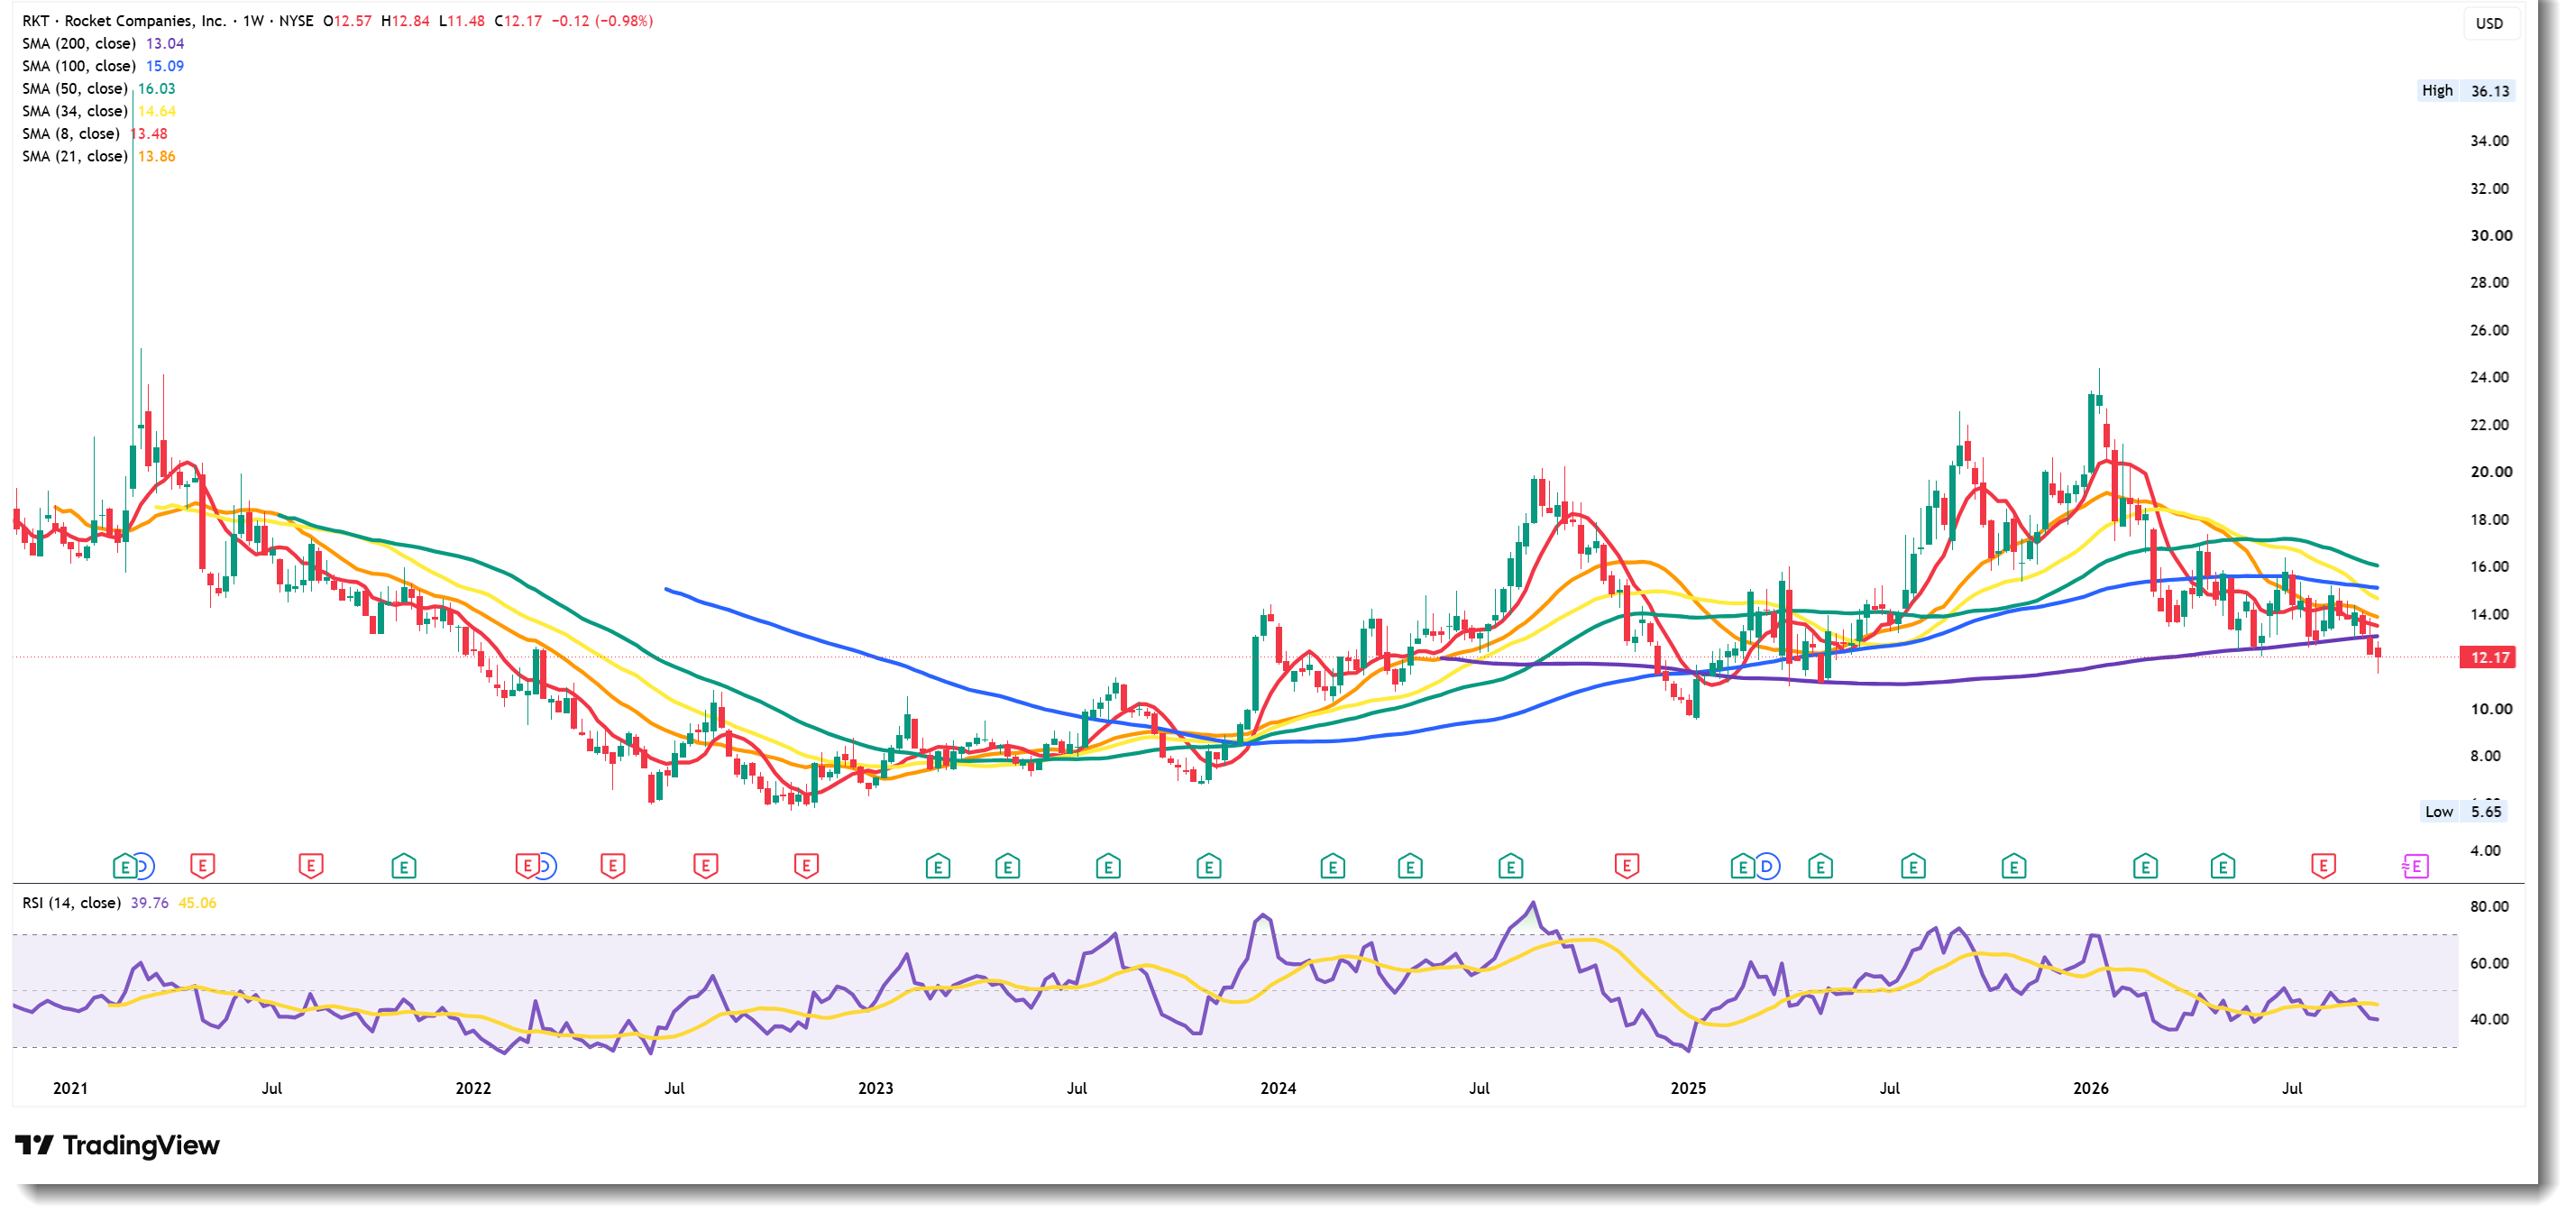
Tale of two sectors: S&P near all time highs with AI at roughly 51 percent of the index, while consumer, housing and rate sensitive names (Rocket Mortgage owned) sit near April 2025 Liberation Day lows
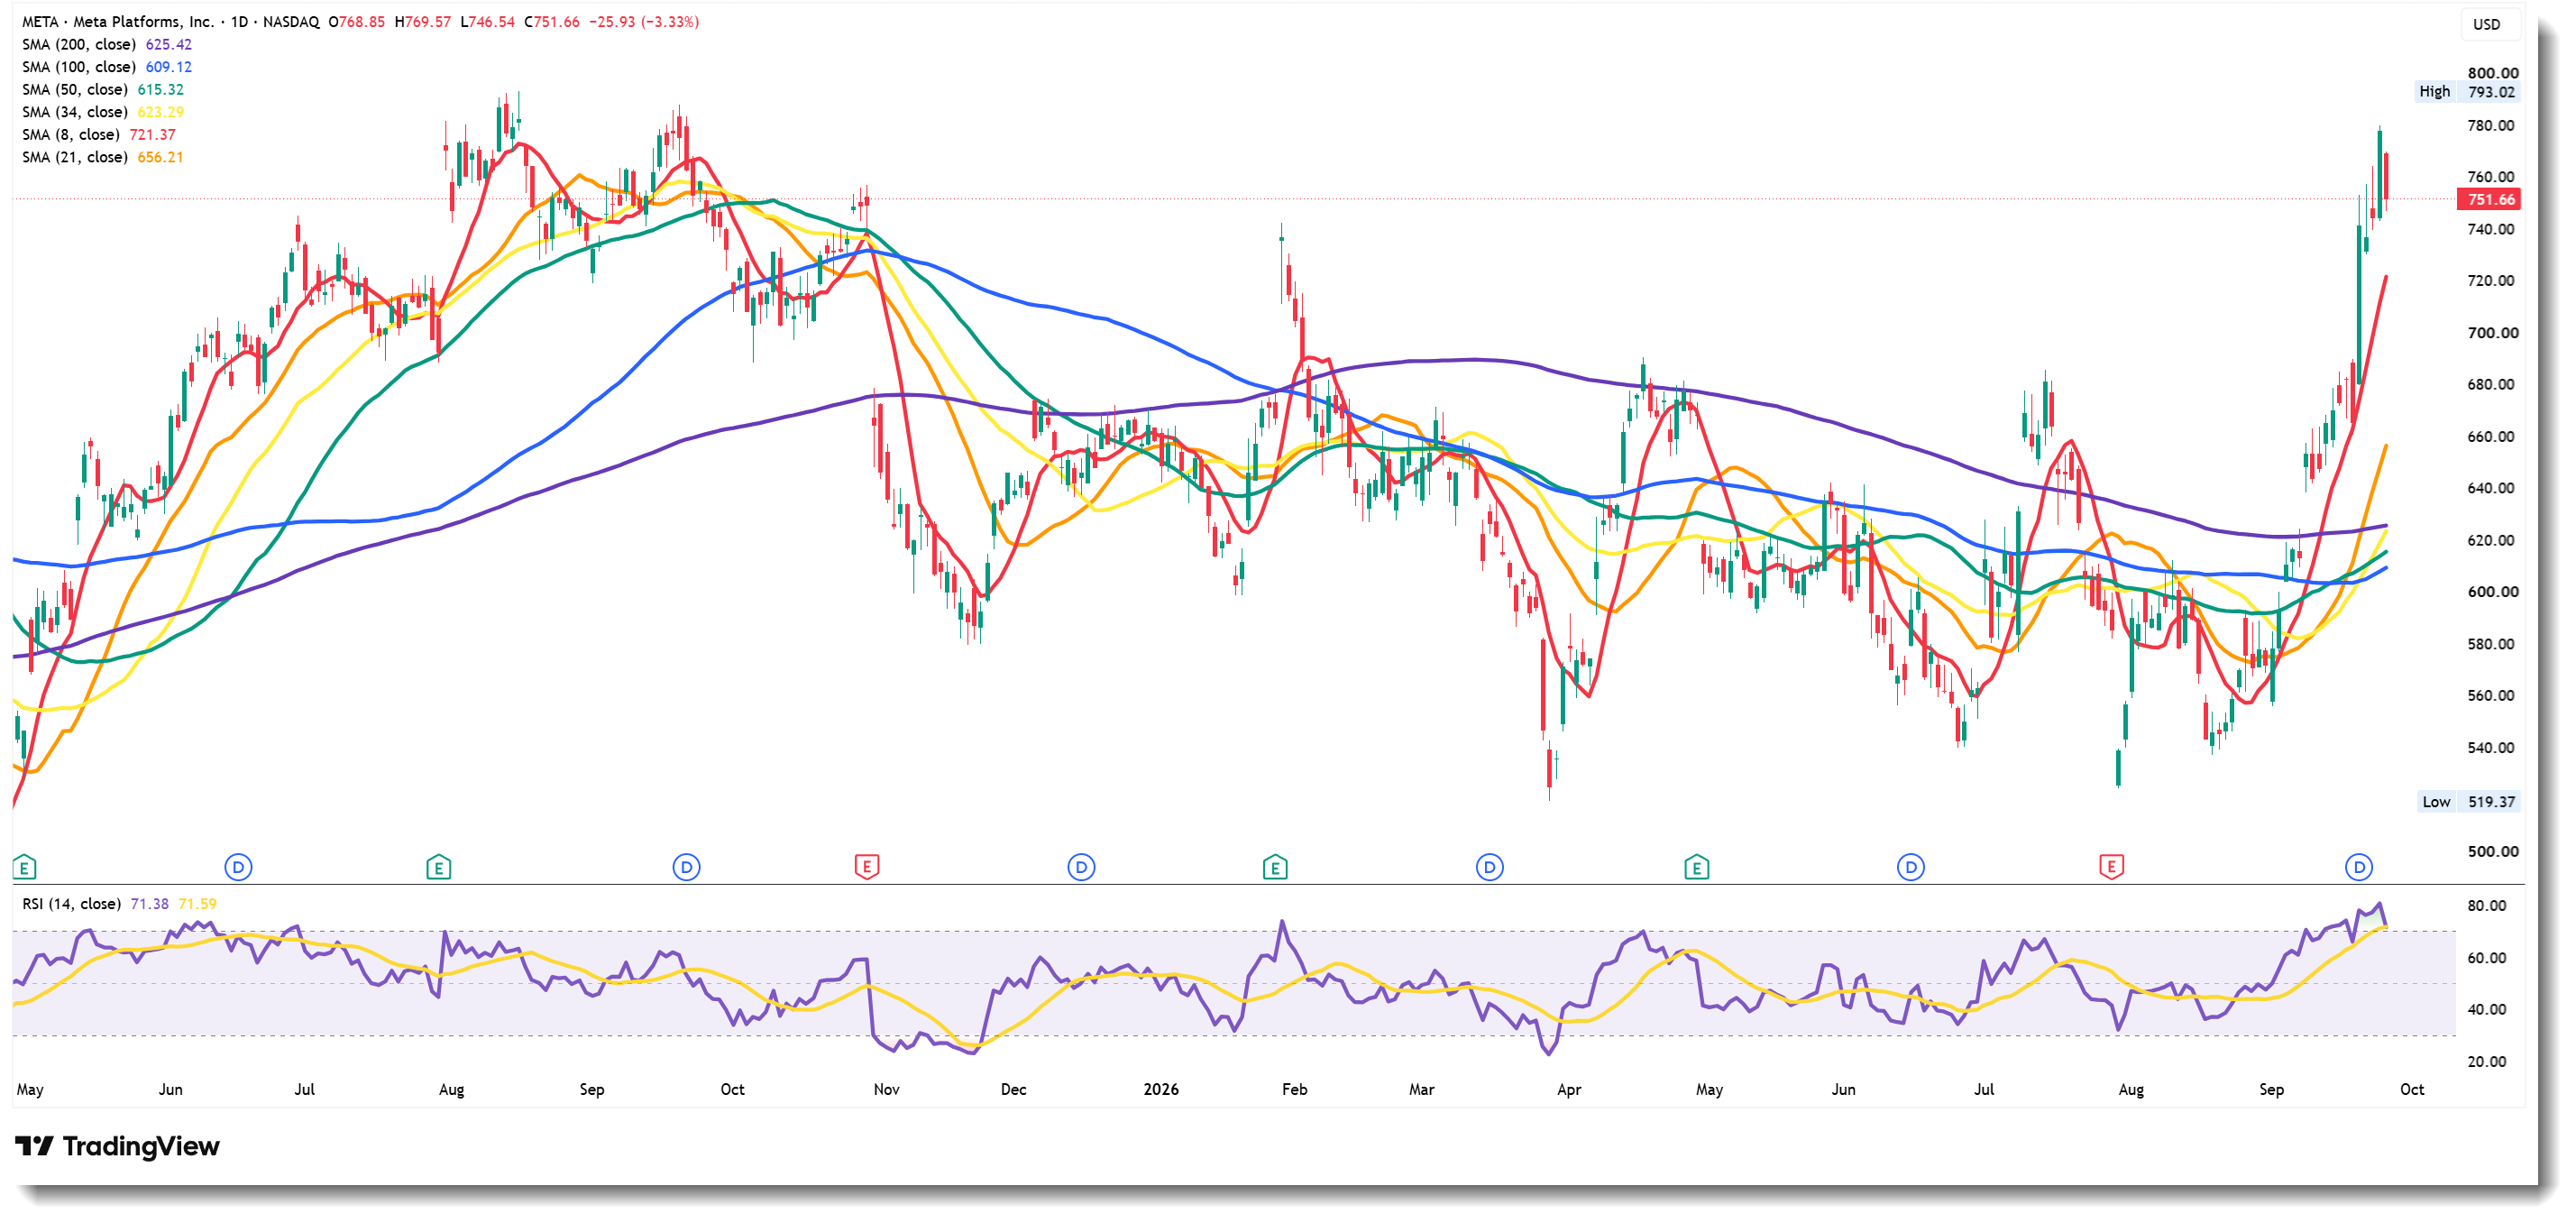
Meta’s Muse agent is the story of the week - Meta ticks all four boxes of data, distribution, brand and owned compute; stock ripped from a $519 post earnings low last summer to just under $800, mostly in two weeks, on heavy call buying
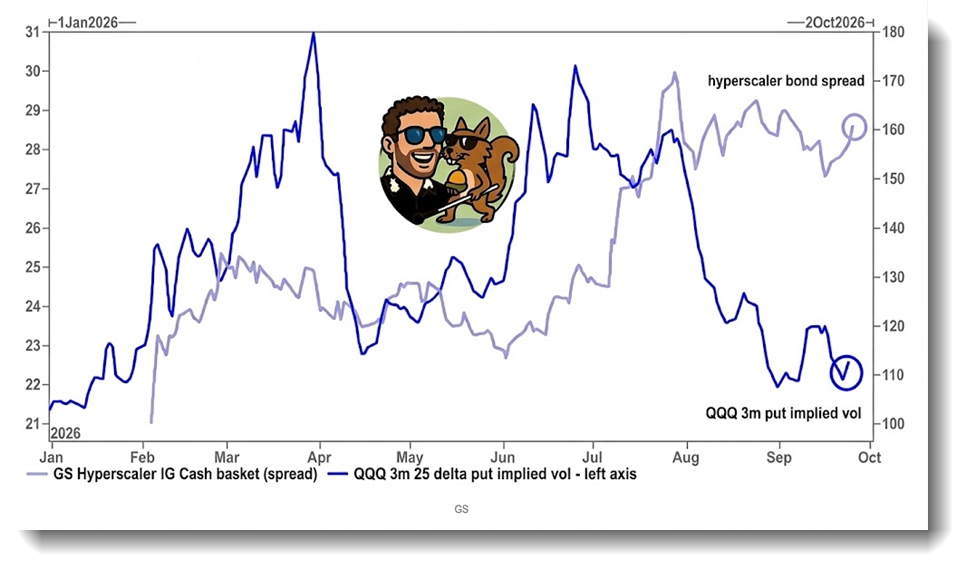
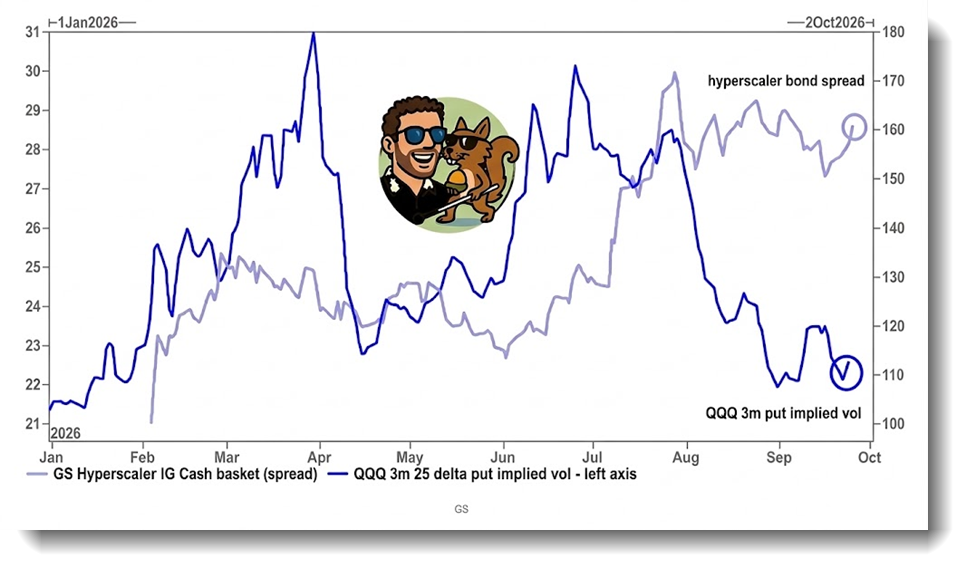
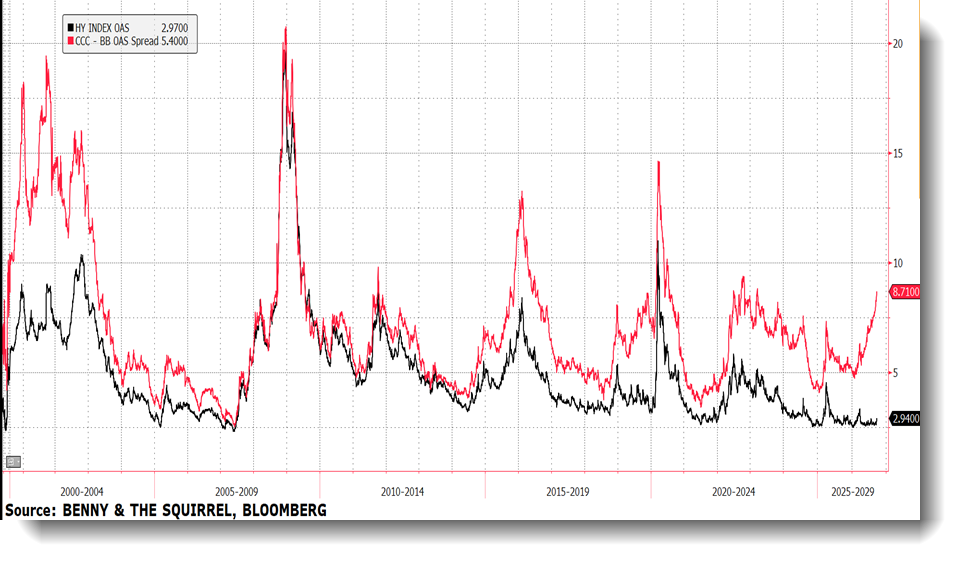
Divergence watch: Nasdaq vol crushed from 28 to 22, but credit is not confirming; CoreWeave spreads around +808bps versus +950bps prior - out from +460bps in May
Oracle declared force majeure on New Mexico power plants; Ellison pledged an extra $9.6 billion of stock against the Paramount deal
Crude Oil (Minute 22)
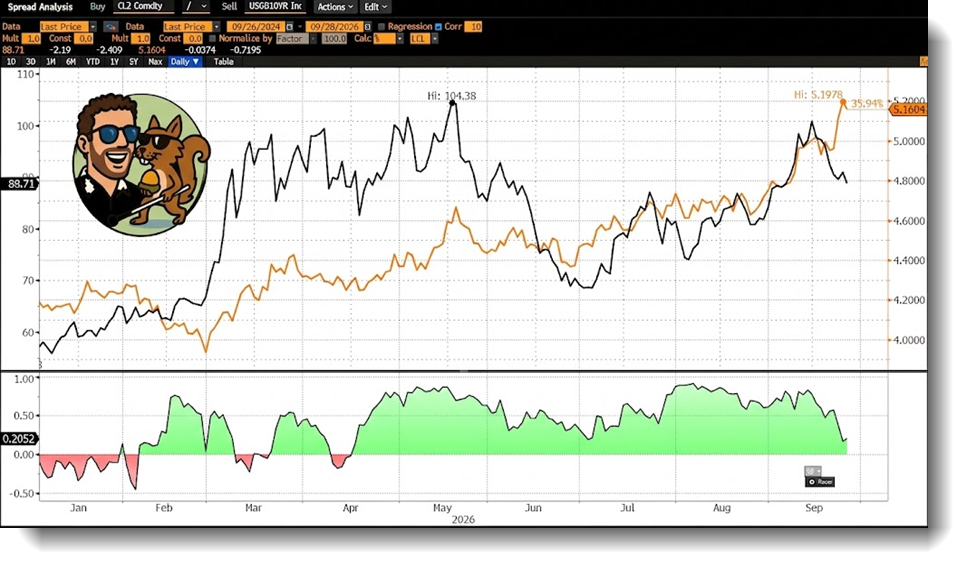
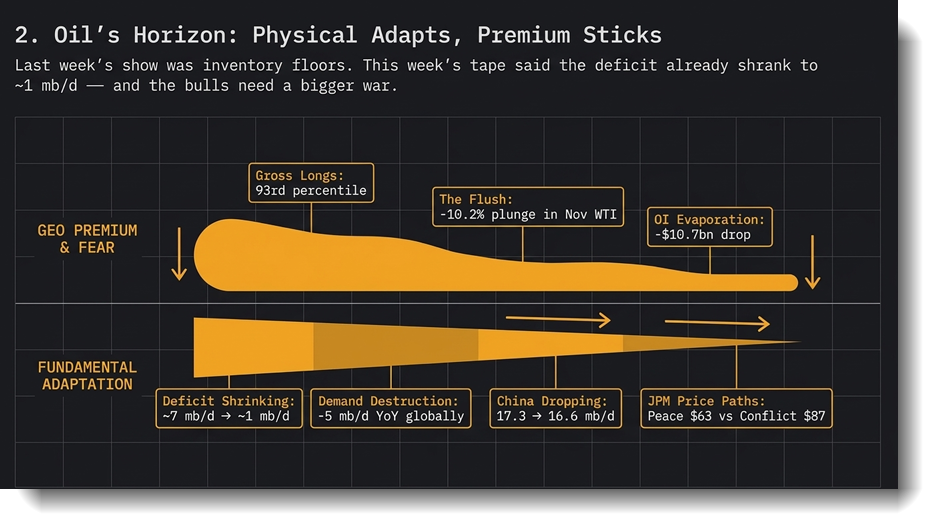
IEA flagged a shrinking global deficit and soft China demand; oil sold off while rates rose, another divergence on the chart versus the 10 year note
Squirrel is much smaller in front month crude than a few weeks ago; holds roughly 5% of NAV in BNO 0.00%↑ but advises new entrants to be appreciably smaller - more comfortable underwriting energy equities than the physical commodity here
Agentic AI and banks (Minute 25)
🐿️ just back from four days at a conference in the Peloponnese, Greece where he presented on agentic AI finance bots and bank deposit franchises
Around $23 trillion of global bank deposits earn zero interest, worth roughly $170 billion of net interest income to global commercial banks; Muse going mainstream at the beginning of last week made the 🐿️’s month-old slides feel a bit stale
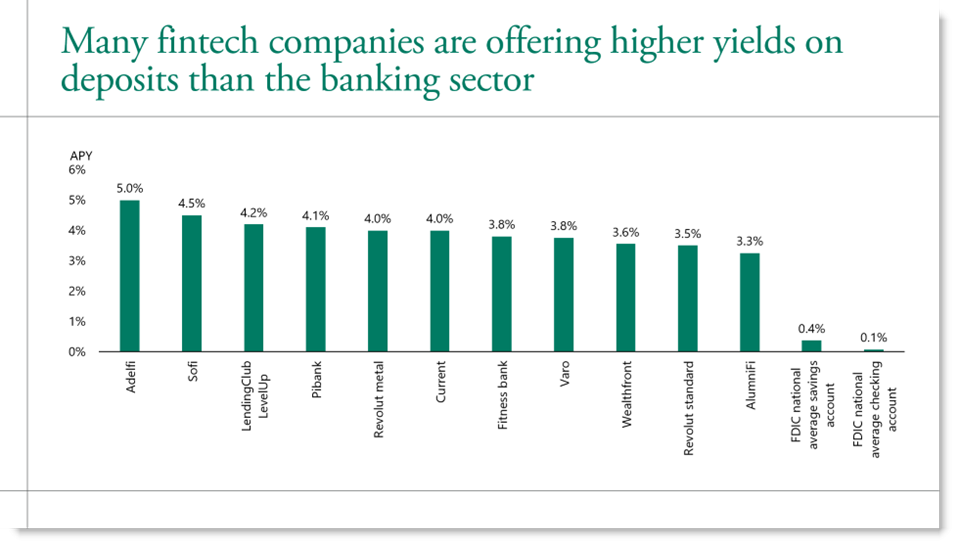
Apollo’s Torsten Slok chart shows fintechs like SoFi and Interactive Brokers paying around 4% on cash versus legacy deposit franchises; classic Silicon Valley overpaying for market share, but frictionless finance bots do pose a real threat to deposit inertia
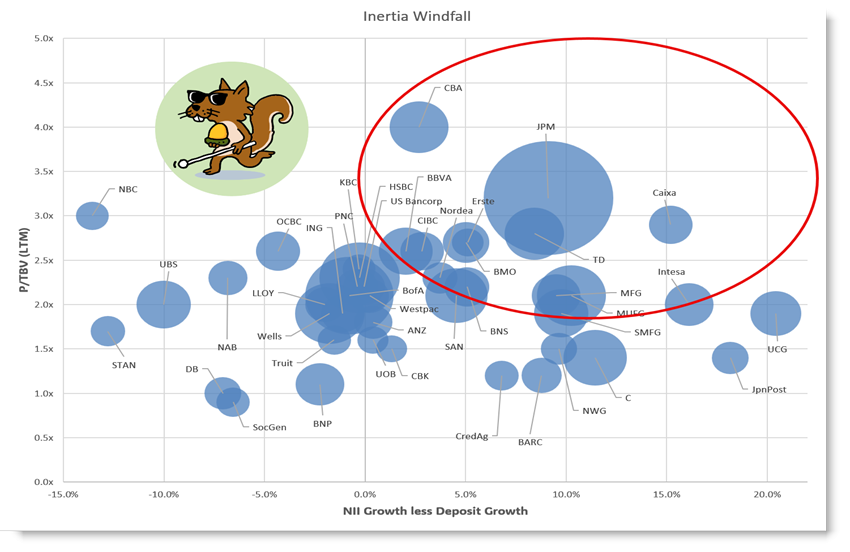
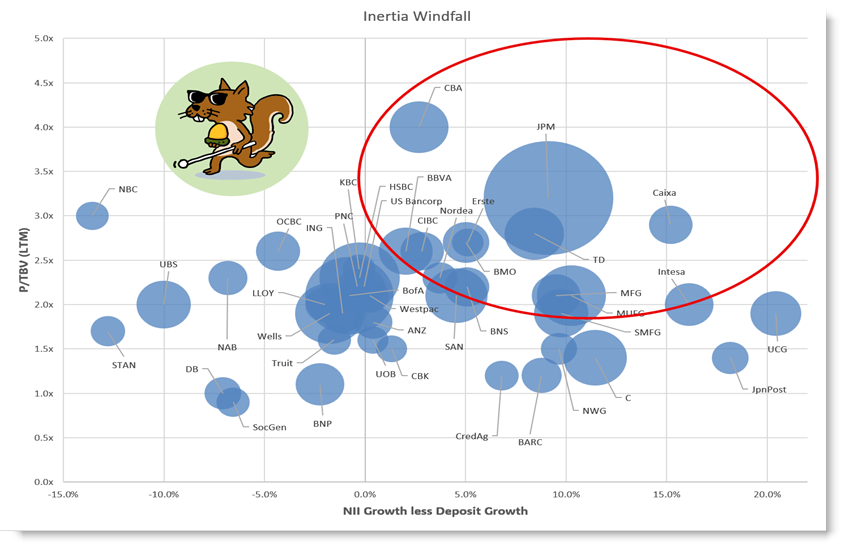
Killer chart: net interest income growth minus deposit growth over four years against price to tangible book; banks in the red circle are most at risk of deposit franchise devaluation; big subscriber note coming
Important to look at the entire financials complex through the prism
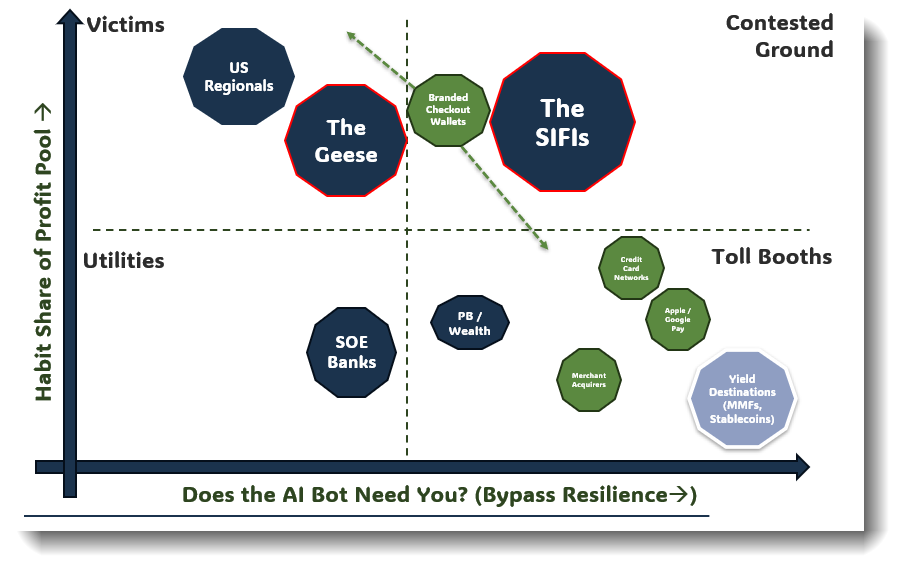
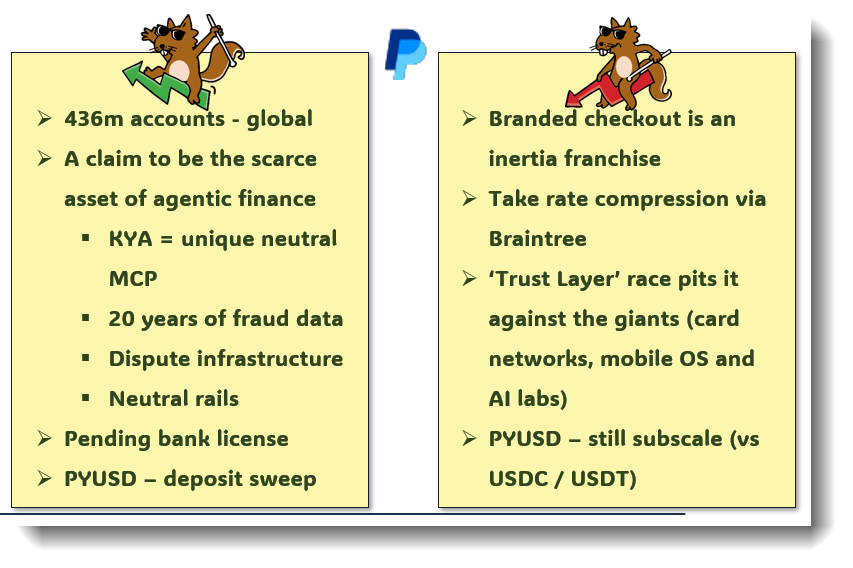
On this note, PayPal is the classic battleground stock: binary outcome justifies the compressed 9x times PE - Benny already owns it.
If you act on anything provided in this newsletter, you agree to the terms in this disclaimer. Everything in this newsletter is for educational and entertainment purposes only and NOT investment advice. Nothing in this newsletter is an offer to sell or to buy any security. The author is not responsible for any financial loss you may incur by acting on any information provided in this newsletter. Before making any investment decisions, talk to a financial advisor.


